Textile and Apparel Sector in the 2016 U.S. Trade Policy Agenda

2

In the recently released 2016 President’s Trade Agenda, the textile and apparel (T&A) sector was mentioned four times (up from only once in 2015*):

1.Trade enforcement

“THE OBAMA ADMINISTRATION has a record of trade enforcement victories that have helped to level the playing field for American workers, businesses, farmers, and ranchers. In 2016, we will continue to aggressively pursue a robust trade enforcement agenda, including by using new and stronger tools under the bipartisan Trade Enforcement Act of 2015 to hold our trading partners accountable.

Ongoing disputes include challenges to:

  • China’s far-reaching export subsidy program extending across sectors and dozens of sub-sectors, including textiles, industrial and agricultural products.”

2.Trade preference programs

“Haitian Hemispheric Opportunity through Partnership Encouragement Act (HOPE) pro­gram, which supports nearly $900 million in garment imports from Haiti, is an essen­tial support for Haiti’s long-term economic growth and industrial development. HOPE supports thousands of jobs in Haiti’s textile and gar­ment sectors, while providing important pro­tections to workers. Early extension of this program will provide the necessary stability and continuity for companies to continue in­vesting in Haiti’s future.”

3.Benefits of trade to the American people

“More recent trends are similar, with families steadily gaining purchasing power as the price of traded goods, such as smart phones, apparel, and toys, falls. While all households benefit, the gains from trade have predominantly benefited lower-income Americans, who spend a greater portion of their incomes on highly-traded staples like food, shoes, and clothing.”

4.Trade and labor

Our engagement has produced an Imple­mentation Plan Related to Working and Liv­ing Conditions of Workers that is helping to address concerns about workers’ rights and working conditions in Jordan’s garment sec­tor, particularly with respect to foreign work­ers. Jordan has issued new standards for dormitory inspections, submitted new labor legislation to its parliament and hired new labor inspectors. USTR and Department of Labor continue to work with Jordan on the issues under the Plan.

Overall, it seems:1) Reflecting the global nature of the sector, T&A is a topic that involves multiple trading parties for the United States; 2) Economic development and foreign aid are important elements in the U.S. trade policy for T&A. 3) Social responsibility and labor practices in the T&A sector remain a grave concern and need further improvement through international collaborations. 4) The T&A sector is involved in some topics with divisive public opinions, such as the impact of imports.

* Textile and apparel mentioned in the 2015 U.S. Trade Policy Agenda:

Our engagement has produced an Implementation Plan Related to Working and Living Conditions of Workers that is helping to address concerns about workers’ rights and working conditions in Jordan’s garment sector, particularly with respect to foreign workers. Jordan has issued new standards for dormitory inspections, submitted new labor legislation to its parliament and hired new labor inspectors.

[Discussion is closed for this post]

Changes in the Final Text of TPP Regarding Textile and Apparel Rules of Origin

tpp

The final text of the Trans-Pacific Partnership (TPP) released by the New Zealand Foreign Affairs & Trade in January 2016 has made a few changes to the textiles and apparel specific rules of origin compared with the USTR version released in November 2015:

  1. “5407.94” is replaced by “5403.49”
  2. “or heading 54.08″ is replaced by ” or heading 54.04 through 54.08″
  3. Minor wording changes are made regarding 55.03 and 55.06-55.11
  4. TPP originating input of “54.04 through 54.07” is now required for 54.08 (Woven fabrics of artificial filament yarn, including woven fabrics obtained from materials of heading 5405)
  5. Rules of origin for HS96.19 (Sanitary towels (pads) and tampons, diapers and diaper liners for babies and similar articles, of any material are newly added.

Details of the changes can be downloaded from HERE

Top 10 Most Read FASH455 Blog Posts in 2015

top 10


1. Potential Impact of TPP on the Textile and Apparel Sector: A Summary of Recent Studies

2. 2014 World Textile Industry Labor Cost Comparison

3. Global Trade of Used Clothing (Updated: October 2015)

4. Market Size of the Global Textile and Apparel Industry: 2014 to 2018

5. When Will TPP Take Effect? Let’s look at the History

6. China to Become the World’s Largest Apparel Market in 2019

7. Are US Textile and Apparel Imports Using Free Trade Agreements?

8. 2015 US Fashion Industry Benchmarking Study Released

9. Exclusive Interview with Erin Ennis, Vice President, US-China Business Council

10. US Tariff Phaseout Schedule for Textile and Apparel in TPP by OTEXA Code

Textile and Apparel (T&A)-Specific Rules of Origin in TPP—Apparel Products

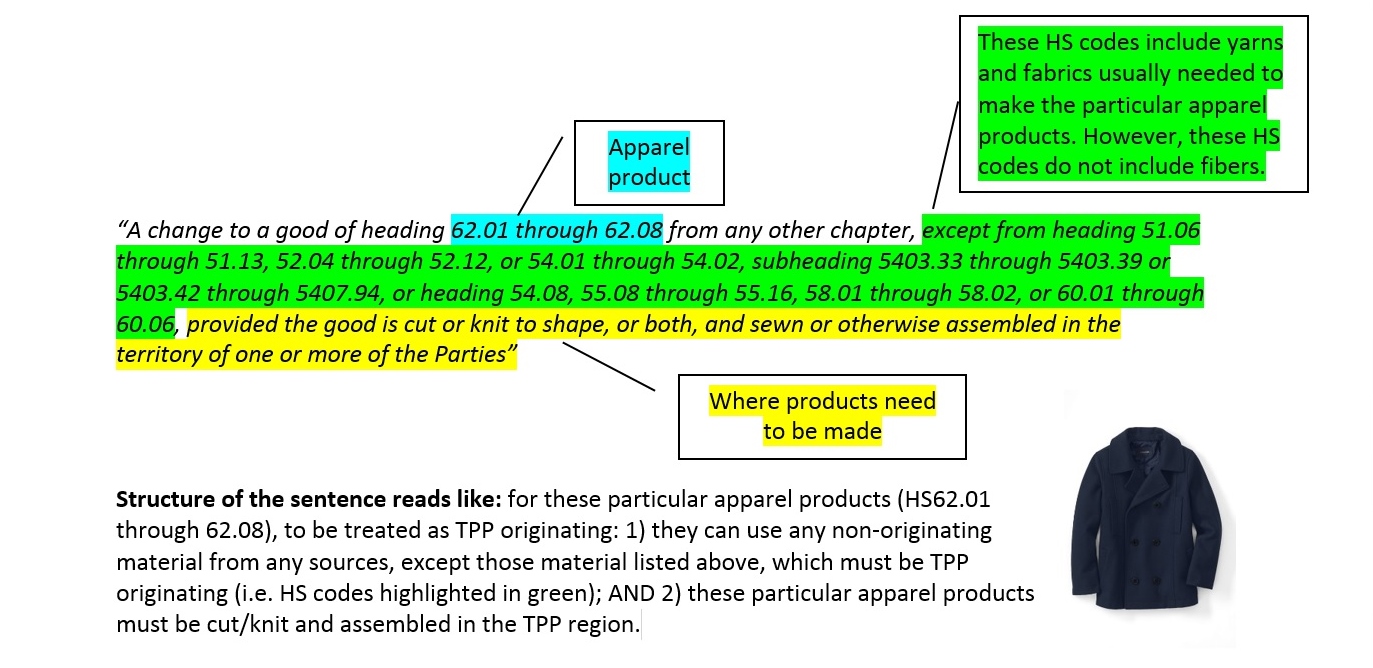
Textile and apparel (T&A)-specific rules of origin (RoO) for most apparel articles under TPP are known as the nickname “yarn forward”. “Yarn-forward “means preferential treatment under TPP will be allowed if the component determining classification meet BOTH the following two criteria:

  • knit or woven in TPP countries FROM yarn spun or extruded in TPP countries;
  • apparel is cut or knit to shape or both + sewn or otherwise assembled in TPP countries

In other words, “yarn forward” RoO not only requires the activity of apparel manufacturing must happen in one or more TPP countries, but also requires certain textile material used to make the apparel products must come from the TPP region.

The following is an example of how TPP describes “yarn-forward” rules of origin:

“A good is an originating good if it is produced entirely in one or more TPP countries by one or more producers using non-originating materials and each of the non-originating materials used in the production of the good satisfies any production process requirement, any applicable change in tariff classification requirement or any other requirement specified.”

yarn forward

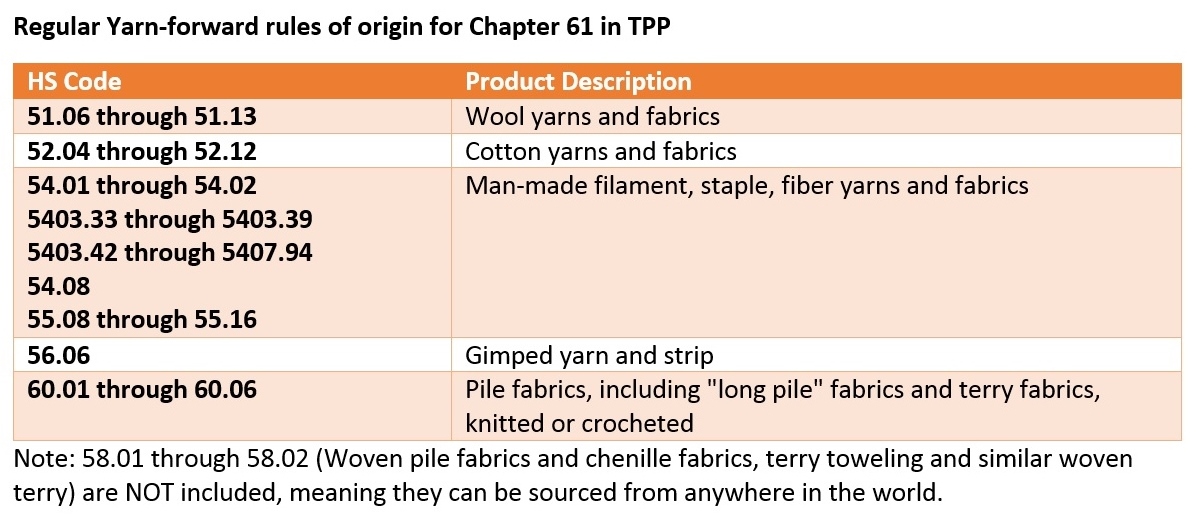
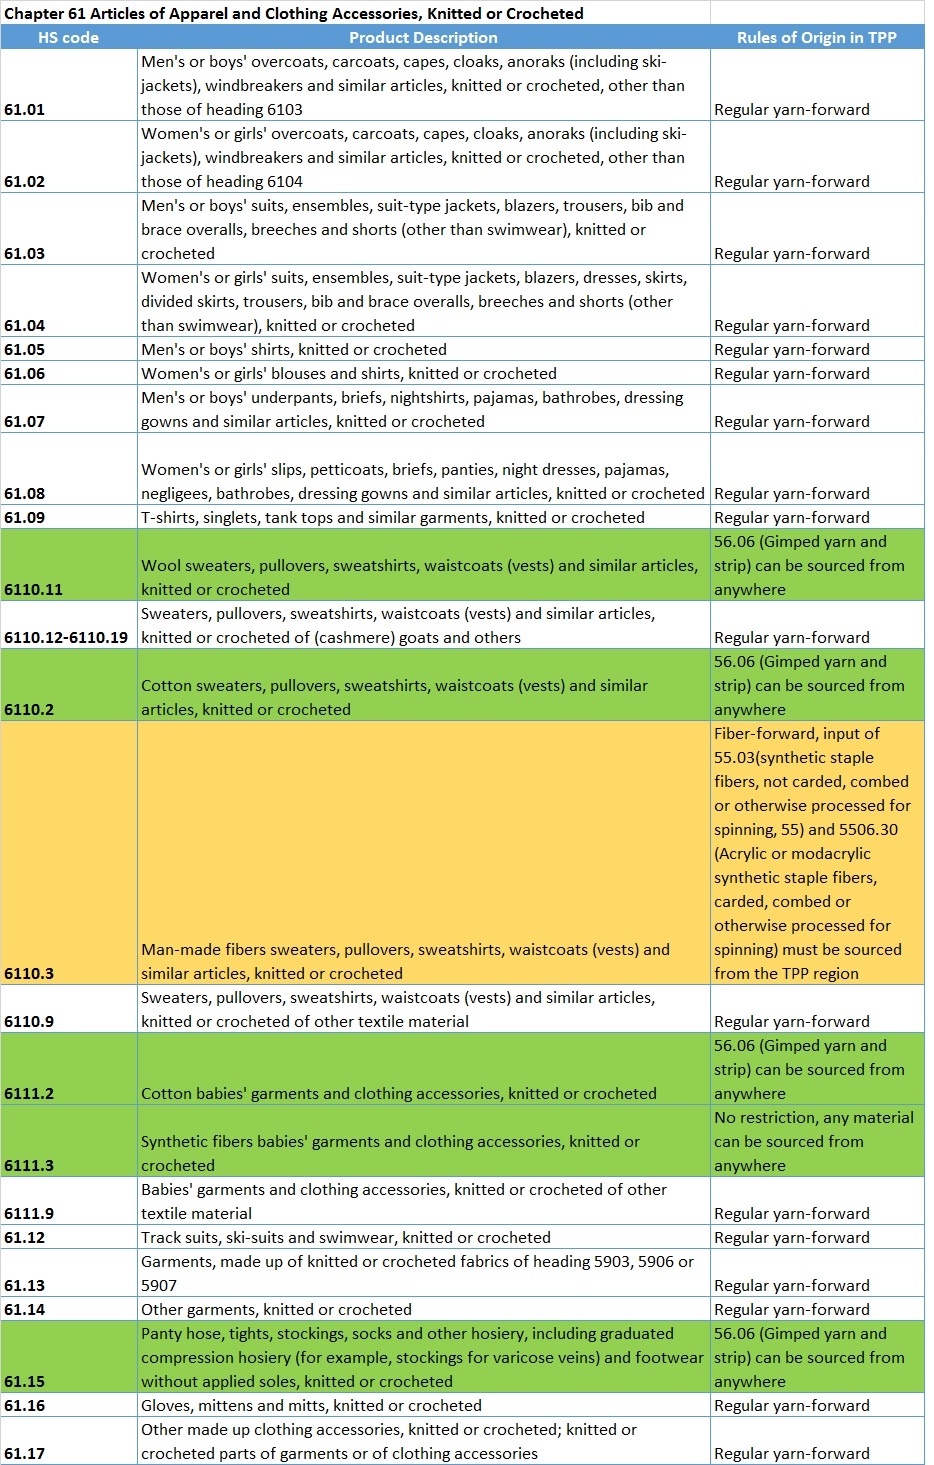
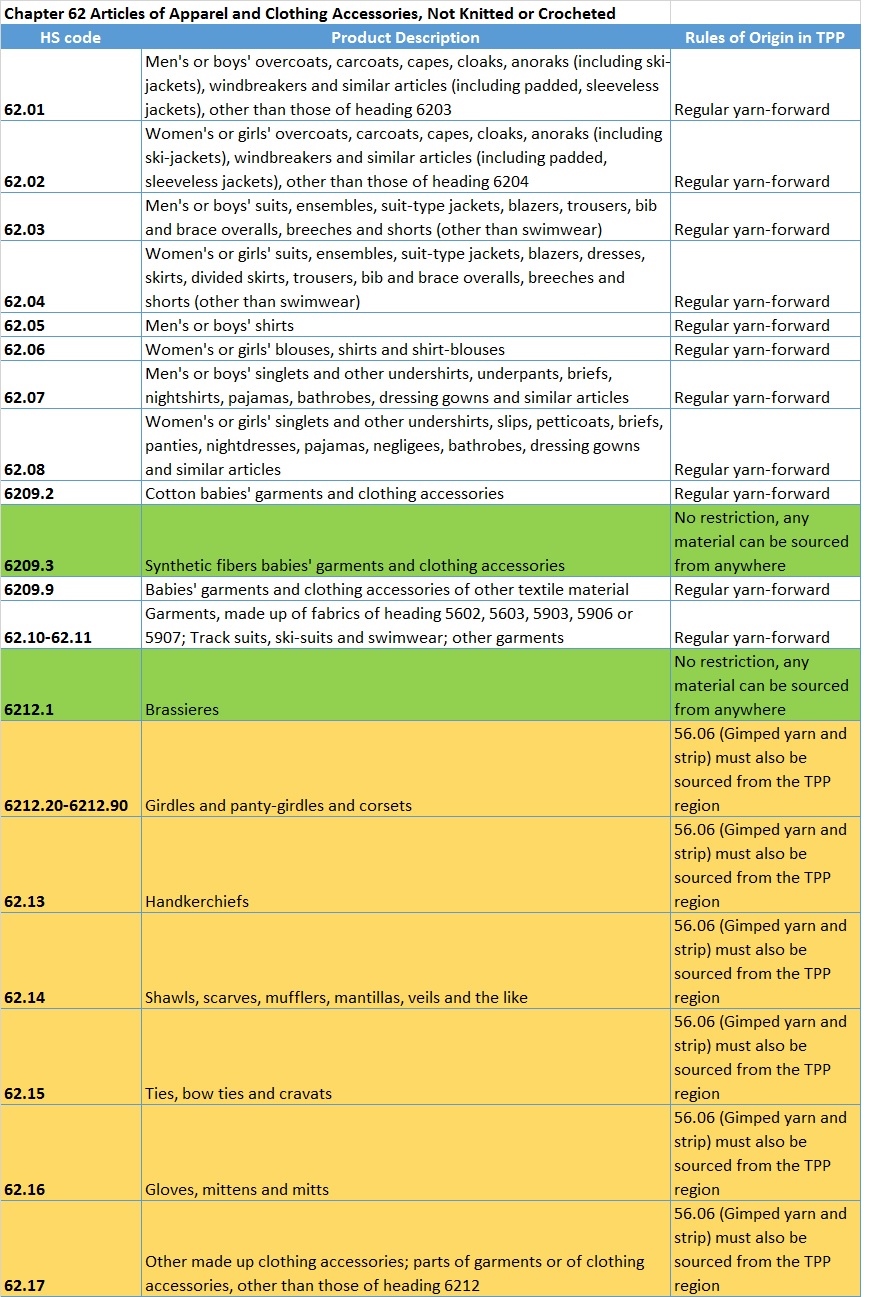
The followings are details of T&A-specific RoO for apparel products in TPP compiled based on released TPP text. “Regular yarn-forward” means all textile material listed in the table must be TPP originating. Overall, TPP allows much fewer exceptions to “yarn-forward” rules than most existing free trade agreements in the United States (such as NAFTA, CAFTA-DR, and Columbia Free Trade Agreement).

61 rule.jpg

61

62 rule.jpg

62

U.S. Department of Commerce Releases Factsheet on TPP and the U.S. Textile and Apparel Industry

textile_Page_1

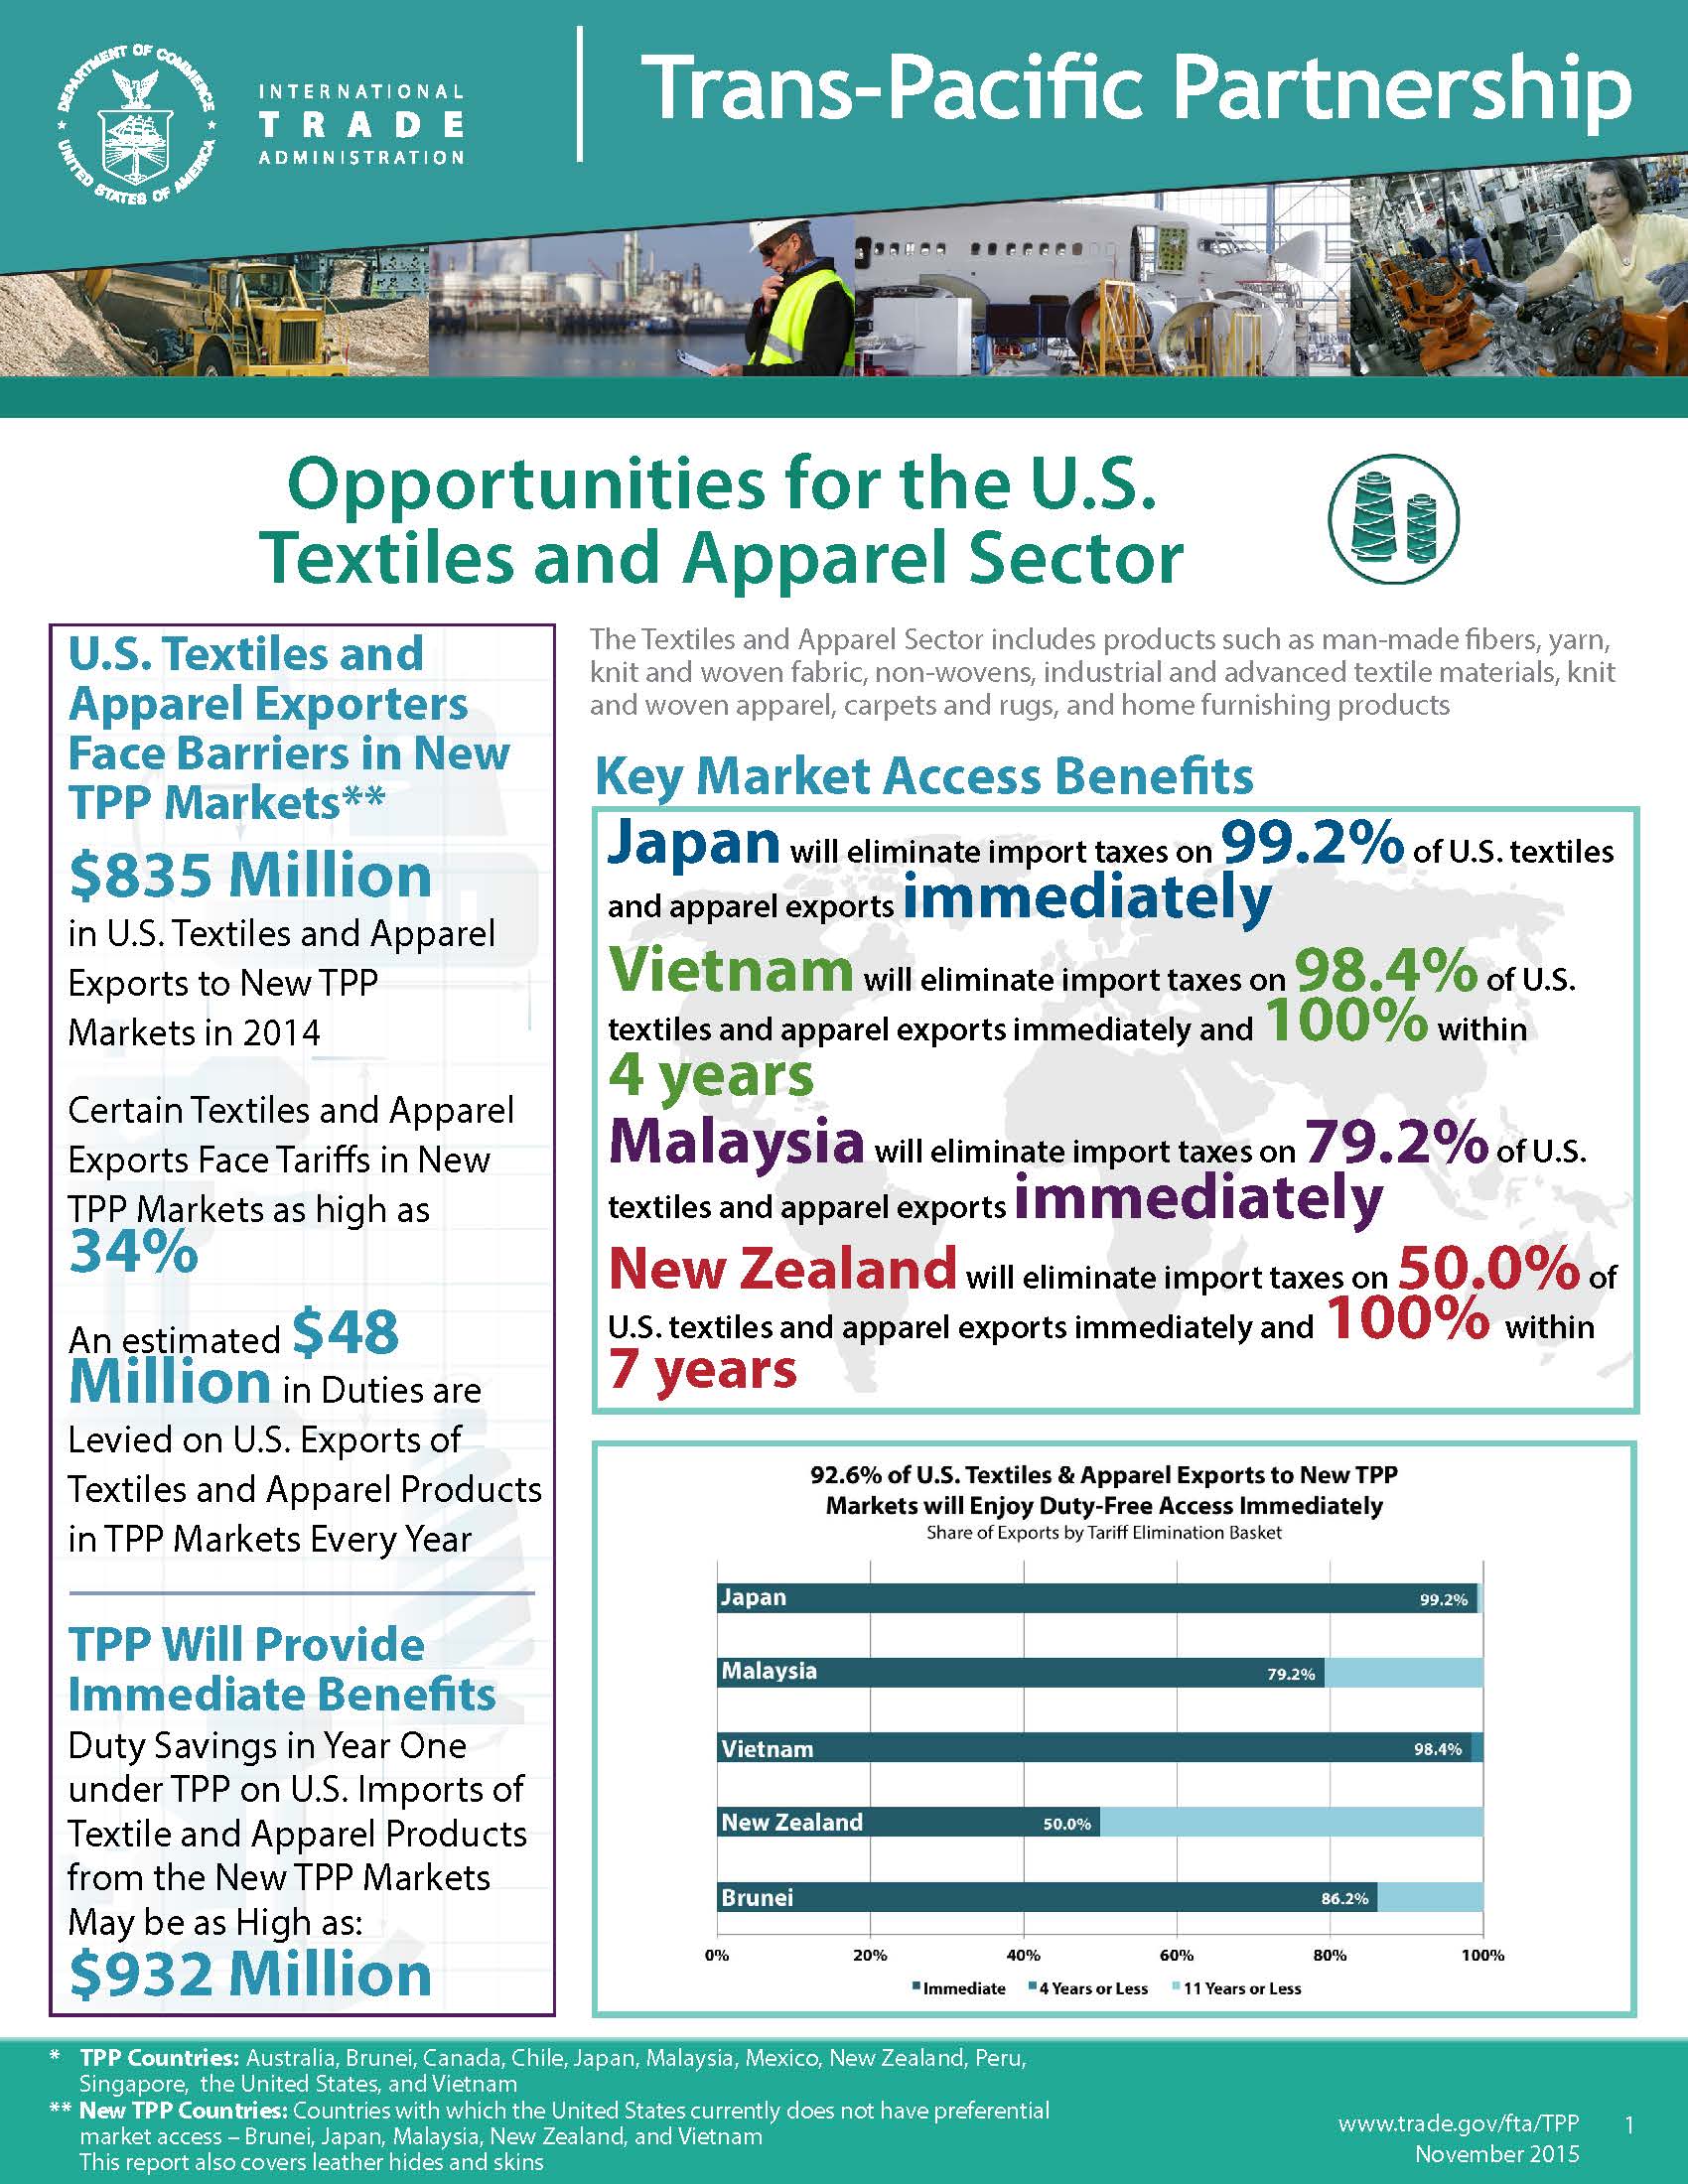
According to the factsheet released by the U.S. Department of Commerce, the Trans-Pacific Partnership (TPP) will create exciting new export opportunities for the U.S. textile and apparel (T&A) industry. The report highlights Vietnam and Japan as two promising markets in TPP for certain T&A products “Made in USA”, including:

Vietnam:

  • Cotton fiber, yarn, and Cotton woven Fabric (U.S. exported $394 million in 2014 with 16% market share only after China; tariff will be cut from 12% to zero on day one)
  • Non-woven fabrics (U.S. exported $23million in 2014, up 951% from 2009; tariff will be cut from 12% to zero on day one)

Japan

  • Synthetic fiber, yarn, and fabric (U.S. exported $61 million in 2014, up 61% from 2009; tariff will be cut from 2.7%-10% to zero on day one)
  • Industrial and advanced textile fabrics (U.S. exported $91 million in 2014, the fourth largest supplier after China, Taiwan, South Korea; tariff will be cut from 8.2% to zero on day one)
  • Men’s and boy’s apparel (U.S. exported $32.6milion in 2014, up 30.9% from 2009; tariff will be cut from 9.8% to zero on day one)

The factsheet also argues that TPP is a “balanced” deal for the U.S. T&A industry: long U.S. tariff phaseout schedule, strict “yarn-forward” rules of origin and textile safeguard mechanism in TPP will serve the interests of those stakeholders that seek protection of U.S. domestic T&A manufacturing, whereas duty savings from import tariff cut and the short supply list will create greater market access opportunities for U.S. fashion brands and retailers.

According to the report, the United States is the fourth largest textile exporter in the world. 54% of total U.S. T&A exports went to TPP markets in 2014. The United States is also the single largest importer of T&A in the world. 372,300 T&A manufacturing jobs remained in the United States in 2014.

US Tariff Phaseout Schedule for Textile and Apparel in TPP by OTEXA Code

[This post is updated on July 1, 2016]
Please also read:TPP tariff phase-out can steer Vietnam sourcing plans

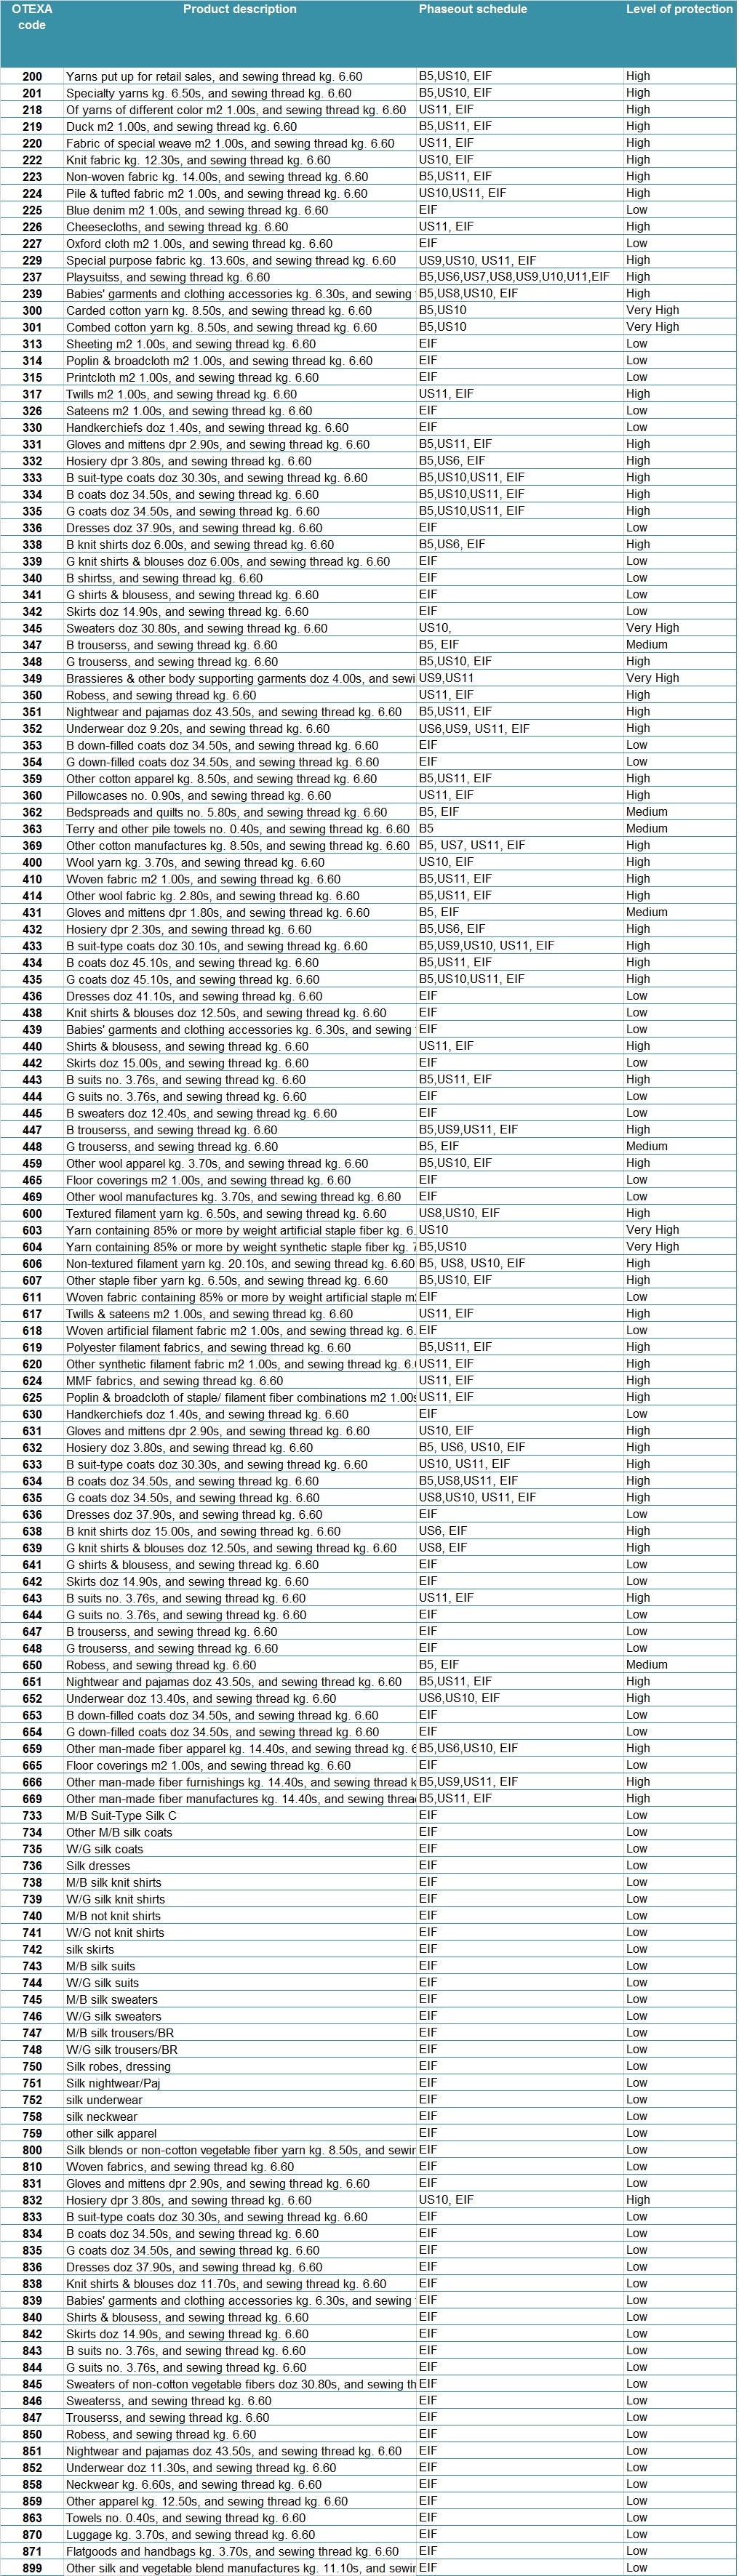
The United States includes as many as 38 different types of phaseout schedule in TPP and 8 of them apply to the textile and apparel (T&A) sector.

phaseout category

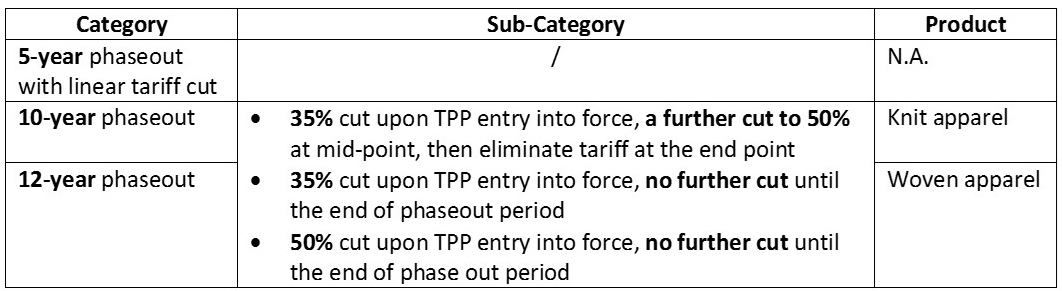
In general, T&A products with lower base tariff rate seem to be given more generous phaseout treatment than T&A that are subject to higher base tariff rate. For example, although T&A products under category EIF can immediately enjoy duty-free treatment once TPP takes into force, their base tariff rate is also the lowest (7.9% on average). In comparison, whereas T&A products under category US6, US7, US8 and US9 are subject to the highest base tariff rate, they are given the least generous tariff cut (i.e. 35%) once TPP takes into effect. This will makes average tariff rate applied to these products remain the highest almost throughout the whole phaseout period. It should be noted that even though US11 apparently seems to be the most restrictive phaseout category (i.e. 50% cut on day 1 and the resulting rate will remain unchanged until the end of year 12), its average tariff rate actually will be lower than phaseout category US6, US7, US8 and US9.

tariff

In the following table, the U.S. phaseout schedule for T&A in the released TPP text based on the 8-digit Harmonized System (HS) code is matched with the Office of Textiles and Apparel (OTEXA) product category. Results show that products equivalent to around 37.5% of the value of U.S. textile and apparel imports from Vietnam in 2015 will enjoy immediate duty-free treatment once TPP takes into force (i.e. EIF), approximately 4% will be subject to medium-level protection (i.e. EIF+B5) and 58.6% are under high (i.e. EIF+ any of the followings: US6, US7, US8, US9, US10, US11) or very high level of protection (i.e. any of the followings: US6, US7, US8, US9, US10, US11).

phaseout by OTEXA code

phaseout by trade data

Note: “Level of protection” in the above table is defined as the following: 1) Low level of protection: EIF only; 2) Medium level of protection: EIF+B5; 3) High level of protection: EIF+any of the followings: US6, US7, US8, US9, US10, US11; 4) Very high level of protection: any of the followings: US6, US7, US8, US9, US10, US11 only.

Sheng Lu


Tariff Remains a Critical Trade Barrier Worldwide for the Textile and Apparel Sector

1

tariff rate

According to data from the World Trade Organization:

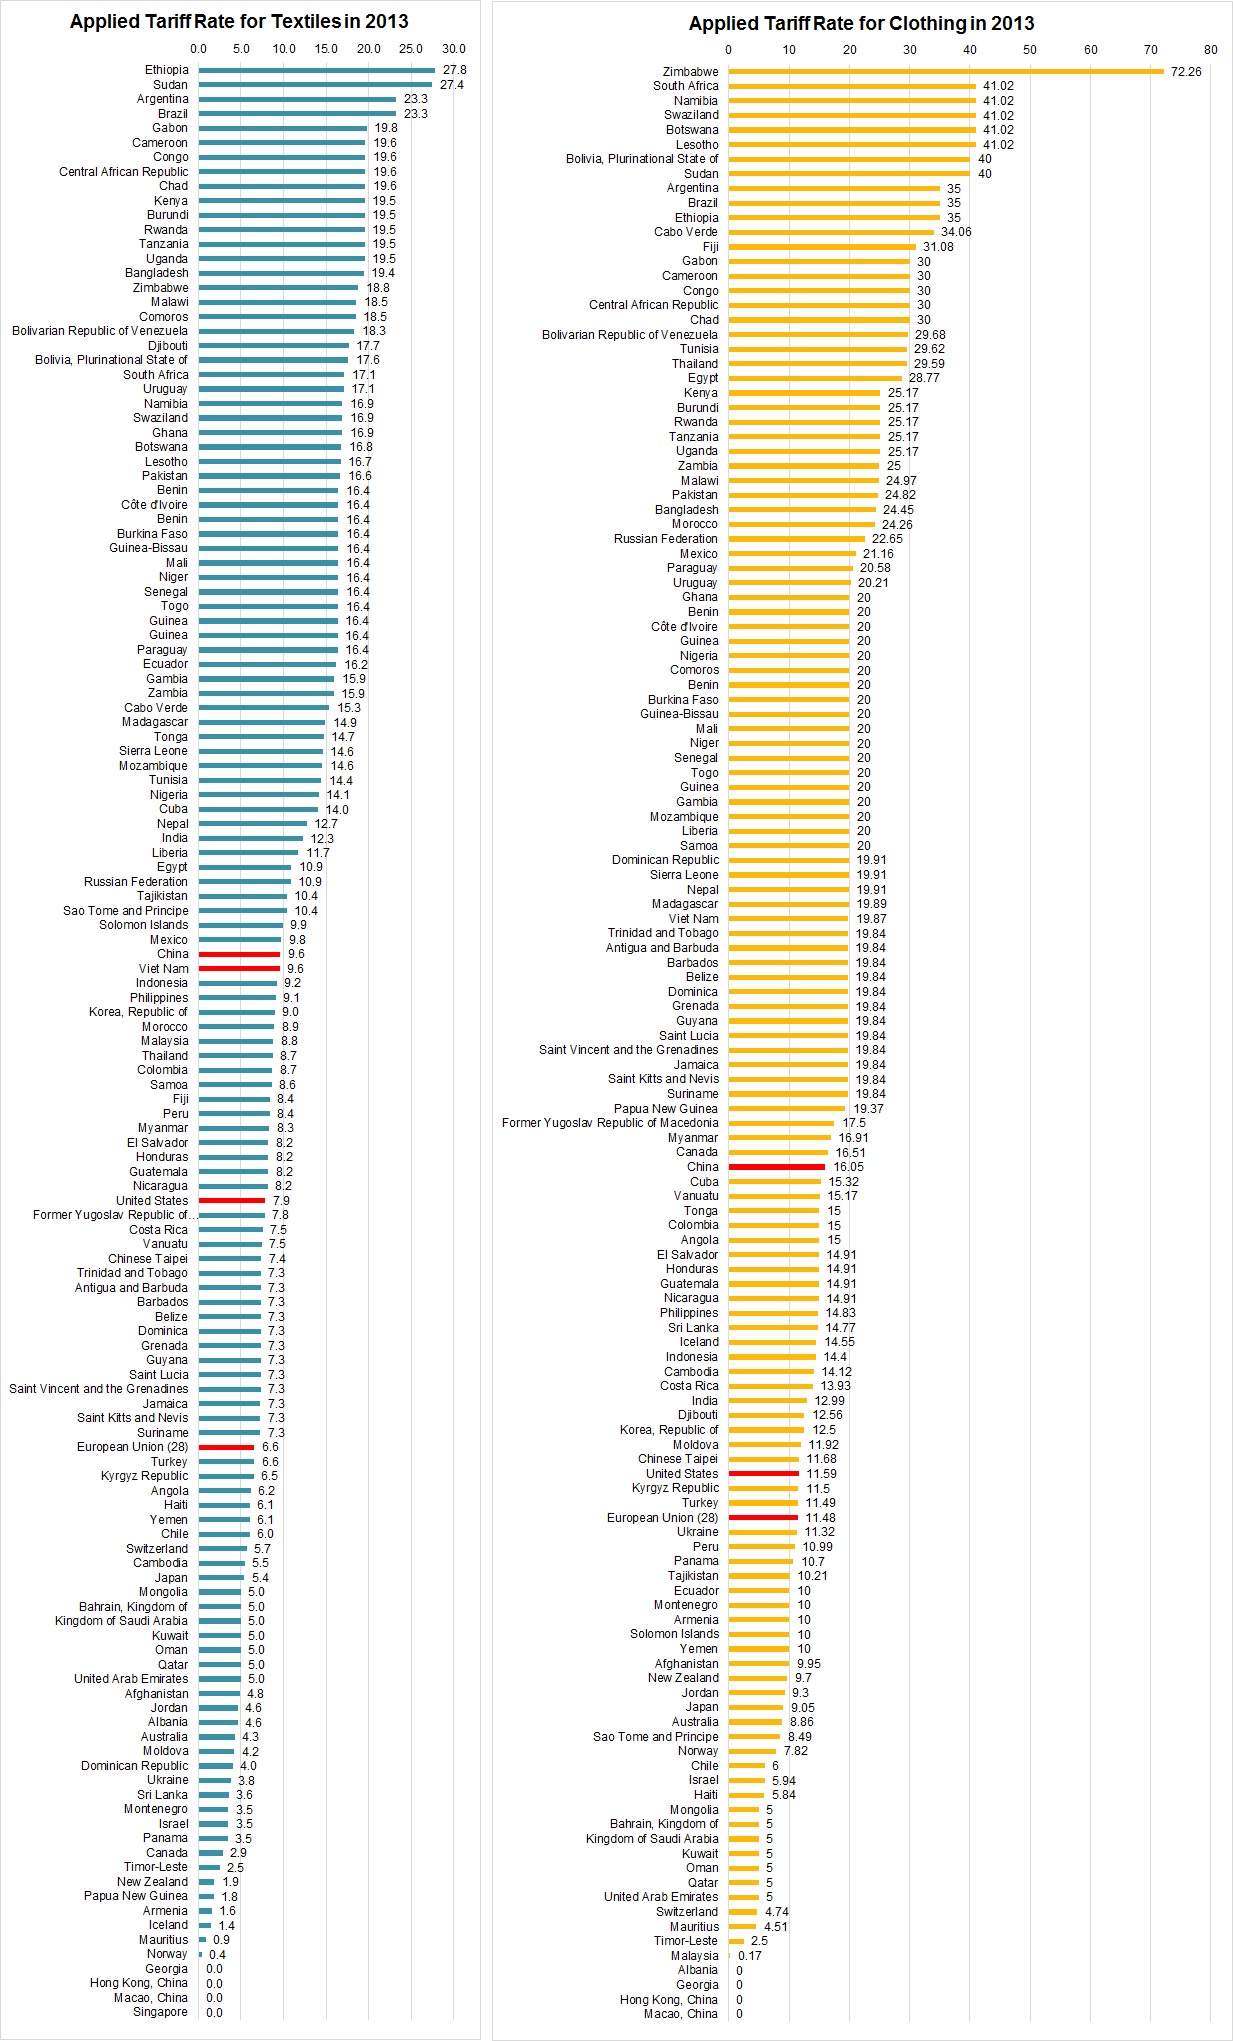
  1. In 2013, average applied tariff rate remained at 10.73% for textiles and 18.25% for apparel worldwide. Compared with the average tariff rate for all sectors, the rate for textiles on average is 1.4 percentage points higher and the rate for apparel is 8.9 percentage points higher. This implies that although tariff may not be a critical trade barrier for some sectors anymore, it still significantly matters for the textile and apparel sector.
  2. Least developed countries (LDC) overall set a higher tariff rate for textiles and apparel than the world average level. Ironically, many LDCs heavily rely on imports for textile supply. Should these LDCs lower their tariff rate for textiles, it may help apparel manufacturers there save sourcing cost for yarns and fabrics and improve the price competitiveness of finished apparel products.
  3. At the country level, countries with the highest tariff rate for textiles include Ethiopia (27.8%), Sudan (27.4%), Argentina (23.3%, Brazil (23.3%), Gabon (19.8%), Cameroon (19.6%), Chad (19.6%) and Congo (19.6%). And countries with the highest tariff rate for apparel include Zimbabwe (72.26%), South Africa (41.02%), Namibia (41.02%), Swaziland (41.02%), Botswana (41.02%), Lesotho (41.02%), Bolivia (40.0%), Sudan (40.0%), Argentina (35.0%), Ethiopia (35.0%) and Brazil (35.0%). Interesting enough, many of these countries are members of the African Growth and Opportunity Act (AGOA) which are eligible for the third country fabric provision.

Sheng Lu

USTR Michael Froman Comments on the Textile and Apparel Chapter under TPP

Trans-Pacific-Partnership-1

In an event hosted by the Council on Foreign Relations on October 15, 2015, U.S. Trade Reprehensive Michael Froman left a comment on the textile and apparel chapter (T&A) under TPP. He said that:”

“You know, we worked very hard to find solutions that could address the broad range of stakeholder interests here, even when we had conflicting interests here in the U.S. I’ll take textile as an example. You know, we have a domestic textiles industry that’s been investing in more production in the U.S., growing their employment in the U.S. And obviously we have a strong sector of our economy that brings in apparel from other countries, apparel importers and retailers. We worked very closely with both groups of stakeholders to come up with a solution, to come up with an outcome that we think both will be comfortable with and both will be supportive of. And that’s been very important to us to try and address the broad range of U.S. stakeholder interests, whether it’s labor, environment, importers, exporters, to make sure we’re covering everybody’s interests well.”

In the remarks, Forman also ruled out the possibility that TPP would be renegotiated. He said that:

“So this isn’t one of those agreements where, you know, you can, you know, reopen an issue or renegotiate a provision. This is one where, you know, every issue is tied to every other issue and every country’s outcome is balanced against every other country’s outcome. And so that’s the agreement that we’ll be putting forward under TPA for a vote by Congress.”

According to Inside U.S. Trade (October 9, 2015), the final TPP reflects some of the key priorities of the U.S. textile industry by allowing limited exceptions from the prevailing yarn-forward rules of origin and by including tariff phaseouts for “sensitive apparel items” of 10 to 12 years.

Besides the basket of goods that will become duty-free upon entry into force (which include cotton shirts and cotton sweaters), TPP sets up three other categories for tariff reductions on apparel:

TPP apparel

Major exceptions other than the “short supply list” mechanism under TPP include:

  • An “earned import allowance“ program for cotton pants made in Vietnam from third-country fabric by importing a specified amount of U.S. cotton pants fabric. This would allow cotton pants from Vietnam would enter the U.S. duty-free as soon as the agreement is implemented. It is said the ratio for the program is “close” to 1:1. However, for men’s cotton pants, there could be a 15 million square meter equivalents (SMEs) annual cap until year 10, after which it will increase to 20 million. There is no quantitative limit for the other types of cotton pants that can be shipped under the program, such as women’s, girls’ and boys’ pants.
  • A limited list of cut-and-sew items that Vietnam and other TPP countries can ship to the U.S. under the preferential TPP duty rate. These include synthetic baby clothes, travel goods including handbags, and bras.

When Will TPP Take Effect? Let’s look at the History

Untitled

With the conclusion of the Trans-Pacific Partnership (TPP) negation on Oct 5, people now wonder: when will the agreement eventually take effect?

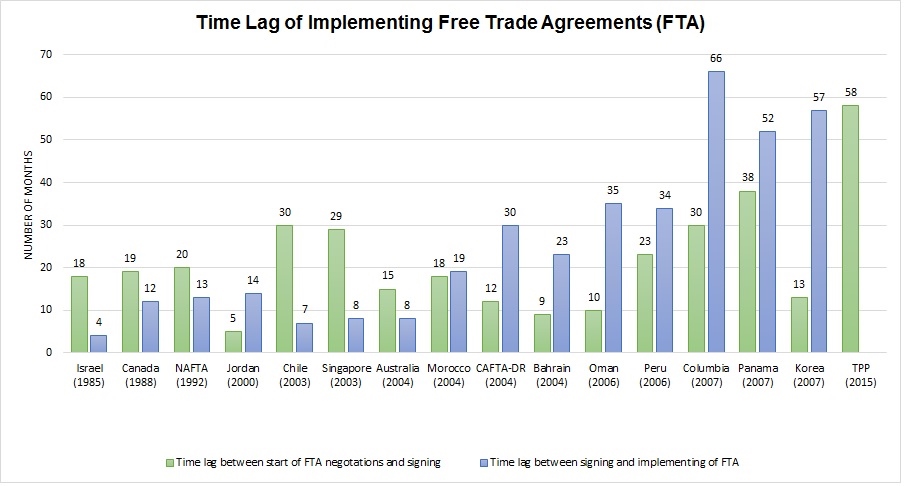
As shown in the chart above, since the 1985 US-Israel Free Trade Agreement, the average time lag between signing and implementing a free trade agreement (FTA) in the United States is 25.5 months (over 2 years). However, since 2006 the average time lag increased to 48.8 months (around 4 years).

So looks like it will take a while…

USTR Adjusts Language of TPP Negotiation Objectives for Textile and Apparel

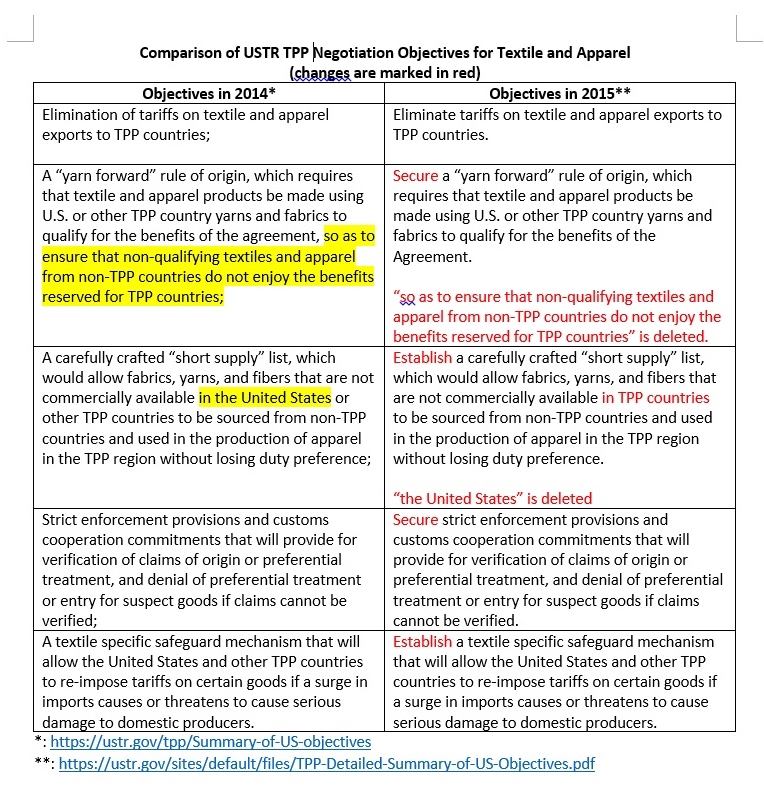
On September 22, the U.S. Trade Representative Office (USTR) releases a detailed summary of its latest TPP negotiation objectives. Specifically for the textile and apparel chapter, compared with the negotiation objectives released in 2014, some wording changes are made this time:

UntitledDoes the change imply that the U.S. side has agreed to allow more exceptions to the “yarn-forward” rules of origin in TPP, but in the format other than “short supply list”? For example, will it be “earned import allowance” or tariff preference level (TPL)?

On the other hand, does the change imply that the “short supply list” under TPP will be stricter than previously expected? (in the 2014 version of the negotiation objectives, it read like the “short supply list” may include those products that are not commercially available in the US but are commercially available in other TPP members. However, in the 2015 version, only those products that are absolutely not commercially available in the whole TPP region are eligible for the “short supply list”.)

Sheng Lu

Does AGOA’s “third country fabric” provision discourage the development of Africa’s local textile industry?

African-textilesThe following Q&A is adapted from the 2015 AGOA Forum Preview (15m:44s)

Question: What is the principal obstacle to the development of a local yarn industry in an apparel exporting country such as Kenya? Does AGOA’s “third country fabric” provision in place for 13 years act as a disincentive to such a development?

Florizelle Liser, Assistant US Trade Representative for Africa: That’s a really good question, but the answer is no. What we know is that African producers of apparel, like producers of apparel all around the world, need to have the flexibility to source their input from wherever of those can be produced most effectively, cost effectively for the products that they are sewing. So we want through the “third country fabric” provision to give the African producers of apparel that flexibility. We do know in terms of establishing textiles business on the ground producing those inputs right there in Africa and that more of that indeed is going to happen. The reason is that as U.S. buyers of apparel and this is an enormous market for apparel… as U.S. buyers of apparel source more of their apparel from Africa, then investors in textile mills, which are very expensive, will be incentivized and are being incentivized to actually establish those fabric mills right there in Africa, and then be able to save time, in terms of getting those inputs that are needed for the clothing that is being produced. So we see that happening already: it’s happening in Kenya, it’s happening in Ethiopia and around the continent. And that is what we need to have more of as we go forward in this ten-year extension of AGOA.

What do you think?

Impact of TPP on U.S. Textile and Apparel Manufacturing: A Preliminary Estimation

Potential impact of the Trans-Pacific Partnership (TPP) remains a hot topic among the U.S. textile and apparel industry. A recent news report suggests that implementation of the agreement will negatively affect clothing manufacturers in LA, where most remaining U.S. apparel manufacturing capacity is located.

According to the news report, “small, independent apparel manufacturers (in LA) did not see big gains from TPP because they did not want to outsource their work, but it put them at a competitive disadvantage.” One local industry estimation quoted in the report claims that “Southern California’s apparel manufacturing will shrink an additional 20 percent if the TPP goes into effect.”

The report further says that “A key question for the apparel industry is whether the agreement includes a yarn-forward provision, which requires material to come from a TPP country in order to be duty-free.” However, the report does not explain why the “yarn-forward” rule could potentially benefit apparel manufacturing in the United States.

The followings are my personal preliminary estimation* of the potential impact of TPP on U.S. T&A manufacturing. Results show that, compared to the base year level in 2011:

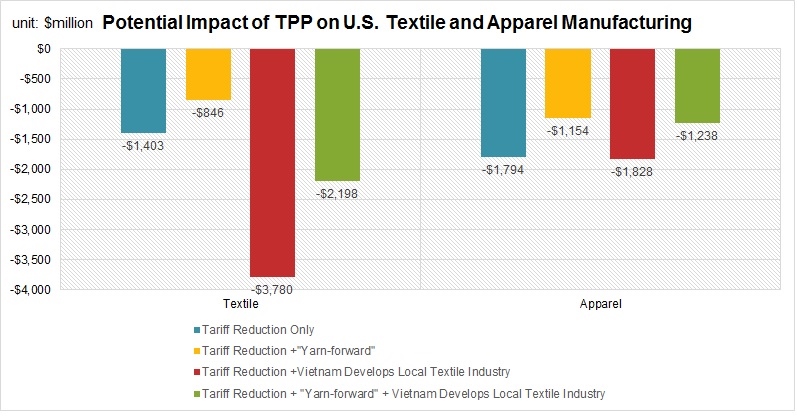
  1. TPP overall will have a negative impact on U.S. domestic textile and apparel manufacturing. In all simulated scenarios, the annual manufacturing output in the United States will decline by $846 million–$3,780 million for textile and $1,154 million–$1,828 million for apparel than otherwise.
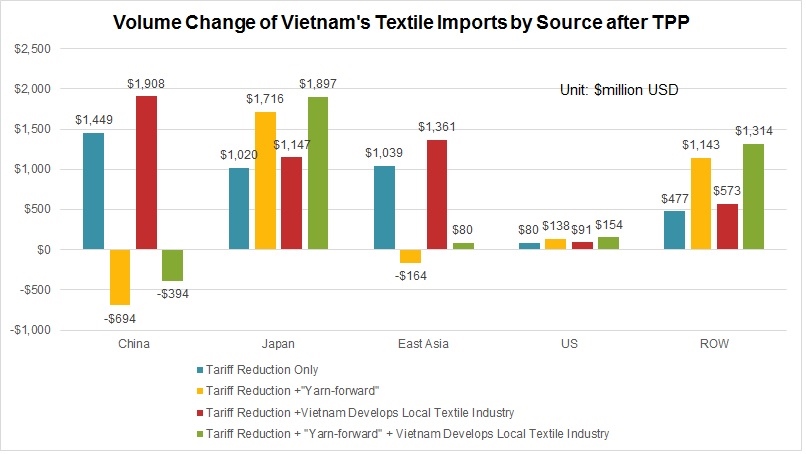
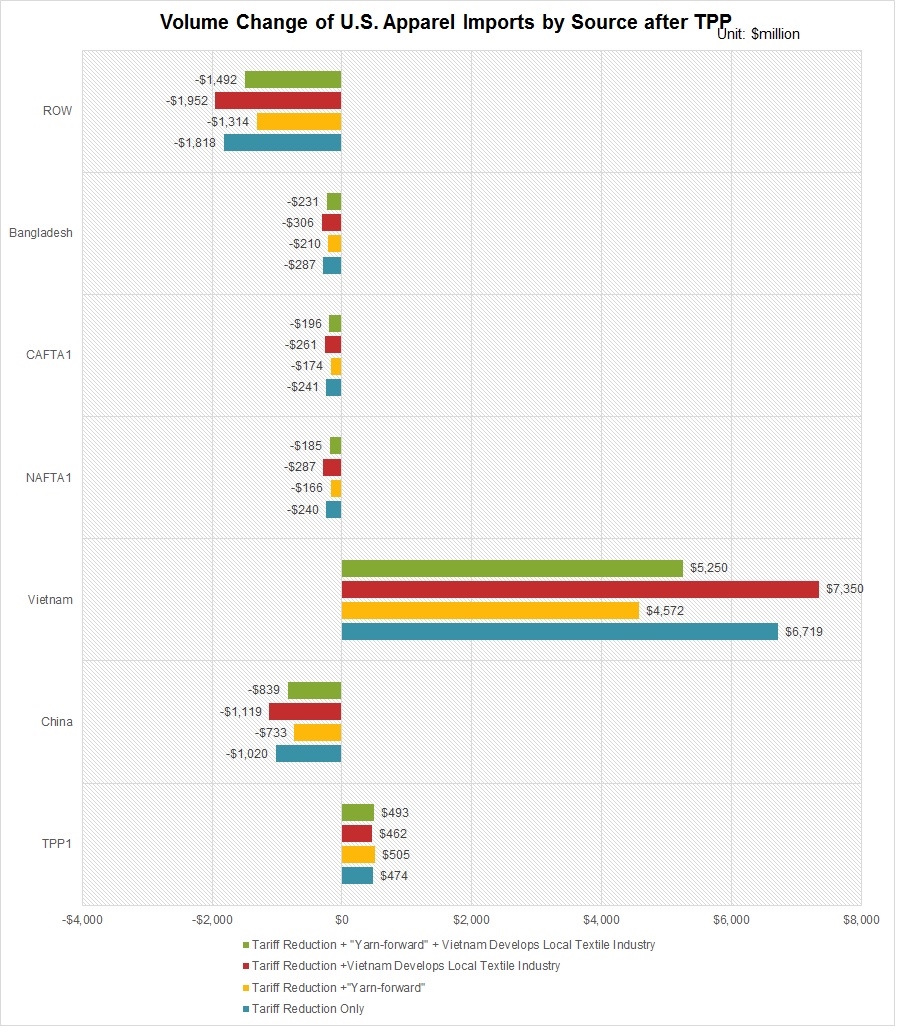
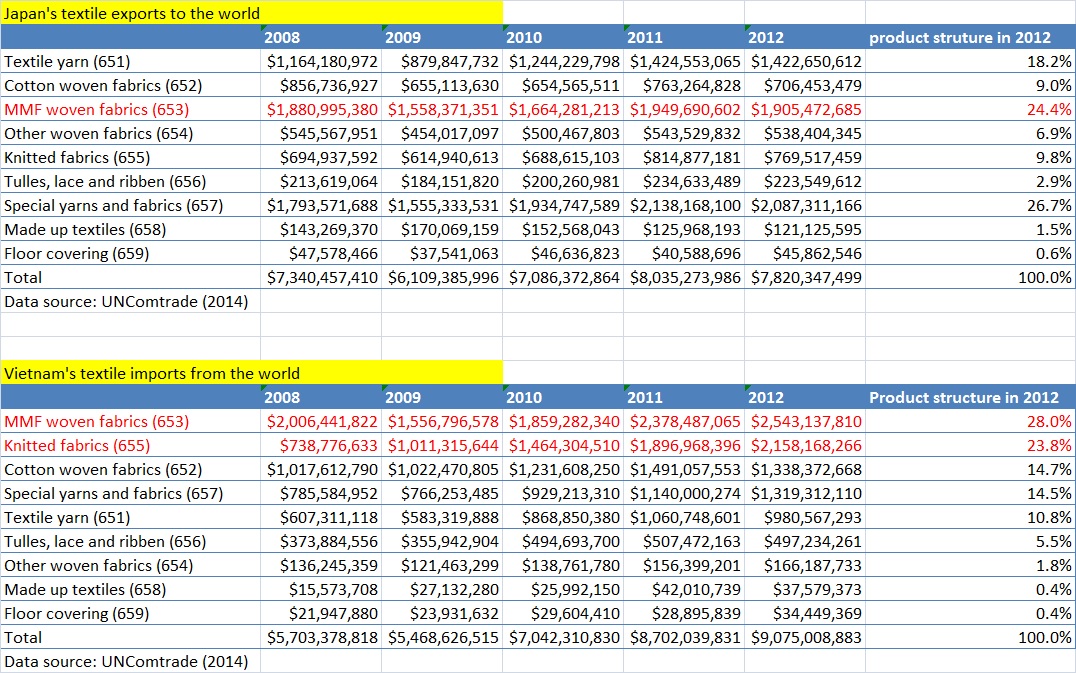
  2. The “yarn-forward” rule may not substantially benefit U.S. domestic textile and apparel manufacturing as some people had suggested, for two reasons: 1) results show that Vietnam is more likely to use Japanese textiles than U.S. textiles when yarn-forward rule is in place. 2) U.S. apparel imports from Vietnam directly compete with those imported from NAFTA and CAFTA regions, the largest export market for U.S.-made yarns and fabrics. When NAFTA and CAFTA’s market share in the U.S. apparel import market is taken away by Vietnam, U.S. textile exports to NAFTA and CAFTA will decline anyway, regardless of whether Vietnam uses U.S.-made textiles.
  3. Results suggest that compared with the “yarn-forward” rule, development of Vietnam’s local textile industry will have an even larger impact on the future of U.S. domestic textile and apparel manufacturing. Particularly, when Vietnam becomes more capable of making textile inputs by its own,  not only Vietnam’s overall demand for imported textiles will decline, but also Vietnam’s apparel exports will become even more price-competitive in the U.S. as well as the world marketplace.

 US T&A manfuacturing

US Textile exports

vietnam import source

vietnam import source

US apparel import source

*Note:1. The estimation is conducted based on the latest Global Trade Analysis Project (GTAP) 9.0 database which includes complete bilateral trade information, transport and protection linkages of 140 countries and 57 sectors. Four scenarios are estimated:

  • Scenario 1 (Tariff reduction only): assumes tariff rate for textile and apparel traded between the twelve TPP members are eliminated, whereas tariff rate for other textile and apparel trade flows remain unchanged.
  • Scenario 2 (Tariff reduction + yarn forward): assumes that in addition to tariff reduction among TPP members for T&A, Vietnam substantially increases tariff rate by 100 percent for textile imports from its leading suppliers that are non-TPP members (i.e. China, South Korea and Taiwan). This policy shock provides strong financial incentives for Vietnam to import less textile from non-TPP suppliers and instead import more from other TPP members—an equivalent effect as the yarn forward rule.
  • Scenario 3(Tariff reduction + Vietnam develops local textile industry): assumes that in addition to tariff reduction among TPP members for T&A, productivity of Vietnam’s textile industry increases by 10 percent whereas productivity of other sectors remain unchanged.
  • Scenario 4 (Tariff reduction + yarn forward + Vietnam develops local textile industry): this scenario combines all policy shocks mentioned in scenario 1-3, i.e. tariff rate for textile and apparel traded between the twelve TPP members are eliminated, Vietnam substantially increases its tariff rate by 100 percent for textile imports from its leading suppliers that are non-TPP members (i.e. China, South Korea and Taiwan) and productivity of Vietnam’s textile industry increases by 10 percent.

 2. TPP1 includes Australia, New Zealand, Malaysia, Singapore, Burnie, Chile and Peru; NAFTA1 includes Canada and Mexico; CAFTA1 includes all other CAFTA members except the United States.

Sheng Lu

2015 US Fashion Industry Benchmarking Study Released

[Note: The 2016 U.S. Fashion Industry Benchmarking Study has been released]

UntitledThe U.S. Fashion Industry Association (USFIA) released its 2015 benchmarking study today. The report examines the industry’s business environment and outlook, sourcing practices as well as U.S. fashion companies’ viewpoints on critical trade policy agendas. Among the key findings:

  • Overall, respondents remain optimistic about the five-year outlook for the U.S. fashion industry. Like last year, they are most concerned about increasing production or sourcing costs, but they expect increases to be more modest this year.
  • Consistent with our 2014 findings, U.S. fashion companies are NOT moving away from China, and Bangladesh remains a popular sourcing destination with high growth potential, though not quite as high as last year.
  • Companies continue to diversify their sourcing, though free trade agreements (FTAs) and preference programs remain underutilized.
  • The U.S. fashion industry is a critical Trans-Pacific Partnership (TPP) stakeholder, as close to 80 percent of respondents expect implementation will impact their business practices. However, the restrictive rules in the agreement limit the potential.
  • U.S. fashion companies continue to express interest in expanding sourcing in the United States in the next two years as they further diversify their sourcing. However, there is no evidence that companies are shifting their business models back to manufacturing.

This benchmarking study was based on a survey of 30 executives at the leading U.S. fashion companies from March 2015 to April 2015. The findings well reflect the views of the most influential players in the U.S. fashion industry, with 90 percent of respondents having more than 100 employees (including 60 percent with more than 1,000 employees).

The full report can be downloaded from HERE.

Two Years after the Rana Plaza Tragedy: What Has Changed?

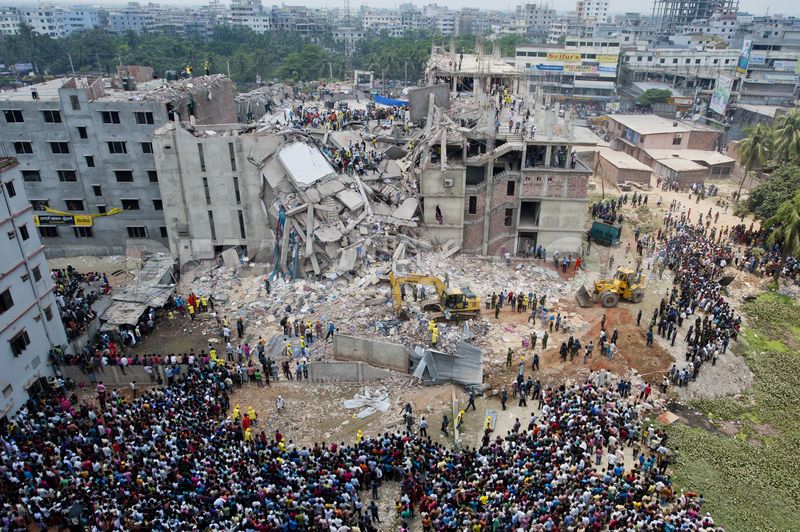
rana plaza

Note: the followings updates are compiled based on the 2015 Bangladesh Development Conference held from June 5th to 6th at the Harvard University. The conference attracted over 100 attendants and speakers from various aspects of the apparel industry, government agencies, international organizations, non-government organizations and academia.

1. Overall, the industry side argues that tremendous efforts have been made to improve work safety in the Bangladesh apparel industry and things are gradually improving. However, representatives from some labor unions say that changes are not happening fast enough as they should.

2. Indeed, as one of the most noticeable changes after the Rana Plaza tragedy, the Bangladesh apparel factories are now facing more frequent safety inspection and audit from various parties:

  • In addition to the regular inspection conducted by individual fashion brand or retailer, the Accord on Fire and Building Safety in Bangladesh (the Accord) and Alliance for Bangladesh Worker Safety (the Alliance) were established in 2013 respectively (mostly funded by western apparel brands sourcing from Bangladesh) to maintain minimum safety standards in the Bangladesh apparel industry.
  • The Accord has a total five-year budget of $50 million to be used on factory safety inspection and improvement. However, it is far from being clear what will happen after the Accord agreement expires in 2018 and whether the inspection achievements can be maintained afterwards.
  • The International Labor Organization and International Finance Corporation launched the “Better Work” program in collaboration with Bangladesh government, apparel factory owners, workers, fashion buyers and other relevant stakeholders. The program intends to provide assessments of factory compliance with national law and core international labor standards, paired with transparent public reporting on findings.
  • Nevertheless, some people argue that audit itself is not the answer to the problem, just like “a pig will not gain weight simply by weighting it; instead, we have to feed it.” Reflecting on the limitation of inspection and audit, they refer to compliance as just a piece of paper whereas ethics is something that keeps people awake in bed.

3. Some foreign governments also have responded to the Rana Plaza tragedy, although in different ways:

  • Stick: the U.S. government decided to suspend Bangladesh’s Generalized System of Preferences (GSP) status in 2013 as a response to the Rana Plaza tragedy. Because textile and apparel are excluded from GSP, this measure has no direct impact on Bangladesh’s apparel exports to the United States. But the movement is symbolic and significantly increases the publicity of corporate social responsibility (CRS) issue in the Bangladesh apparel industry.
  • Carrot: in comparison, the European Union chooses to continue providing Bangladesh its GSP benefits. As a GSP beneficiary, Bangladesh’s apparel exports to EU can enjoy duty free treatment when competing with other Asian suppliers such as China and India. According to EU, from 2008 to 2012 EU28 imports from Bangladesh increased from €5,464 million to €9,212 million (+69%), which is more than half of Bangladesh’s total exports. While granting Bangladesh the benefit, EU also launches the GSP Action Plan and the Sustainability Compact to encourage responsible businesses in Bangladesh.

4. Training has been provided for Bangladesh officials to help them better understand building safety requirements.

5. More apparel factories in Bangladesh now have their own labor unions. According to the local law, 30 percent of the labor force in a factory can form its own labor union, meaning theoretically one factory can have up to three different unions. There has been more open discussions on “worker/women empowerment”, “social dialogue” and “stakeholder engagement” in the Bangladeshi society as well.  

6. Some creative financial incentive mechanisms are suggested to improve the situation, such as offering factories with better compliance record with more attractive interest rate for bank loans; and adding building safety clauses in factory insurance contract.  

7. Academia is actively engaged in finding a solution for improving the CRS practices in the Bangladesh apparel industry as well:

  • Based on analyzing the factory inspection data, some scholars start to evaluate the effectiveness of the current inspection system (eg: does who pay for the inspection matter for the result? Does violation go down overtime in inspection? What is the role of on-going people to people relationship in inspection?).
  • Some projects intend to develop an estimate of the true size of the Bangladesh apparel industry, given the fact that the worst work condition may exist in those undocumented factories. As a matter of fact, even the Bangladesh government doesn’t know how many garment factories they have in the country.
  • Some scholars propose the idea of linking a company’s social compliance data with its business financial data to evaluate the business implication of CRS practices.
  • Some studies compare the labor practices between Bangladesh and other developing countries in South Asia such as Cambodia and Sri Lanka.
  • Some people suggest using case studies to develop hypotheses for a policy change.
  • More and more studies are now conducted based on field trip and interview in Bangladesh.

8. Criminal charges recently are filed against a dozen individuals and companies identified responsible for the Rana Plaza tragedy.

9. Response to the Rana Plaza tragedy has further led to a discussion on the broader economic, social and political reform in Bangladesh.

Sheng Lu

From Trade Protection to Going global: the Changing Nature of the U.S. Textile Industry

MIL-06

Last week, Milliken & Company, one of the largest U.S. textile manufacturers founded in 1865, was featured in a Wall Street Journal article on the changing position of the U.S. textile industry on international trade. As you may remember in our case study, it was Roger Milliken, the chairman of the Milliken & Company, that founded the Crafted with Pride in the U.S.A. campaign in the 1980s. The campaign not only encouraged U.S. consumers to purchase more “Made in USA” products, but also intended to raise the public awareness of “import threat”. However, titled “free trade gains a convert”, the WSJ article argues that Milliken & Company today has “dropped protectionist stance as business went global”.

The article is a great reminder of the changing nature of the U.S. textile industry in the 21st century. One of them is going global. According to the Hoover’s Academics (2015). Milliken & Company today operates about 40 manufacturing plants in the US, Belgium, China, France, and the UK, as well as sales and services offices worldwide. In particular, as mentioned in the WSJ article, China nowadays is seen as Milliken & Company’s future. The company opened an industrial-carpet factory near Shanghai in 2007 and also moved its Asia headquarters from Tokyo to Shanghai in 2012. And rather than using Chinese labor to make goods for export back to the United States, most Milliken & Company’s products made in China target the local market. As estimated by GlobalData, urbanization and an increase in house ownership in developing countries like China, India, Vietnam, Thailand and Indonesia have led to an annual 7.9% growth of carpets and rug sales in the region.

It is also important to recognize that Milliken & Company’s business model is no longer based on manufacturing basic yarn or fabrics used for apparel. Instead, the company mostly produces highly tech-driven and capital intensive industrial textiles as well as chemicals and colorants that offer more than 100 applications including infusing washable markers and liquid laundry detergent, killing bacteria, melting ice, and blocking UV rays. In many industry sources, Milliken & Comopany is even counted as a chemical company that directly competes with industry giants such as DuPont, Dow Chemical and Shaw industries. Overall, it is product and business innovation that drive this hundred-old company moving forward.

Additionally, we shall not misread title of the WSJ article—i.e. the U.S. textile industry 100% supports free trade with no condition. As a matter of fact, the rules regulating global textile and apparel trade are still very complicated and restrictive in nature. For example, the U.S. textile industry still insists strict yarn-forward rules of origin to be adopted in the Trans-Pacific Partnership (TPP) and the Trans-Atlantic Trade and Investment Partnership (T-TIP). However, many U.S. apparel companies and fashion brands see the restrictive yarn-forward rule of origin outdated and incompatible with the 21st century global apparel supply chain.

No matter how, it is a noticeable change that the U.S. textile companies like Milliken start to shift their position on international trade, even just in a subtle way. Globalization has demonstrated its impact on shaping the new landscape of the U.S. textile industry and will continue to do so in the years to come.

TPP Textile Negotiation Updates (March 2015)

trans-pacific-trade-agreement_issuebanner

According to Inside US Trade, negotiators continued their work on the technical details of the textile chapter under the Trans-Pacific Partnership (TPP) during the latest round of negotiation in Hawaii. Although progress has been achieved, key issues remain unsolved.   Exceptions to Yarn-Forward Rule of Origin Since the 807A program under the Caribbean Basin Imitative (CBI) enacted in 1998, the so called “yarn-forward” rule of origin has been adopted in almost all free trade agreement (FTA) and trade preference program (TPA) reached between the United States and its trading partners. “Yarn forward” rule requires that each step of apparel production from spinning of the yarn must take place in one of the FTA countries. At the same time, FTA/TPA often adopt exceptions in addition to “yarn-forward” rule so as to provide flexibility to importers, especially in the case when certain textile and apparel products are not available in commercial quantities from the FTA/TPA region. It is almost certain at this point that TPP will continue to adopt the “yarn forward” rules of origin. However, what kind of exceptions to the yarn forward rule will be allowed in TPP remain unclear: 1) How long will be the “short supply” list in TPP? Short supply list is a mechanism which allows fibers, yarns, and fabrics determined not to be available in commercial quantities in a timely manner from within the FTA partner countries to be sourced from outside the countries for use in qualifying textile and apparel products. According to Inside US Trade, some TPP countries want to declare the short-supply list complete as soon as possible so that they can shift the discussion to other possible exceptions to the yarn-forward rule. However, others doubt that the U.S. would be willing to contemplate additional exceptions and therefore believe that the best approach is to keep the short-supply list open and try to add as many products as possible. 2) Whether there will be other exception mechanisms in TPP in addition to the “short supply” list? According to Inside US Trade, there were some discussions on creating a separate mechanism such as the tariff-preference levels (TPL) in TPP. TPL allows for a certain quantity of textile and apparel goods (usually yarns, fabrics and cut pieces) from a third-country (a country who is not a party to the agreement) to qualify for the FTA benefits. Additionally, it is more than just Vietnam that is seeking more exceptions to the “yarn forward” rule in TPP. For example, Australia and New Zealand are also doing so, which may be in large part for tactical reasons — essentially holding up the textile talks as leverage to secure acceptable outcomes in other areas that are more important to them, for instance, agricultural market access or intellectual property. Tariff Phrase-out Mechanism Inside US Trade says that U.S. is sticking to the framework that it laid out in its initial tariff offer, which put products into three categories subject to different phrase-out schedule:

  • X-basket, which covers the most sensitive products that would be subject to an initial cut upon entry into force, but then remain in place until they are eliminated in the tenth year for knit apparel and fifteenth year for woven apparel
  • B-basket, which consists of slightly more sensitive apparel items that would be subject to a linear tariff phase-out over five years
  • A-basket, which consists of least sensitive items whose tariff rate would go to zero immediately upon TPP entries into force

Key questions remain as to which items the United States will place into what basket. Other issues in the textile chapter The TPP textile chapter may also include languages on the following two issues: 1) a special safeguard mechanism under which the importing country can raise tariffs up to the most-favored nation (MFN) level in the case of an import surge; 2) customs language on the inspection mechanism.

Mexican New Import Rules on Textiles and Apparel Raise Concerns

mexicanclothes

In January 2015, Mexico announced a set of new measures aimed at combating “unfair” trade practices in T&A imports and enhancing the competitiveness of domestic T&A sector in the face of increasing foreign competition.

The proposed measures will particularly target those imports considered to be “undervalued” by the Mexican government. According to Inside US Trade and Sourcing Journal Online, one of these measures is to establish a minimum reference price for imported T&A products. If shipments enter at below that price, they would be subject to an investigation by the Mexican government that could lead to the imposition of additional duties and taxes. To be noted, the proposed new measures will be taken separately from traditional trade remedy measures such as anti-dumping, countervailing duty and safeguard.

Other proposed measures intend to strengthen custom enforcement, including:

  • Mexico will required a mandatory registry for T&A imports. A similar registry system has been required for footwear;
  • Mexico will postpone the import duty reduction that was expected to be implemented at the beginning of 2016 on 73 apparel items and seven textile made-ups. Originally slated to enter into force on January. 1, 2013, the duty reduction from 25 percent to 20 percent has been twice postponed for one-year periods and will now be delayed until 2018;
  • Importers will be required to provide advance notice of shipments to the Mexican Economy Secretariat in the future;
  • Mexico will break down the current eight-digit tariff lines for textile and apparel products into 10 digits, which an industry source said would allow tariff rates to be more specific in light of the fact that apparel products have evolved to be more specialized;

Moreover, Mexico will implement a new financing mechanism with total available credit of 450 million pesos (around $30 million USD) over the next 12 months to help the domestic T&A industry (especially small- and medium-sized enterprises) upgrade their machinery and equipment, pursue innovative strategies and develop new products. The Mexican Service Agency for the Commercialization and Development of Agricultural Markets (Aserca) will further support the purchase of cotton from domestic growers by textile manufacturers.

According to WWD, the US T&A industry has three major concerns about Mexican’s proposed measures: one is the potential delay in custom clearance and more complicated documentation requirements; second is the additional tariff rate and increased cost of exporting from the United States or anywhere else in the world to Mexico; third is the lack of policy transparency adding to the potent business risks.

Industry Background

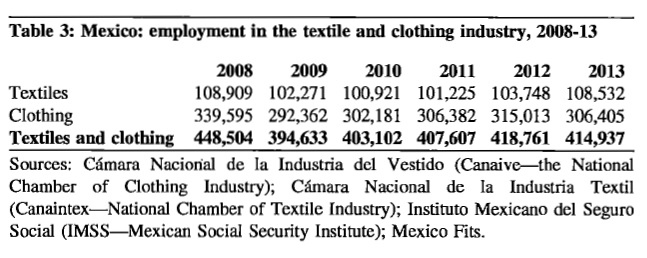
T&A industry accounted for 3.7 percent of Mexico’s GDP in 2013 (1.3 percent for textiles and 2.5 percent for apparel). About 415,000 workers directly employed in the sector in 2013, among which 74 percent worked for the apparel sector.

1

One important feature of Mexico’s T&A industry is the so called “Maquiladora” operation: simple sewing of garments made from imported fabrics and using cheap labor. The “Maquiladora” operation is largely coordinated by US-based apparel brands and retailers. Most of “Maquiladora” factories are located in the free trade zones, in which equipment and imported materials (such as fabrics) can be duty-free. Output of “Maquiladora” are exported, mostly to the United States.

3

Mexico imported $8.6 billion T&A in 2013, among which $2.4 billion were fabrics, followed by made-up textiles ($0.55 billion) and yarns ($0.39 billion). This pattern reveals Mexico’s heavy reliance on imported textiles due to limited domestic textile manufacturing capacity.

At the same time, Mexico’s apparel imports increased from $2.4 billion in 2008 to $2.9 billion in 2013. Particularly, Mexico’s apparel imports from China surged by 558.8 percent between 2008 and 2013. In 2013 alone, apparel imports from China went up by 42.1% to $0.97 billion. It is said that China is the main target of Mexico’s proposed new import measures.

4

 [Comment for the post is closed]

Textile and Apparel in the 2015 US Trade Policy Agenda

Untitled

Two hearings were held on January 27 where US Trade Representative Michael Froman testified before the Senate Finance Committee and the House Ways & Means Committee on the 2015 US Trade Policy Agenda. During the Senate hearing, two questions were directly related to the textile and apparel (T&A) industry:

Senator Robert Menendez (D-NJ) expressed concerns that inclusion of several concessions requested by Vietnam regarding rule of origin and short supply list for T&A in the Trans-Pacific Partnership (TPP) will result in severe job losses and potentially hurt the T&A industry in the Western Hemisphere. In response, Froman said that:

“We worked in the textile area through the yarn forward rule, the short supply list, rules of origin and customer enforcement and corporation to take these things into consideration. We’ve worked very closely with textile manufacturers in the US who are part of this supply chain with Central America to get the best of our understanding of what are the sensitivities are and take that into account in our negotiations.”

John Isakson (R-GA) raised the question about China’s recent cotton reserve & subsidy policy and its negative impact on the world cotton price which “has declined from 83-85 cents/pound not a long ago to 55-57 cents/pound recently.” Isakson wondered if anything USTR would do to address the problem, such as bringing the case to the World Trade Organization (WTO) Dispute Settlement Body (DSB). In response, Froman said that:

“The whole pattern of agriculture subsidies has changed a lot over the last ten to fifteen years. When (WTO) Doha Round was first started, focus on the subsidy was really the United States and the European Union. But in both of those areas subsidies have come down, while subsidies from China and India in the agriculture area have been increased. By some measures, China is now the largest subsidizer of cotton. We are engaging with them. We have conversations in the last couple of days also about that, about taking a fresh look at where subsidies have been provided, how it distorted the market and how that should play into the global trading negotiations. It is important to update our views on where the subsidies come from and what impact it has. For poor farmers in Africa, it doesn’t matter whether the subsidies come from the US or from China. It matters that the subsidy exists and so we will be engaged with China on this and create some disciplines around us. We are looking at all options out there. We are not yet determined whether there will be a (WTO DSB) case brought in that area.”

Other hot topics covered by the hearing include passing Trade Promotion Authority (TPA) bill, creating jobs through trade, addressing agriculture, digital trade & data flow, State owned enterprises (SOE), currency manipulation, transparency and Intellectual property right (IPR) protection issues in TPP, strengthening trade enforcement, renewing African Growth and Opportunity Act (AGOA), and making further progress of Trade in Service Agreement (TiSA) and Information Technology Agreement (ITA) at WTO.

The followings are some personal comments on the overall atmosphere in the Senate hearing:

  • It doesn’t seem possible to be able to conclude TPP without TPA, for at least two reasons: 1) Congress doesn’t want to give up its authority on trade policy. If TPP negotiation were concluded before the passage of TPA, Congress would feel it had little influence on shaping TPP through the mechanism of TPA trade negotiating objectives. This will add to the difficulty of potentially passing the TPP implementing bill under expedited legislative procedures. 2) Other TPP members, such as Japan, are unlikely to put the final offer on the negotiation table, especially for politically sensitive issues, without having the assurance provided by TPA.
  • There is a growing call for “strong” labor and environmental provisions in TPP. This is not surprising given the fact that the general public is attaching greater importance to labor and environmental impact of international trade. NGOs, such as labor and environmental groups have become more critical players in trade politics nowadays as well. Practically, strong labor and environmental provisions are regarded as important means to create “a level playing field” for US products competing in the world marketplace. These provisions can also be used as leverages to push for better human right practices in some foreign countries. That being said, as noted by many trade experts, trade policy shall not be expected to solve environmental and labor problems.
  • Currency manipulation becomes a hot discussion topic again, but USTR doesn’t seem to be interested in including the currency provision in TPP. Many senators raised the currency issue during the hearing, however, it shall be noted that: 1) Free trade agreement (FTA) and even WTO is not an appropriate venue to deal with currency issues; 2) the business community actually does not see currency as a priority issue to address. They care more about things like market access, IPR protection, national treatment and dealing with SOEs. 3) Currency manipulation provision is not an effective way to solve currency concerns. For example, it would be impossible to determine what shall be the “right” exchange rate–ten economists may give twelve different answers. 4) It will be interesting to see what language the potential TPA bill will use to define currency issue as a  trade negotiating objective.
  • Benefit of trade is still largely misunderstood. During the hearing, almost all support for TPA & TPP came from the export side: “export is good for the US economy”, “export can create higher-paid middle class jobs”, “US runs trade surplus with all FTA partners and all trade deficits came from those non-FTA partners”…However, nobody in the hearing talked about the benefits of imports and the global nature of supply chain in the 21st Mercantilism is still a popular view in Congress.

Sheng Lu

Tariff or Not

B711fJvCcAAELet

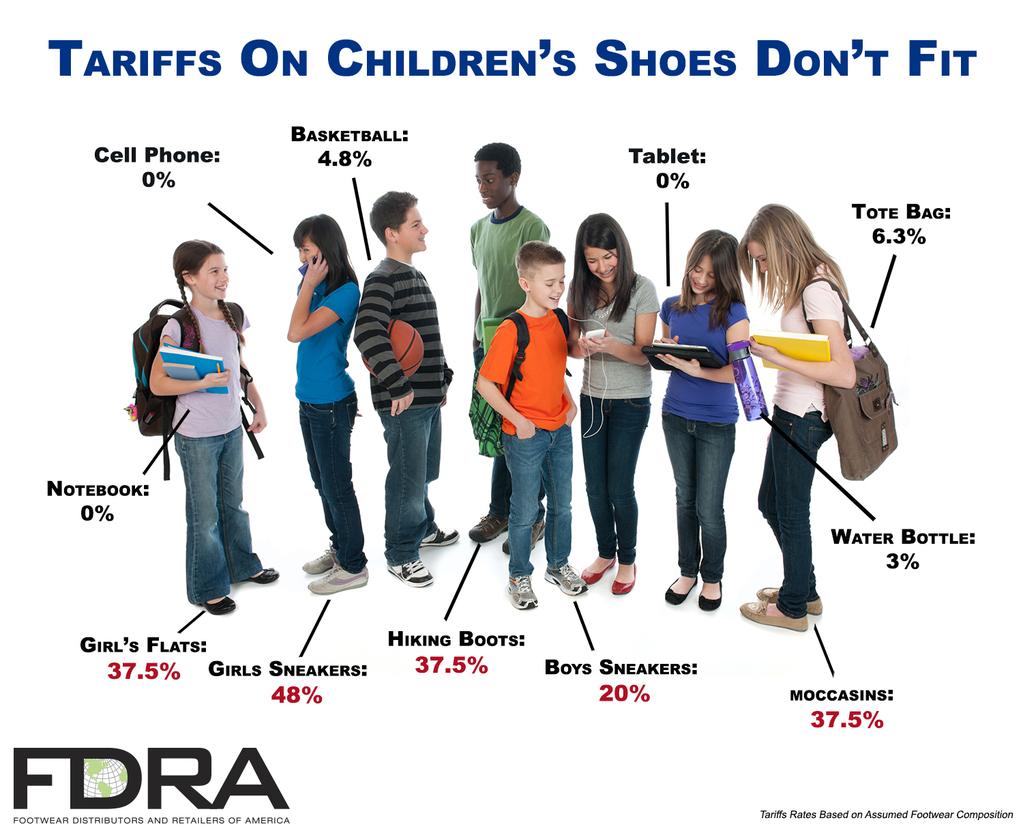
Tariff is a tax levied on imports only. Tariff will make imports more expensive in the market. For example, if the original price of a “Made in China” T-shirt is $5, with a 20% tariff, it becomes $5*(1+20%)=$6 when sold in the U.S. market.

Tariff has multiple impacts. On one hand, tariff may protect the domestic industry from foreign competition and help government of the importing country gain some tax revenues. On the other hand, consumers will have to pay more (or consume less) because of increased market price as result of tariff. Tariff also hurts exporters and those sectors operating on a global basis. For example, a high tariff rate on imported fabrics may raise the production cost of a clothing manufacturer which sells its finished products to the world market. According to the World Trade Organization, nearly 60 percent of world trade today are inputs and components. 

Questions for discussion:

  • How to explain the phenomenon that tariff rates are so different across different types of product in the picture? Should they be so different?
  • Should tariffs on flats, sneakers, boots and moccasins be lowered or eliminated in the U.S. or even world wide? What issues need to be considered?

US Department of Labor: 28 countries were Found Using Child or Forced Labor in Making Textiles and Apparel

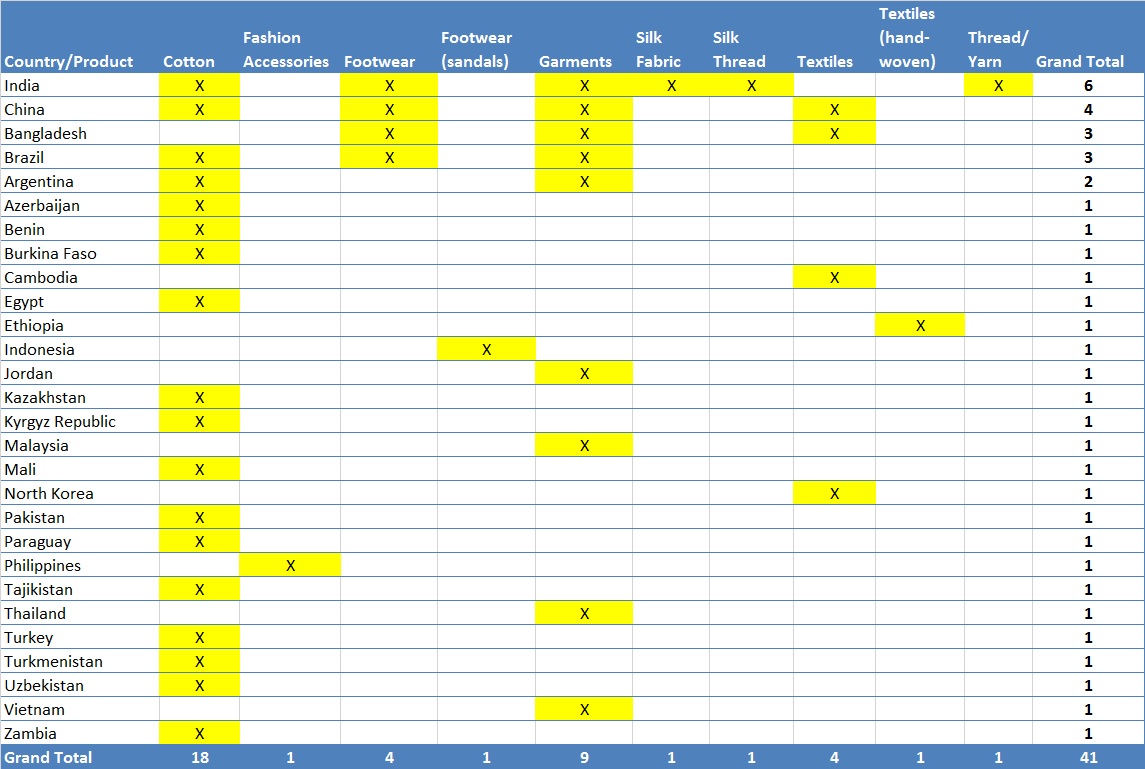
In its updated List of Goods Produced by Child Labor or Forced Labor (ILAB) released on December 1, 2014, the U.S. Department Labor said that at least 28 countries are found using child or forced labor in making textiles and apparel. All countries on the list appear to be developing countries. Particularly, the problem of using child labor or forced labor was found most serious in the cotton sector (18 countries), followed by garment manufacturing (9 countries).

Bangladesh, a focus of corporate social responsibilities practices these days, was found using child labor in making garment according to ILAB.

1

2(Data compiled by Sheng Lu)

Note: * ILAB maintains a list of goods and their source countries which it has reason to believe are produced by child labor or forced labor in violation of international standards. The List is intended to raise public awareness about child labor and forced labor around the world, and to promote and inform efforts to address them. A starting point for action, the List creates opportunities for ILAB to engage and assist foreign governments. It is also a valuable resource for researchers, advocacy organizations and companies wishing to carry out risk assessments and engage in due diligence on labor rights in their supply chains

Follow up:

After the release of the ILAB report, four House Democrats sent a letter to USTR Michael Forman on December 4th, 2014, asking him to provide details on labor provisions in the TPP. As noted by the lawmakers in the letter: “Vietnam, Mexico, Peru, and Malaysia, one-third of the nations included in the TPP, were all cited for labor abuses in the report…”. “We are following up with you because we believe it is important that you take action to ensure that real, meaningfully enforceable labor protections are in the TPP”.

Think Big about International Trade

cropped-chess-globe-32

I hope you all enjoy the guest lecture given by Ambassador Friedrich Löhr on his global travel stories as a career diplomat over the past 37 years. Actually, topic of our class is closely connected with “international relations”. As observed by Michael Forman, US Trade Representative, “trade is what most of international relations are about and trade policy is national security policy”; “leaders have come to see the economic clout that trade produces as more than merely a purse for military prowess; they now understand prosperity to be a principal means by which countries measure and exercise power”.

Several readings/case studies/discussions in our class have touched the strategic aspects of international trade in the 21st century. For example, I hope at this point you not only understand the technical aspects of the Trans-Pacific Partnership (TPP) such as “yarn-forward” and “short supply list”, but also can see TPP as a strategic movement for the US to become more deeply embedded in the Asia-Pacific region. Similarly, the Trans-Atlantic Trade and Investment Partnership (T-TIP) is a free trade agreement, but a successful conclusion of T-TIP will also send “an unmistakable signal to the world about the strength of the US-EU bond—a timely reminder as the crisis in Ukraine has triggered deep unease across the continent.”

The strategic aspects of international trade can also be understood from the development perspective. There is a direct correlation between integration into the multilateral trading system and economic growth and between growth and poverty reduction. What then UN Secretary Kofi Annan said remains very true “The main losers in today’s very unequal world are not those who are too much exposed to globalization. They are those who have been left out”. No example can be more convincing than the case of textile and apparel (T&A) to illustrate this point. In many low-income countries in the world, T&A accounts for two-thirds of local employment and over 60 percentage of total merchandise exports. This is why trade preference programs such as AGOA, GSP and HOPE play a critical roles in providing greater market access opportunities to those most vulnerable countries.

To understand the strategic aspects of trade, you may further recall our case study 2 and the discussions on the necessity of maintaining a sound operation of the GATT system in the setting of 1970s. Without a rule-based multilateral trading system, international trade simply couldn’t happen. Yet the current multilateral trading system established shortly after World War II needs an update to better reflect the changing nature of world economy and format of trade. This is why so much attention has been given to mega-trade agreements such as TPP and TTIP. These free trade agreements will have a huge impact shaping the future rules of the game, no matter in terms of adding new agendas such as state-owned enterprises, digital trade and facilitating supply chain, or more effectively establishing a level playing field for issues such as environmental and labor standards.

So think strategically about international trade and think big about the impact of our T&A industry in the 21st century global economy.

US Fashion and Apparel Industry Releases Position Paper on the Transatlantic Trade and Investment Partnership (T-TIP)

p0111400002h

The American Apparel and Footwear Association (AAFA) and the US Fashion Industry Association (USFIA) , the two leading industry organizations representing the US fashion and apparel industry, jointly released a position paper this week on the Transatlantic Trade and Investment Partnership (T-TIP), which is currently under negotiation between the United States and the European Union.

The position paper spells out a few priorities deemed by the US fashion apparel industry for the T-TIP:

  • Full, immediate and reciprocal elimination of tariffs, meaning import duties on all apparel products shall be eliminated on day one without phrase-out periods.
  • Flexible rules of origin, meaning restrictive rules of origin such as “yarn-forward” which requires companies to use textile inputs from certain regions so as to enjoy the duty free market access shall be abandoned and replaced by simpler and more flexible ones.
  • Regulatory coherence, such as harmonization on labeling regulations, harmonization of product safety and test method regulations, and establishing of a harmonized list of prohibited substances.
  • Emphasis on facilitative customs provisions, meaning improving predictability, simplicity and uniformity in border procedures.  

The European Branded Clothing Alliance is also a party of the joint statement; however, the European Textile and Apparel Confederation (Euratex) is not involved.

On the other hand, in May 2014, the National Council of Textile Organizations (NCTO), which represents the interests of the US textile industry, announced its priorities for the T-TIP negation, including:

  • Adopt the “yarn-forward” rules of origin in T-TIP
  • Set phrase-out periods for sensitive textile and apparel products
  • Protect the Berry Amendment (which requires all US military uniforms have to be 100% made in USA)

Recent Scholarly Books about the Global Textile and Apparel Industry (Update: Aug 2014)

4 3 2 1


Why does the US Textile Industry Want Yarn-forward Rule of Origin (RoO) in TPP?

textile

My personal understanding: the US textile industry insists yarn-forward RoO in TPP is not because they expect a substantial increase of textile exports to Vietnam as the case of NAFTA and CAFTA which help capture the export markets in Mexico and Central America. But rather it is because:

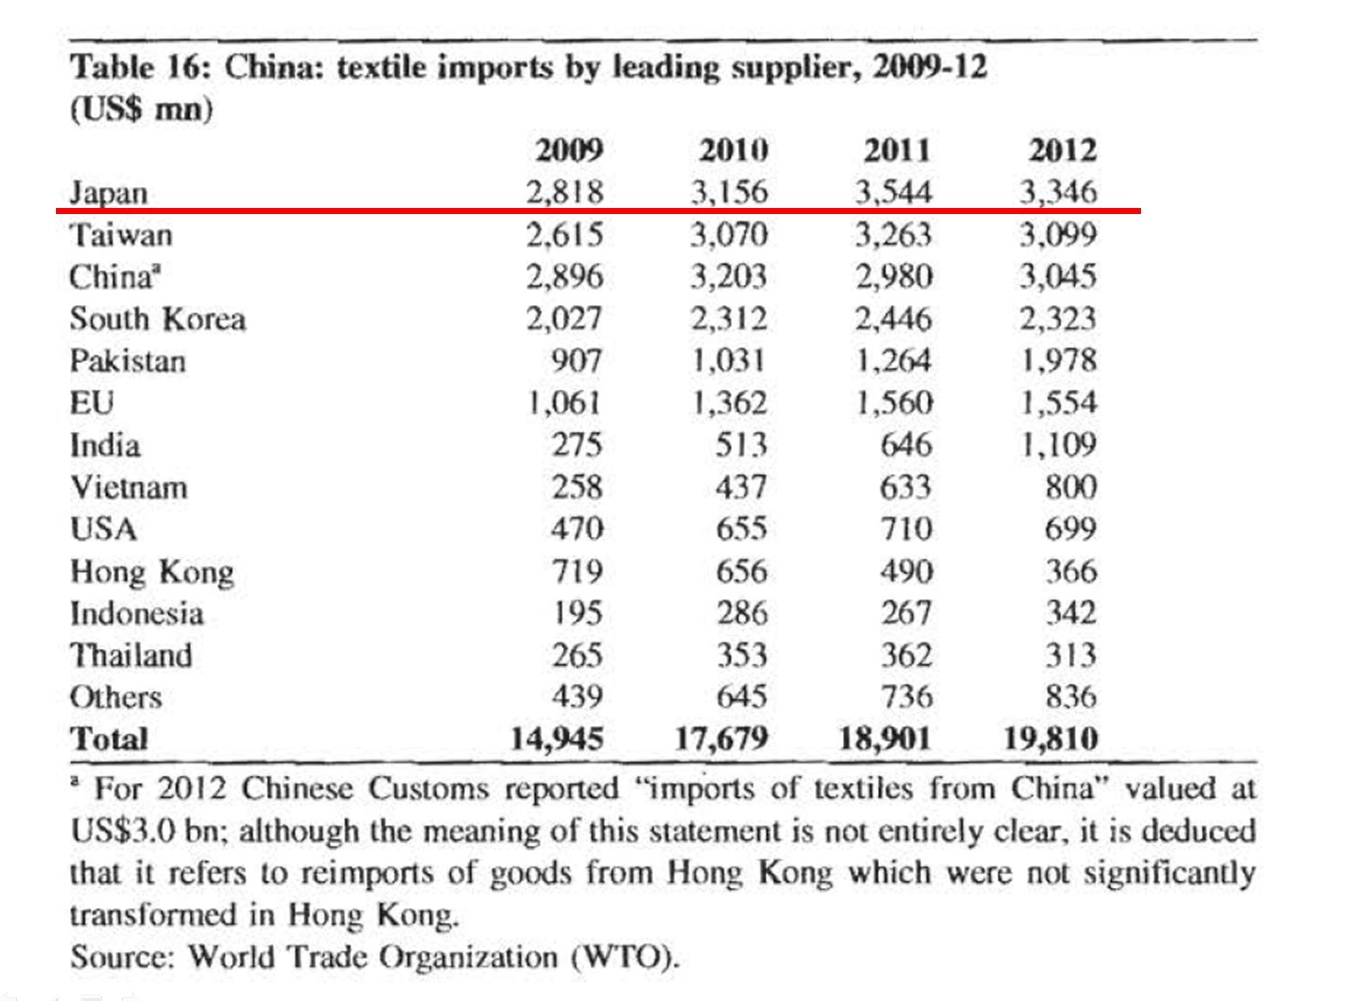
1) Without yarn-forward, situation will get even worse. Particularly, a less restrictive RoO will make Vietnam’s apparel exports which contain textiles made in China, Taiwan or South Korea qualified for duty free access to the US market. Definitely this will be a more imminent and bigger threat to the US textile industry than simply facing competition from Vietnam’s apparel which contains Japanese made textiles. And still many US textile companies don’t treat the Japanese textile industry very seriously, although I think they should. Remember, Japan currently is the fourth largest textile supplier to Vietnam and the NO.1 textile supplier to China.

1

2

2) With yarn-forward RoO in place, at least US textile companies can invest in Vietnam (remember, globalization is about movement of capital as well. Many apparel companies in Mexico and Central America actually are invested by US companies). Without yarn-forward RoO however, Vietnam can simply rely on imported textiles as the case mentioned in (1) and there will be no incentive for US textile companies to move factories to Vietnam (meaning, capital holders will lose).  

So overall yarn-forward RoO may win a few more years for the US textile industry. But in the long run, it is my view that the US textile production and its exports to the Western Hemisphere countries may still inevitably decline (especially those output to be used for apparel assembly purposes) after the implementation of TPP. In the 21st century, the nature of competition is supply chain v.s. supply chain. 

The future of the US textile industry is those high-end markets, particularly technical & industrial textiles.  

Sheng Lu 

Additional Reading: The potential impact of TPP on the US textile industry

Textile and Apparel Sector in the TPP Negotiation: An Update

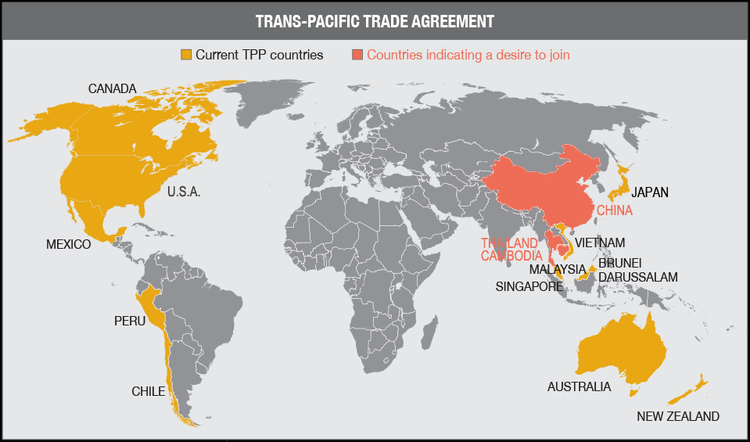
TPP_map

USTR objectives
Officially, USTR has announced the following objectives in the TPP for textile and apparel:

  • Elimination of tariffs on textile and apparel exports to TPP countries;
  • A “yarn forward” rule of origin, which requires that textile and apparel products be made using U.S. or other TPP country yarns and fabrics to qualify for the benefits of the agreement, so as to ensure that non-qualifying textiles and apparel from non-TPP countries do not enjoy the benefits reserved for TPP countries;
  • A carefully crafted “short supply” list, which would allow fabrics, yarns, and fibers that are not commercially available in the United States or other TPP countries to be sourced from non-TPP countries and used in the production of apparel in the TPP region without losing duty preference;
  • Strict enforcement provisions and customs cooperation commitments that will provide for verification of claims of origin or preferential treatment, and denial of preferential treatment or entry for suspect goods if claims cannot be verified; and
  • A textile specific safeguard mechanism that will allow the United States and other TPP countries to re-impose tariffs on certain goods if a surge in imports causes or threatens to cause serious damage to domestic producers.

X-basket
According to the National Council of Textile Organizations, with regard to the market access offer to Vietnam, textile and apparel products are categories into different groups based on their “sensitivity” to the domestic industry producing the like products. Among the three major categories, the so called “X-basket” will include textile and apparel items that are deemed most sensitive to the United States. Specific items to be included in the X-basket however are unclear and details of the phrase-out formula are still under discussion. It is said that items in the “X-basket” may be subject to an initial tariff cut ranging from 35 to 50 percent.

Vietnam’s top apparel exports to the United States are basic apparel items like shirts, sweaters and pants.  Many of them are the same types of items that were subject to the U.S. safeguard measures against China back in 2005. The U.S. textile industry hopes that the longer phrase-out period for items in the “X-basket” would provide needed time for the industry to adjust. However, for the Vietnam side, if duties on most of its apparel exports to the United States stay in place after the implementation of the TPP, the value of participating in the agreement would substantially be compromised.

Short-supply list
The short-supply list is a roster of fabrics and other textile inputs that are determined to not be readily available in the TPP region in commercial quantities on a timely basis and can therefore be imported from third countries. Items on the short-supply list would be exempt from the general “yarn-forward” rule of origin that the U.S. has proposed in the textiles and apparel talks. USTR is pushing for a short-supply list that would have permanent items as well as temporary items that will be removed after three years. Previous U.S. free trade agreements, including CAFTA, have included a short supply process to add additional products to the list once the agreement enters into force. But the U.S. has rejected the notion that the short-supply list could be modified after the TPP enters into force.

Mexico has consistently sought to limit the scope of the short-supply list, arguing that it actually makes some of the products that the U.S. had originally proposed for inclusion in the short-supply list. Mexico was also pushing for roughly 70 items proposed for the short supply to be included only on a temporary basis, rather than a permanent one.

Other TPP members’ positions
According to the Inside US Trade, Malaysia’s textile and apparel industry is supporting U.S. calls for a “yarn-forward” rule of origin in TPP, but is also pushing for a range of exceptions such as cut-and-sew allowances and a short supply list that would be periodically reviewed. Among the items the Malaysian industry would like to see on the short supply list are shirting fabrics such as woven cotton fabric that weighs not more than 250 grams because this type of fabric is said not made in the U.S. nor Malaysia.

Related reading
Lu, S. (2014). Does Japan’s accession to the Trans-Pacific Partnership an opportunity or a threat to the U.S. textile industry: A quantitative analysis. Journal of the Textile Institute. (ahead of print version) 


2014 USFIA Benchmarking Study Released

UntitledKey Findings

  • China will remain the dominant supplier, though Vietnam and Asia as a whole are seen as having more growth potential.
  • Companies aren’t leaving Bangladesh, and are committed to compliance.
  • Companies continue to look for opportunities closer to home, including the United States, as they diversify their sourcing.
  • Companies are diversifying their sourcing and expect to continue to do so. However, current FTAs and preference programs remain under-utilized or don’t represent a major component of respondents’ sourcing.
  • Respondents welcome the passage or renewal of all future trade agreements that intend to remove trade barriers and facilitate international trade in the industry.

About the Benchmarking Study
The 2014 USFIA benchmarking study is conducted based on a survey of 29 executives at 29 leading U.S. fashion companies from March to April 2014. The study incorporates a balanced mix of respondents representing various business types in the U.S. fashion industry, including retailers, importers, wholesalers, and manufacturers. The survey asked respondents about the business outlook, sourcing practices, utilization of Free Trade Agreements and preference programs, and views on trade policy.

The full study can be downloaded from HERE.

Why Textile and Apparel Majors Need to Know about Trade Policy

Untitled

This past week, our class moved to the topic of trade policy, which as usual turned out to be one of the most challenging and “least exciting” chapters for our students. A common question in students’ mind is (and probably for some professors in the textile and apparel field as well): as a fashion major, why do I need to care about trade policy?

The answer is straightforward: textile market is shaped by rules—trade policy. Trade policy affects the availability of T&A products in the market in terms of quantity, price and speed. Trade policy also affects T&A companies’ access to the market, both domestic and foreign. Simply look at the clothing and shoes we wear daily: if they are imported, very likely the price we pay includes 10-30% additional tax (tariff). Even the clothing is “made in USA”, we should realize that the survival of US domestic apparel manufacturing could be the result of protection by the exact same trade policy which makes imported competing products 10—30% more expensive than otherwise in the US market.

Yet, trade policy does not happen naturally. Trade policies are deliberately made by policymakers and strongly influenced by industry players. Two things I hope our students can realize: first, the T&A industry cannot afford ignoring trade policy. Think about this case: if the US yarn manufacturers did not actively advocate “yarn-forward” rules of origin to be adopted in NAFTA and CAFTA, what will happen to their fate right now? Vice versa, how will the commercial interests of apparel retailers/importers be affected if they stop voicing themselves and simply leave the trade protectionism forces to influence trade policymakers? As the saying goes: if you are not at the table, you are on the menu. To certain extent, there is no good or bad trade policy, but winners and losers.

Second, understanding trade policy making is about understanding the real world. Trade policymaking is a painful balancing process like trying to “breathe and suck at the same time”.Not only different interests groups may have conflicting views on a specific trade policy, but also different policymakers may have their respective philosophies and priorities. As we mentioned in the class, agencies in the executive branch such as the US Trade Representative Office and the Commerce Department put national interests and international obligations of the United States at its heart whereas the Congress often times gives preferences to regional, sectoral and party interests.  A full understanding of T&A trade policy thus requires familiarity with what’s going on in this unique industry sector, knowledge about its key players as well as having a big picture vision in mind. For example, without recognizing the value of becoming a WTO member for China, it will be difficult to appreciate why it was willing to allow US to restrict its apparel exports from 2003 to 2008 on a discriminatory basis (T-shirt book, part III).

Our FASH students shall be encouraged to jump out of the narrowly-defined fashion world, because no industry operates as an island. Instead, the T&A industry is part of the world economy and shaped by the “rest” of the world economy.

 Sheng Lu

The Ways and Means Hearing Shows Divided Views on US Trade Policy for Textiles and Apparel

ways&means

US Trade Representative Michael Froman testified on Obama’s 2014 trade policy agenda before the House Ways and Means Committee on April 3. Issues concerning the textile, apparel and the footwear industry were raised three times during the 3-hour hearing. However, it seems the Congress is much divided on how to deal with the T&A sector deemed as “sensitive” in the FTA talks.

(1h:42’)Mike Thompson (D-CA) asked Froman to reevaluate the value of including the “yarn-forward” rules of origin (RoO) in the TPP. Thompson suggested that this rule only affects a small proportion of the US apparel imports nowadays (Note: according to Froman, it was $13 billion annually or 17% of the total US apparel imports) and no longer meets the needs of the US outdoor apparel industry which demands more flexible RoO in supporting of their business model. In response, Forman said that “the USTR’s approach to T&A is always being to ensure to strike a balance that helps the domestic producers continue to produce while allowing importers to import products that serve customers…”

(2h:06’) Earl Blumenauer (D-OR) asked Froman to reduce the trade barriers (tariff and NTB) on footwear imports, arguing that less than 1% of the footwear consumed in the US nowadays is domestically produced. He said that the high tariff rates both retard the ability of the US footwear industry to concentrate on those parts of the value chain that it enjoys competitive advantages and hurt the interests of the US consumers. In response, Forman said that footwear has been a sensitive and key issue to the US and among other TPP members. According to Forman, USTR has been working both with the domestic producers and the importers to develop an approach hoping to achieve the right balance that the domestic producers can continue to compete and also the importers can bring in high quality products (from overseas) for the US consumers. Additionally, Forman referred to the footwear industry an “outstanding area” in the TPP negotiation and said that discussion among all partners will continue.

Last but not least, (2h:30’) Bill Pascrell(D-NJ), also the chair of the house textile caucus, reiterated the importance of the yarn-forward RoO to the US textile industry and asked Froman to ensure that the USTR will “seek the longest possible duty phrase out for the most sensitive textile items” in the TPP negotiation. In his reply to Pascrell, Forman said that his team will work with all stakeholders of the US T&A industry to fully understand what these “sensitive textile items” are and will use tools like the “phrase out period” and “short supply list” to strike a right balance. Pascrell also expressed the concerns of the US textile industry about Vietnam’s wanting of immediate access to the US apparel market after the implementation of the TPP. However, Forman declined to give any concrete promise, just saying the USTR commits to create the “maximum number of jobs in the US” through the trade talks[Note: textile industry jobs? Apparel retail jobs?].

In addition to the T&A, other issues mentioned in the hearing include TPA, GSP, TAA, IPR, SPS & TBT, TTIP, SOE, TiSA, ITA and WTO.

Full hearing can be viewed here

Sheng Lu

Digital Economy and the Fashion Industry: A Macroview

Part I

Part II

Part III

Textile and Apparel–Key Trade Terms (updated October 2015)

FTAThe following important trade terms for textile and apparel are supplementary to what we’ve learnt in class:

Cumulation – Yarns and/or fabrics from one FTA partner country to be used in another FTA partner country and qualify for duty-free benefits (In NAFTA and the future TPP agreement, cumulation is among FTA partners only) . Example: in CAFTA certain woven fabrics from Mexico (NAFTA) can be used for the manufacture of apparel in the CAFTA region and qualify for CAFTA benefits, i.e. duty-free access to the U.S. market.

Tariff Preference Level (TPL) – An exception to the rule of origin in FTAs that allows for a certain quantity of textile and apparel goods (usually yarns, fabrics and cut pieces) from a third-country (a country who is not a party to the agreement) to qualify for the FTA benefits. Example: Under the U.S.-Bahrain FTA, Bahrain can use up to 65 million sme of yarns and fabric from any other country and the products made from those yarns and fabrics (up to the 65 million limit) still qualify for duty-free access to the U.S. market.

807: a commonly used term (formerly utilized by US Customs) to describe a category of apparel which has been assembled in an overseas country from fabric pieces cut in the USA from fabric formed in any country. The duty levied on apparel imported under 807 is based only on the value added to the goods overseas rather than the whole customs value of the goods. This provision is now specified under code 9802.00.8065 of the USA’s Harmonized Tariff Schedule (HTS). This outward processing arrangement benefits mainly countries which are close to the USA—particularly those in the Caribbean Basin

807A: a commonly used term (formerly utilized by US Customs) to describe a category of apparel which has been assembled in an overseas country from fabric pieces cut and formed in the USA. The duty levied on apparel imported under 807A, a modification of 807, is based only on the value added to the goods overseas rather than the whole customs value of the goods. Also, goods imported under 807A are provided with almost unlimited access to the US market. This provision is specified under code 9802.00.8015 of the USA’s Harmonized Tariff Schedule (HTS).

Short Supply/Commercial Availability — Fibers, yarns, and fabrics determined not to be available in commercial quantities in a timely manner from within the FTA partner countries may be sourced from outside the countries for use in qualifying textile and apparel products. For example, a fabric that is determined not to be commercially available under the U.S.-Australia FTA may come from a third-party, i.e. China, be cut-and-assembled into a garment in Australia, and imported to the U.S. duty-free.

Square Meter Equivalents (SME) – A notional, common unit of quantity, constant across apparel categories. Conversion factors are used to convert units of quantity into SME. Common measurement used to determine specific quantities of yarns, fabric, and apparel allowed under exceptions to the rule of origin, i.e. TPLs, cumulation.

Third Country – A country outside of the FTA or preferential trade arrangement, but is not a party to the agreement and is not required to adhere to the rules of origin under the agreement but may supply inputs to the FTA countries.

Earned Import Allowance Program (EIAP)– Certain amount of apparel assembled in a FTA partner using U.S. yarn and fabric will allow certain amount of apparel assembled in that country using third party yarn and fabric also to enter the U.S. duty free. For example, under CAFTA-DR, every two square meter equivalent (SME) of apparel assembled in Dominican Republic using U.S. yarn and fabric allows one SME of apparel assembled in Dominican Republic using third party yarn and fabric to enter the U.S. duty free.

Wholly-Assembled – A good is wholly assembled if all of its components, of which there must be at least two, pre-existed in essentially the same condition as found in the finished good and were combined to form the finished good. For example, the sewing together of the sleeves and the body of a shirt would be considered to be wholly assembled.

Knit-to-Shape — A good is considered “knit-to-shape” if 50 percent or more of the exterior surface area of the good is formed by major parts that have been knitted or crocheted directly to the shape used in the good, with no consideration being given to patch pockets, appliqués, or the like. Minor cutting, trimming, or sewing of those major parts shall not affect the determination of whether a good is “knit-to-shape.”

Source: US Trade Representative Office; Office of Textile and Apparel, US Department of Commerce