New Study: Do US apparel retailers absorb or pass through tariff costs? Evidence from US apparel import and retail prices, 2015–2025

Summary

Background

In the context of the significant tariff hikes during President Trump’s second term, there has been heated debate about who ultimately bears the cost of higher U.S. import tariffs. Do U.S. apparel retailers pass these additional costs on to consumers through higher retail prices, or do they absorb a substantial share of the costs themselves?

Research question

Using monthly U.S. government data from January 2015 through December 2025, the study examines how apparel tariff changes are transmitted through the import-to-retail pricing chain. Rather than looking only at consumer prices, the study considered three interconnected factors: U.S. apparel import tariff rates, U.S. apparel import prices, and U.S. apparel retail prices. The analysis also included U.S. apparel retail sales to reflect shifting consumer demand.

Findings

Challenging the common perception that higher tariffs inevitably lead to higher clothing price tags in the retail market, the findings suggest that tariff increases do not necessarily translate into proportionally higher retail prices. Instead, a substantial share of the tariff burden appears to be absorbed by U.S. fashion companies and their suppliers, rather than being fully passed on to consumers, at least in the short to medium term. Specifically:
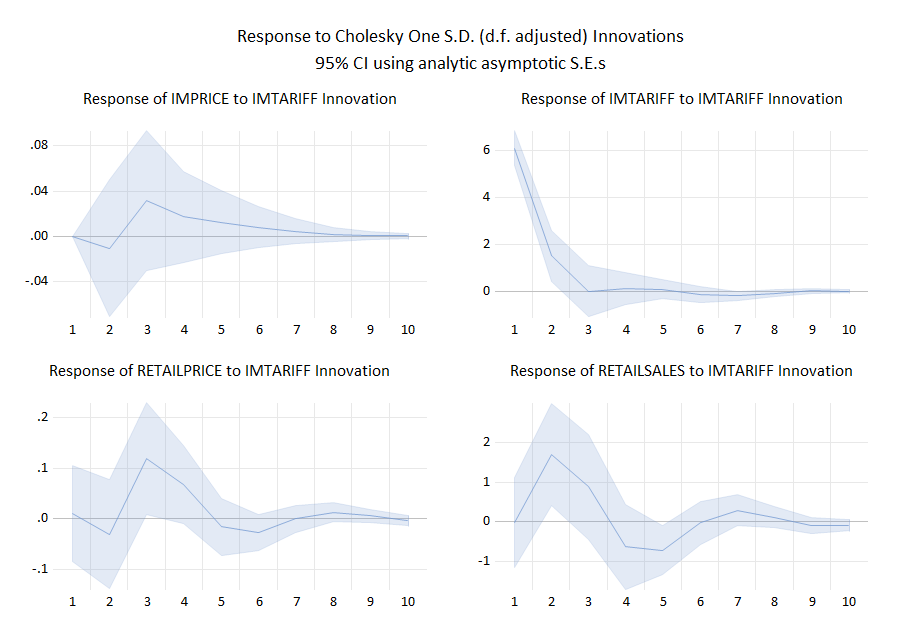
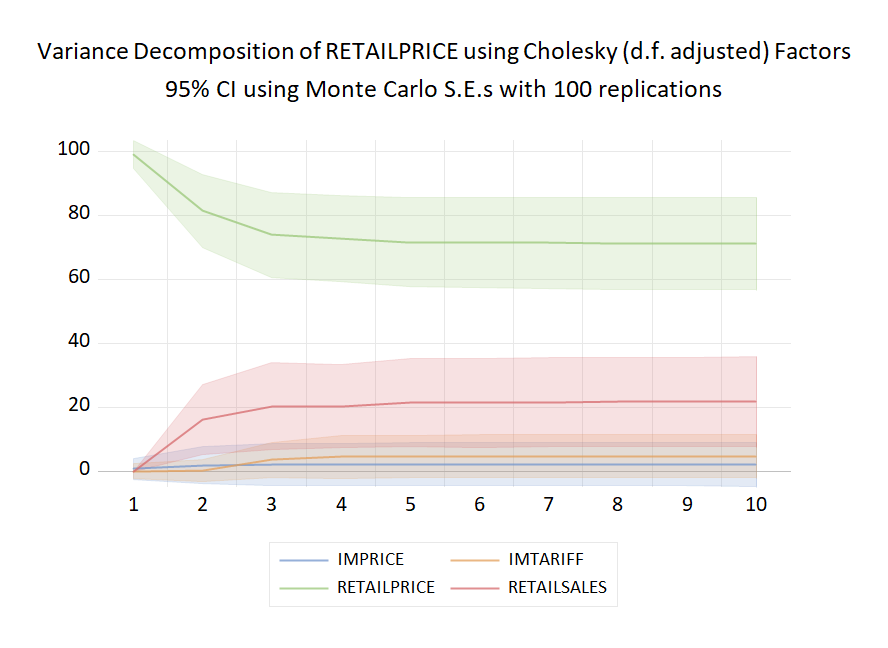
First, higher tariffs do not automatically translate into higher apparel import prices. One particularly interesting finding is that U.S. apparel import prices showed relatively little response to tariff increases. In the statistical analysis, tariff shocks explained only approximately 1.2% of the variation in U.S. apparel import prices over a ten-month forecast horizon. More than 95% of the variation was explained by import prices’ own historical dynamics. In other words, changes in tariffs alone did not explain much of the month-to-month movement in U.S. apparel import prices.

Several factors could contribute to this intriguing pattern. One is that apparel sourcing operates on relatively long planning and purchasing cycles. Brands and retailers often negotiate prices and place orders with overseas suppliers several months before products arrive in the United States. Consequently, import prices may not adjust immediately when trade policies change.

In addition, importers and suppliers may renegotiate prices and share some of the additional tariff burden, at least initially. However, this arrangement can put additional financial pressure on overseas manufacturers, many of which already operate with relatively thin profit margins.

Second, U.S. apparel retail prices respond to tariffs, but the increase could be delayed. According to the study, while U.S. apparel retail prices do respond positively to tariff increases, the response is relatively small and temporary. The statistical analysis finds that apparel retail prices initially show no statistically significant increase following a tariff shock. A measurable positive response emerges approximately three months later. However, this effect weakens quickly and becomes statistically insignificant afterward. In other words, U.S. apparel retailers do not immediately pass the full impact of higher import costs on to consumers. Instead, they appear to absorb a substantial share of additional costs, at least in the short to medium term.

Several factors could help explain this behavior. The U.S. apparel retail market is highly competitive, and consumers have many alternatives when shopping for clothing. Retailers may therefore be reluctant to increase prices substantially because doing so could cause customers to switch to competitors. Retailers may also have opportunities to renegotiate supplier prices, adjust sourcing arrangements, or modify product assortments to manage additional costs.

It should be noted that the findings do not suggest that tariffs have no impact on apparel prices. Rather, they show that tariff costs are transmitted to consumers neither immediately nor proportionally. Over a ten-month forecast horizon, tariff changes explain only about 5% of the variation in U.S. apparel retail prices. By comparison, retailers’ historical pricing patterns explain the largest share, over 70%, of price fluctuations, while consumer demand accounts for approximately 16%–22%.

Implications

As the findings suggest, the key question facing the U.S. apparel industry amid tariff hikes is not simply whether tariffs will make clothing more expensive, but how companies across the global supply chain will absorb, share, and manage the resulting costs. In the context of continued trade policy uncertainty, understanding these dynamics will be increasingly important for fashion companies as they make sourcing, pricing, and supplier-management decisions.

For overseas apparel manufacturers, the findings also raise an important question: as U.S. importers face higher tariff costs, will suppliers be increasingly asked to share the burden by lowering export prices? Such pressure could further strain manufacturers’ profitability and influence their relationships with U.S. buyers.

For policymakers, the findings underscore the importance of looking beyond changes in consumer or retail prices when evaluating the economic impact of tariffs. Limited increases in retail prices do not necessarily mean that tariffs impose limited costs. Rather, policymakers should also examine how tariff costs are absorbed and distributed across the global apparel value chain, including their effects on retailers, overseas suppliers, and other industry stakeholders.

By Sheng Lu

Full paper: Lu, S. (2026). Do U.S. Apparel Retailers Absorb or Pass Through Tariff Costs? Evidence from U.S. Apparel Import and Retail Prices, 2015–2025. Research Journal of Textile and Apparel, ahead of print
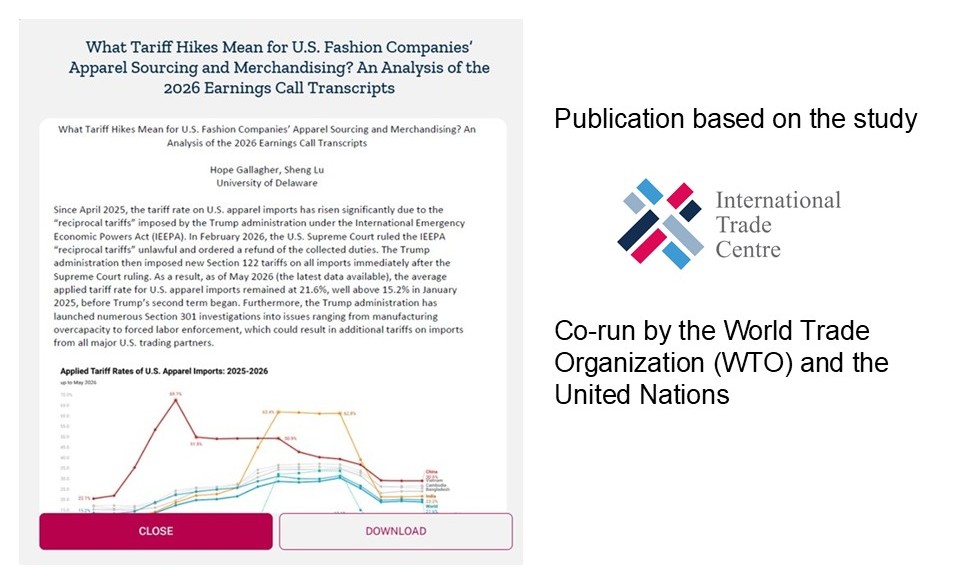
What Tariff Hikes Mean for U.S. Fashion Companies’ Apparel Sourcing and Merchandising? An Analysis of the 2026 Earnings Call Transcripts

About the study

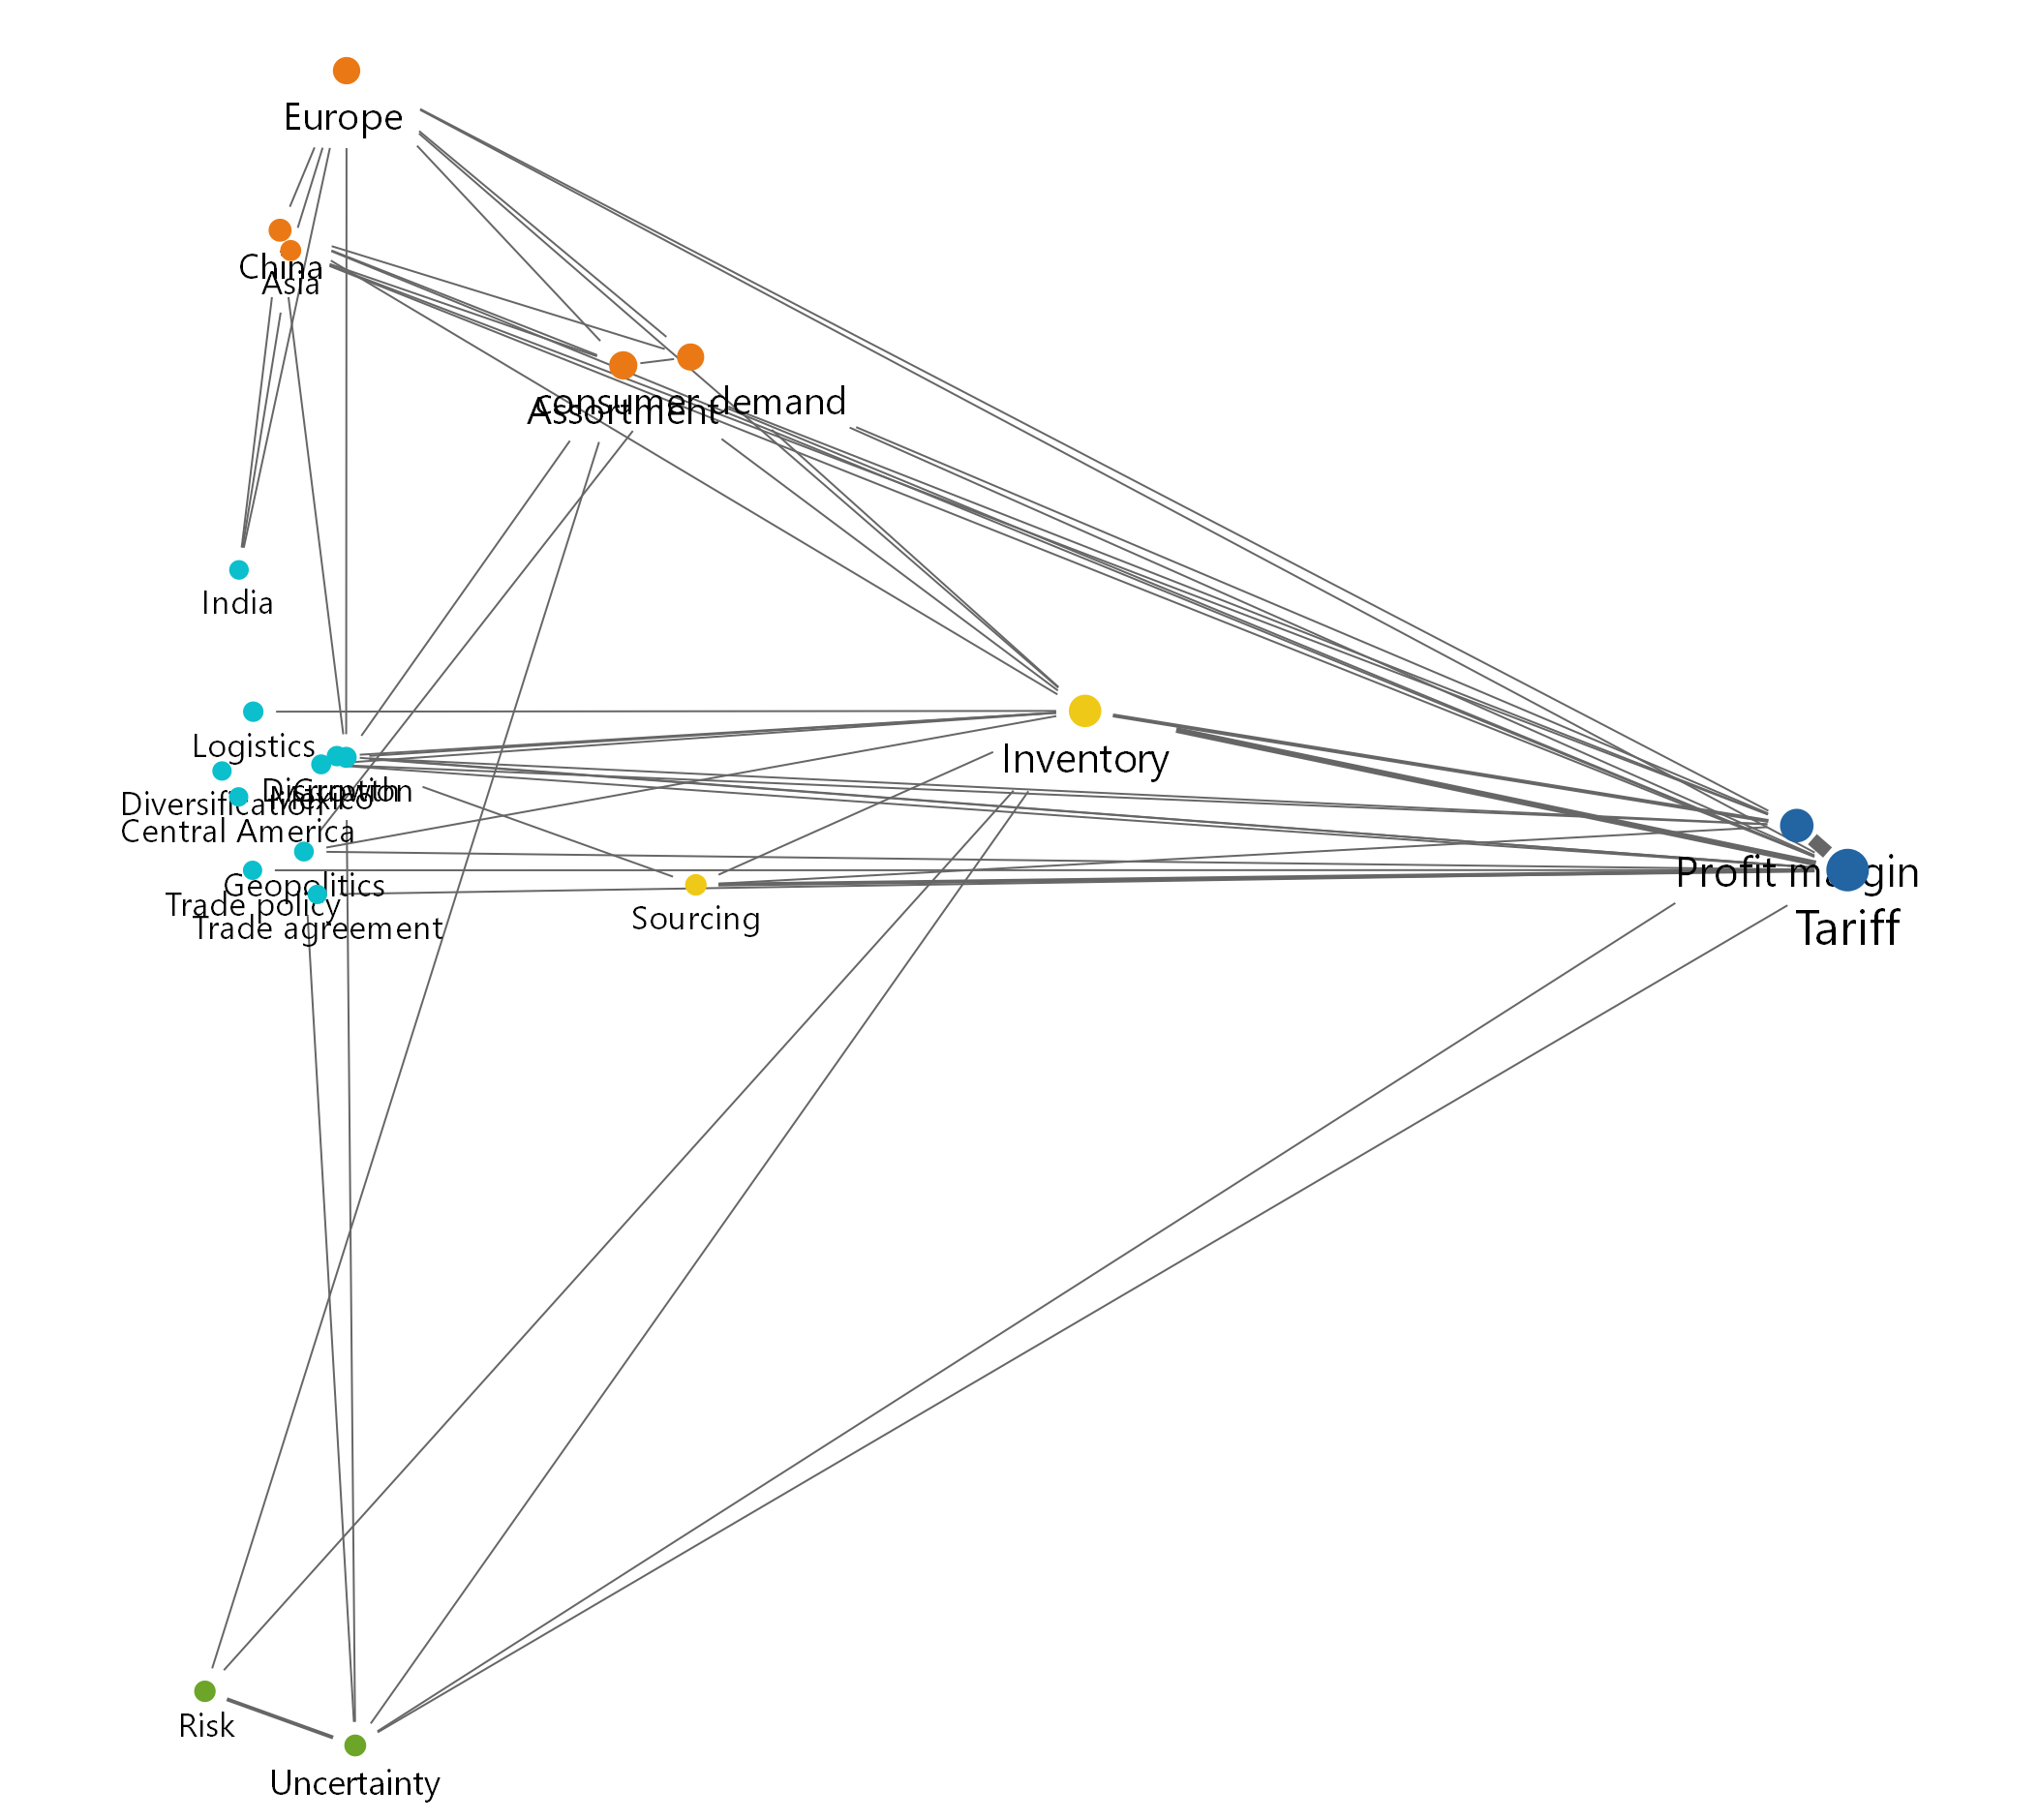
The unprecedented tariff hikes and policy uncertainty since President Trump’s second term began in early 2025 have directly and significantly affected U.S. fashion companies’ financial performance and key business operations. Based on a content analysis of 30 leading U.S. fashion companies’ earnings call transcripts from April to June 2026, this study explored the evolving impacts of tariff hikes and policy uncertainty on U.S. fashion companies’ sourcing and merchandising practices.

The results show that the effects of tariffs on U.S. fashion companies have gone far beyond costs, affecting broader sourcing, assortment, and pricing practices. In particular, the uncertainty surrounding tariff policy appears to be even more concerning to U.S. fashion companies than the tariff hikes themselves, as sourcing relies on advance planning. Meanwhile, the findings illustrate that U.S. fashion companies have transitioned from short-term responses to tariff hikes to more medium- to long-term responses.

The study’s findings provide new insights into the apparel-sector-specific effects of tariff policy and offer valuable input that can help fashion companies navigate the evolving sourcing and business landscape.

About the authors

Read the publication based on the study: Gallagher, H., & Lu, S. (2026). What Tariff Hikes Mean for U.S. Fashion Companies’ Apparel Sourcing and Merchandising? An Analysis of the 2026 Earnings Call Transcripts. Global Textile Academy, International Trade Centre, Geneva, Switzerland.

U.S. Fashion Companies’ Evolving Sourcing Practices amid Tariffs and Geopolitical Tensions (Updated April 2026)

This study aims to examine U.S. fashion companies’ evolving apparel sourcing and business practices in response to a shifting business environment, including ongoing hiking tariffs and geopolitical tensions. Based on data availability, transcripts of the latest earnings calls from about 30 leading publicly traded U.S. fashion companies were collected. These earnings calls were held between February and April 2026, reflecting company performance in the last quarter of 2025 or later. A thematic analysis of the transcripts was conducted using MAXQDA.

Key findings:

First, U.S. fashion companies identified shifting consumer demand, macroeconomic volatility, tariff hikes, and ongoing policy uncertainty as their main business concerns. The pressure on middle- to low-income consumers’ discretionary spending was emphasized as a structural issue that could persist in 2026. For example:

  • Kohls: “consumer is behaving differently in this challenging macroeconomic environment. We know our core low to middle-income customers continue to face financial pressure, and they are seeking value…”
  • Macy’s : “Our customers across nameplates skew more towards the middle and upper-income tiers. Performance remains stronger in these cohorts, while the lower tiers remain more choiceful. As we look ahead, there are many macroeconomic and geopolitical factors that could influence discretionary spend…”
  • Carter’s: “It continues to be a challenging time to forecast the business. Consumer spending appears to have held up well, while other macro indicators, such as consumer confidence and overall inflation, are less positive. Tariffs continue to dominate the headlines… there continues to be a great deal of uncertainty about where all this will settle…”
  • Oxford industries: “In an uncertain consumer environment, success comes from controlling what we can control and staying focused on execution…(we) have increased our flexibility and better positioned us to navigate continued uncertainty in the marketplace…”

Second, raising retail prices and focusing on full-price selling have become more common and systematic approaches among U.S. fashion companies to mitigate the impact of tariffs. Nonetheless, fashion companies remain selective–price increases have mostly occurred on fashion-forward, trend-driven, and premium items, while avoiding significant price increases for basic and core categories to shield most price-sensitive consumers. Companies also try to leverage new products and product innovation to justify the price increase. Additionally, many companies have reported that consumers have shown “no resistance” to price increases so far. For example:

  • Columbia Sportswear: “For both Spring 2026 and Fall 2026, we increased U.S. pricing by a high-single digit percent. When combined with our other mitigation tactics, our goal in 2026 is to offset the dollar impact of higher tariffs…Retailers remain cautious as tariff-induced price increases are just now beginning to hit the marketplace.”
  • Levi’s: “So tariffs, as I mentioned in my prepared remarks, impacts gross margins adversely by about 150 basis points, and we have an FX headwind of about 20. We’re fully offsetting this with higher pricing…We’re not seeing any initial demand reaction to it, so the elasticity is pretty good. More full price selling, which is, something that we’ve been focusing now for about 12-18 months, especially as a product, you know, and newness is resonating well with the consumer. And then lower product costs, which are a combination of lower, you know, better, and lower quarter, as well as the negotiation with the vendors as we rationalize SKUs…reduce unproductive…assortment…”
  • Kontoor Brands: “Tariffs net of pricing represent a headwind to our gross margin rate in 2026. We’ve implemented price increases for Wrangler, Lee, and Helly Hansen as part of a holistic plan to mitigate the impact of the increases in tariffs. Our pricing strategies were thoughtful and developed in consideration of the fluid macro environment, the strength of our brands, our elasticity expectations in certain categories and channels, and the retail environment around the globe.”
  • Oxford industries: “The price increases implied in our guidance range from 4%-8% and vary by brand. These increases reflect a more elevated assortment as well as higher pricing on new product with relatively limited like-for-like increases on existing product.”
  • Victoria’s Secret: “Importantly, we pulled back on promotions, driving more regular price selling and double-digit AUR (average unit retail) expansion, which benefited margins across PINK’s portfolio, showing that the brand is regaining pricing power.”
  • URBN: “We’re being highly strategic and thoughtful about taking price, these are definitely not across-the-board price increases. We’ve taken small price increases where we felt the price-value equation was appropriate, have seen really little to no price resistance where we did so. We also want to stress that we remain committed to maintaining our opening price points and our pricing architecture and protecting those items that our customers count on to have great price value. Next, we’re really planning very little incremental price increases over and above what we’ve already implemented this fall and holiday. We really don’t anticipate price resistance. Our focus remains on protecting the integrity and the value of our product while we manage our cost structure appropriately…”

Third, regarding the apparel sourcing base, four strategies stand out: 1) continue sourcing diversification including reducing sourcing from China; 2) expand sourcing from other lower-cost manufacturing hubs in Asia, such as Bangladesh and Vietnam; 3) explore near-shoring opportunities in Mexico and Central America and take advantage of lower tariff benefits; 4) carefully monitor newly negotiated trade agreement with the US, especially those with textile and apparel-specific provisions, such as the one with Bangladesh. Meanwhile, many companies noted that full sourcing realignment takes 12–18 months or more. For example:

  • Oxford industries: “Early in fiscal 2025, approximately 40% of our apparel and related products were expected to be sourced from producers located in China. Through the actions we took during the year, that figure declined to slightly less than 30% of our product purchases in fiscal 2025, and our annualized run rate entering fiscal 2026 has been reduced to approximately 15%.”
  • Abercrombie & Fitch: “Obviously we’ve talked a lot about our sourcing footprint over the course of the last year or so. Really proud of that diversified network that we have in place, and it’s taken us years to build. We currently source from over 16 different countries. That’s been obviously a core enabler for us and our read and react model here. Approach isn’t changing…”
  • Kontoor Brands: “Of particular interest to us is the trade agreement with Bangladesh, which we highlighted. That trade agreement reflected a potential reciprocal tariff ranging from 0% to 19%, depending on the U.S.-grown cotton content of products sourced from Bangladesh. More than 80% of the product we source from Bangladesh does include U.S.-grown cotton. Bangladesh is our largest country of origin from a sourcing perspective, so by nature, it’s also our largest source of tariff pressure.”
  • Gildan: “we are pleased to announce that we are moving forward with phase two of our Bangladesh complex. Over the next 18 months, we will begin construction of our second large-scale textile facility, with initial production expected to come online in the later part of 2027. Expanding our Bangladesh footprint is central to reinforcing our cost leadership in ring spin and innerwear…we are increasing our internal capacity in Bangladesh and in Central America, obviously in anticipation to support the Hanes integration.”
  • Land’s end: “our teams just got back from a sourcing trip in India with one of our major airline partners, and they couldn’t be happier about the breadth that we’re able to offer, and the opportunity that we’re creating for their employees.”
  • Ralph Lauren: “You’ll start to see our broader mitigating actions take shape, country of origin shifts, optimization, merchandising actions. You’ll start to see those all come into play as we move through fiscal 2027”

Additionally, U.S. fashion companies closely monitor geopolitical tensions, including the ongoing conflict in the Middle East; however, the direct impact on sourcing remains limited, with greater concern centered on indirect disruptions to logistics and supply chain operations. For example:

  • Nike: “This quarter, we also experienced traffic disruption from the Middle East, and we also are you know taking that into consideration as we’re thinking about where this business stands, and also as we look forward”
  • Abercrombie & Fitch: “as it relates to some of the more near term news in the Middle East, you know, we do have some sourcing operations there in the region. Haven’t experienced any disruptions that would have any sort of meaningful impact to the receipt plans here that underpin our outlook. You know, we’ll keep monitoring that and we’ll keep agile with our sourcing base in total.”
  • PVH: “It’s important to highlight that significant uncertainty remains around the conflict in the Middle East as well as evolving global trade policies, the broader macroeconomic environment and consumer spend in behavior. Our business in the Middle East, excluding Turkey, is about 1% of our total revenue and solely a wholesale business, so the profit impact is disproportionate at approximately 7%.”
  • Victoria’s Secret: “in terms of Middle East, we’re obviously staying very close to the situation and monitoring the developments and how long this may last. There’s two areas right now that we’re paying close attention to. One is just shipments to North America. We are experiencing some delays, but not material that are gonna have a broader impact on the business that way. As you said, we’ve got franchise partners in the Middle East. There are a handful of store closures right now.”

By Sheng Lu

Read the full paper: Lu, S. (2026). U.S. Fashion Companies’ Evolving Sourcing and Business Practices. Global Textile Academy, International Trade Centre (ITC). Geneva, Switzerland

Tariffs Impact U.S. Apparel Sourcing and Trade Beyond Just Price (updated March 2026)

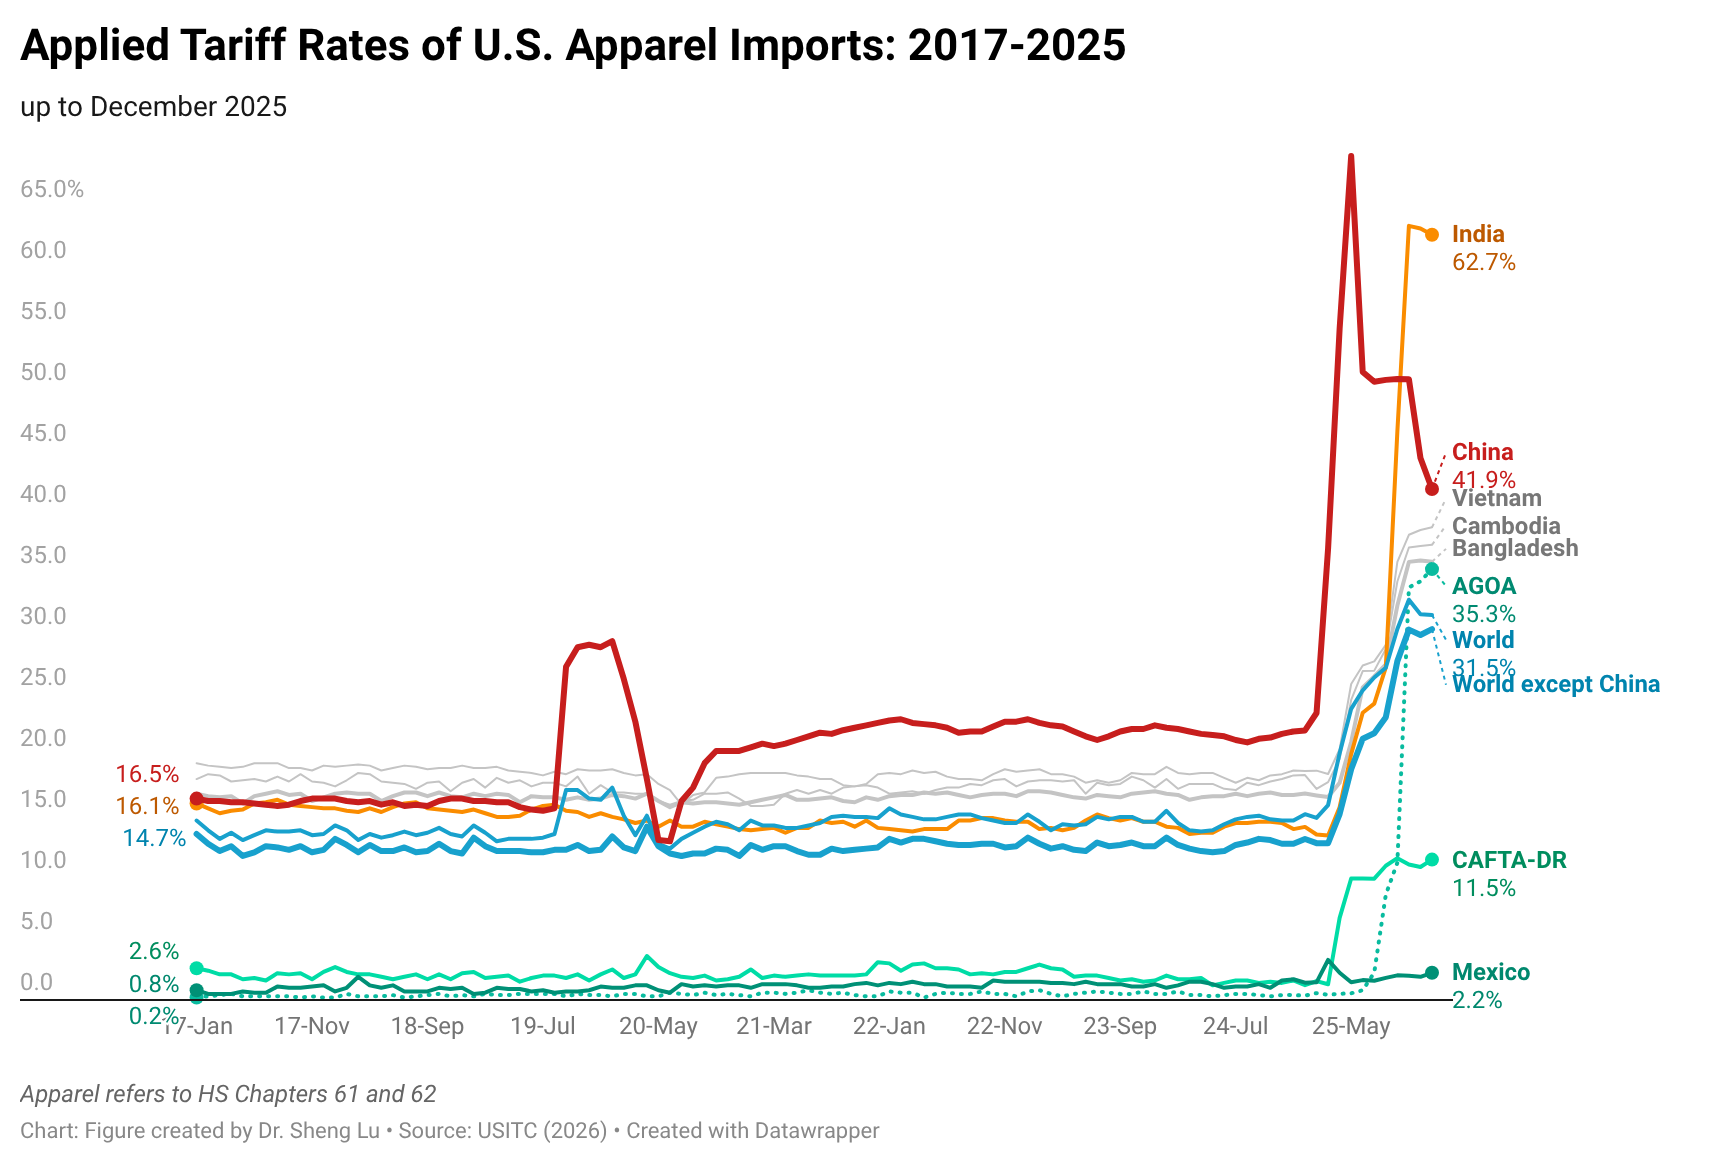
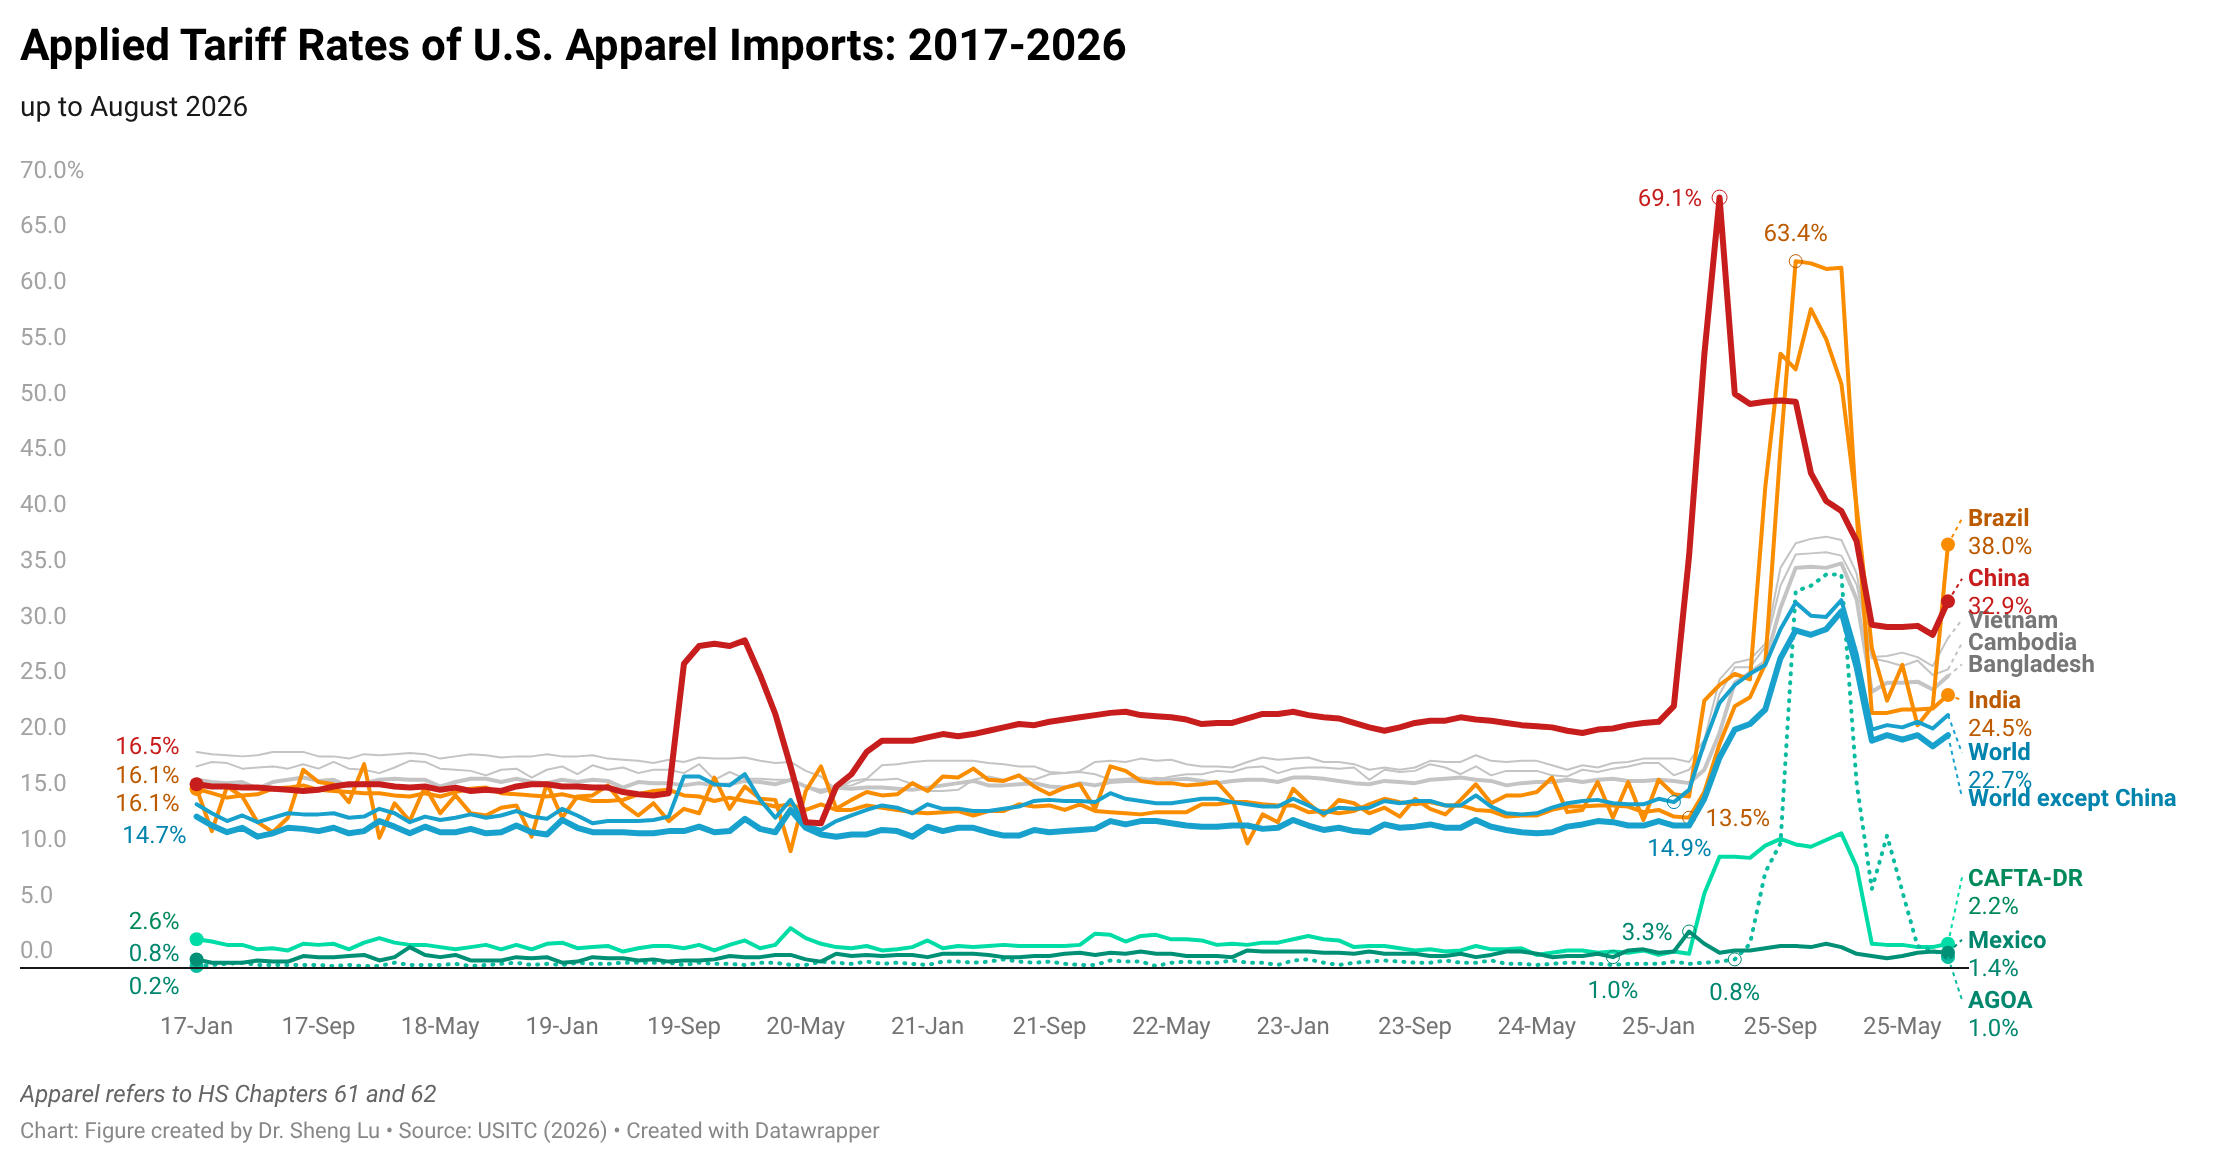
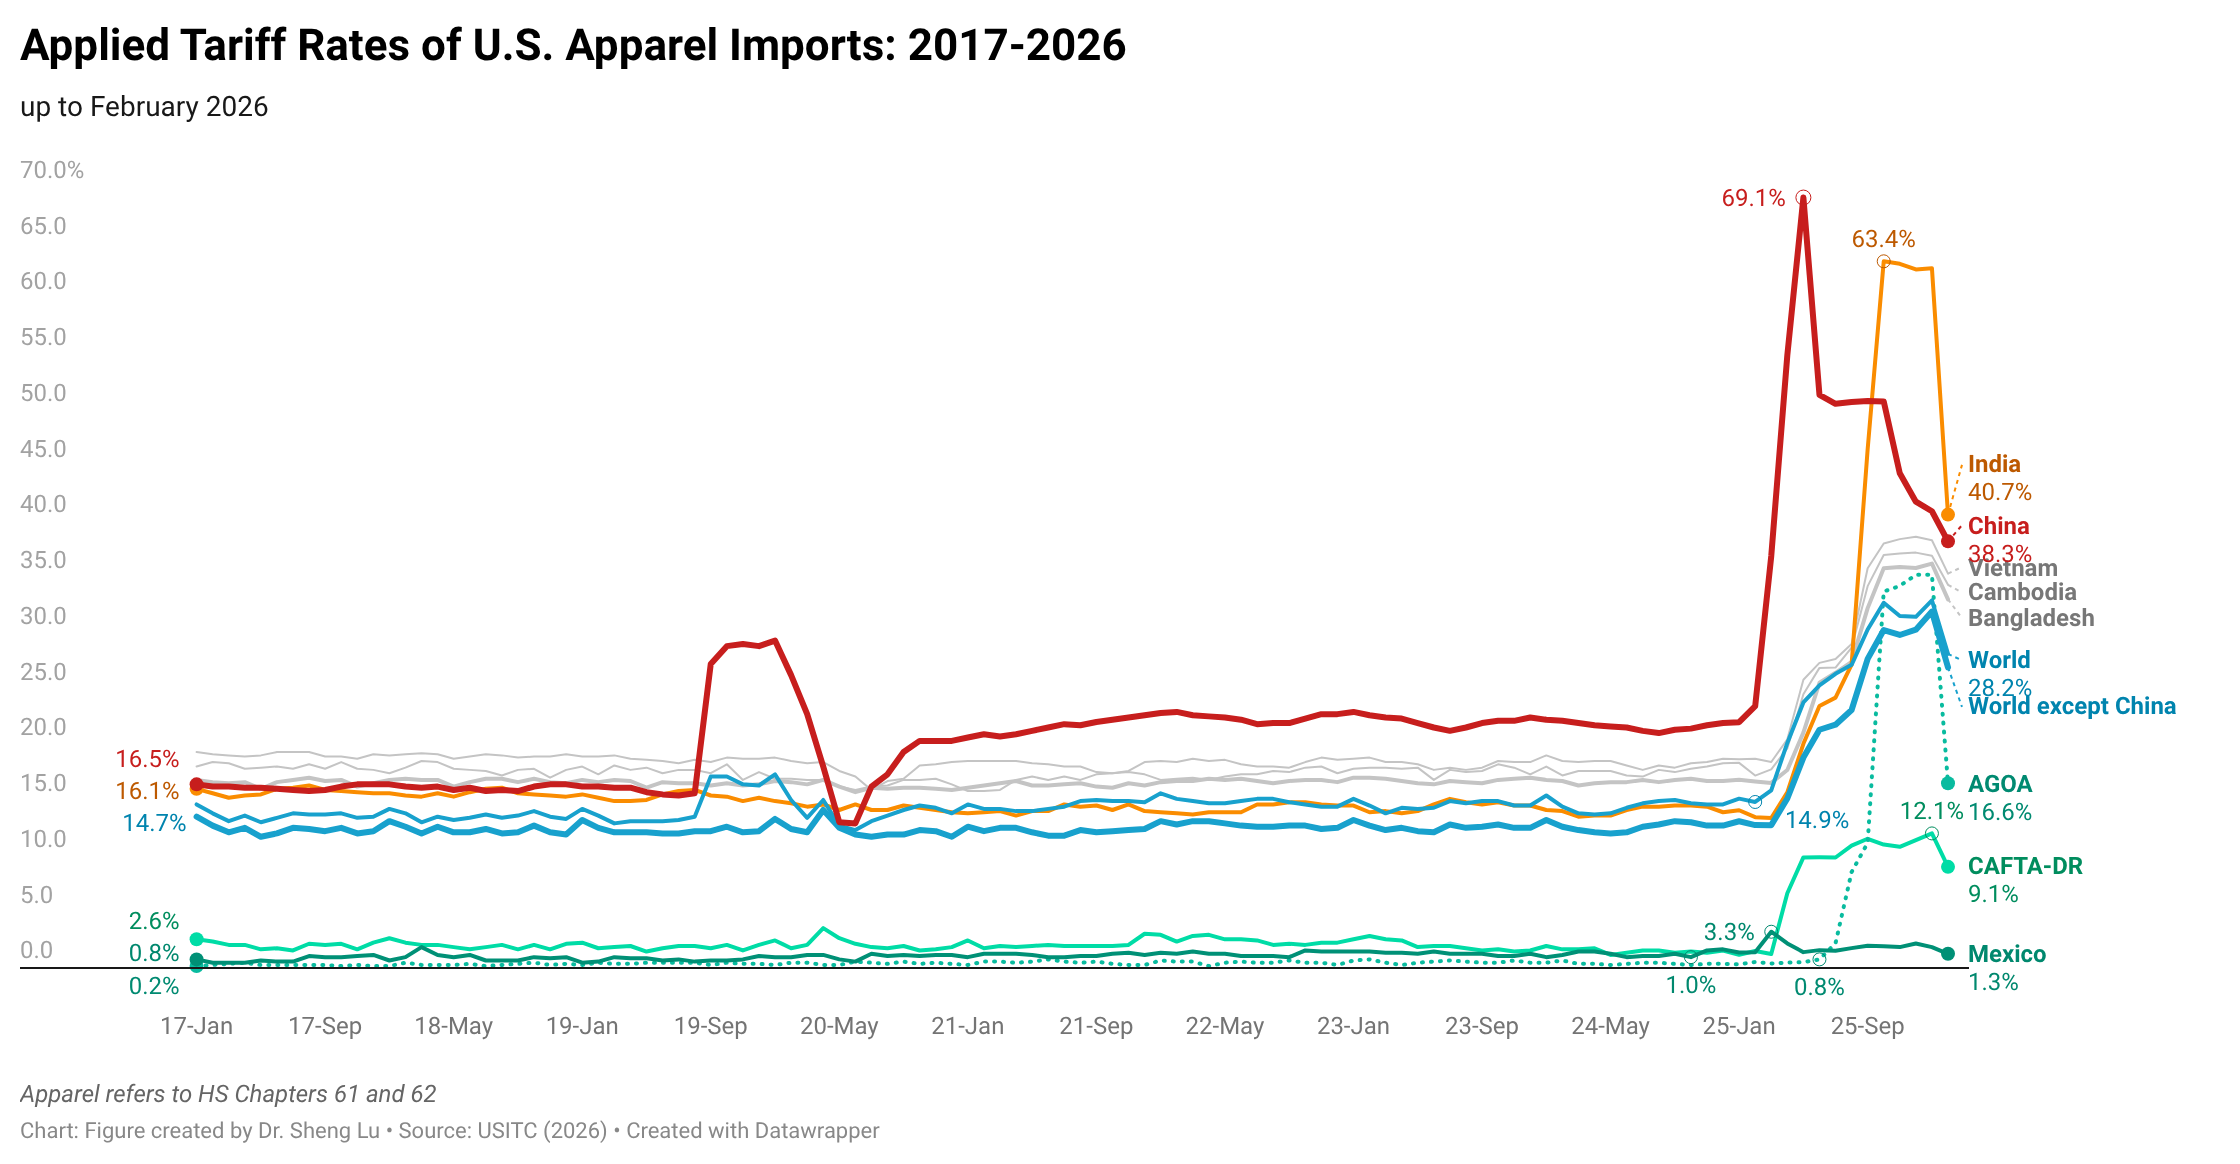
The average tariff rate for U.S. apparel imports (HS Chapters 61 and 62) reached 35.1% in December 2025, hitting a new high in decades and a sharp rise from 14.7% in January 2025, before President Trump’s second term. According to statistics from the Office of Textiles and Apparel (OTEXA), the U.S. International Trade Commission (USITC), and other government agencies, the hiking of tariffs and associated policy uncertainty has affected U.S. apparel sourcing and trade in multiple ways. [click here for detailed tariff data]

Impacts on apparel import price

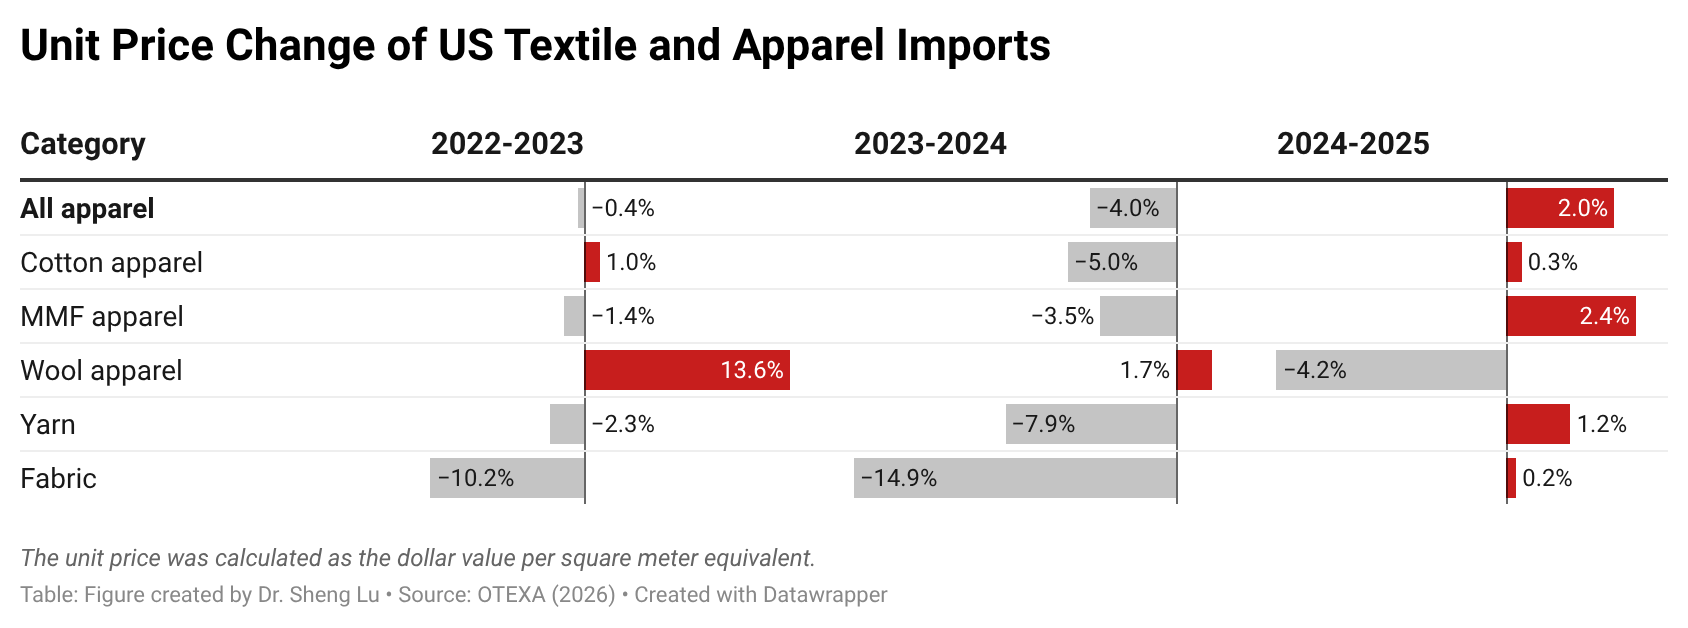
Apparel sourcing cost pressure increased in 2025, although price changes varied by fiber type. Data from OTEXA shows that, measured in dollars per square meter equivalent (SME), the unit price of US apparel imports increased from $3.08/SME in 2024 to $3.14/SME in 2025, a 2% year-over-year increase. Notably, due to an overall downward trend in world cotton prices, the unit price of US cotton apparel imports was almost flat in 2025, after a 5% decline in 2024.

In contrast, amid ongoing geopolitical tensions and rising oil prices, the unit price of US man-made fiber (MMF) apparel imports increased more noticeably by 2.4% in 2025. Still, in absolute terms, the unit price of US MMF apparel at $2.58/SME in 2025 was only about two-thirds of the price of cotton apparel at $3.59/SME.

Additionally, due to weaker demand for relatively more expensive clothing, the unit price of US wool apparel increased from $21.6/SME to only $20.68/SME, or down 4.2%.

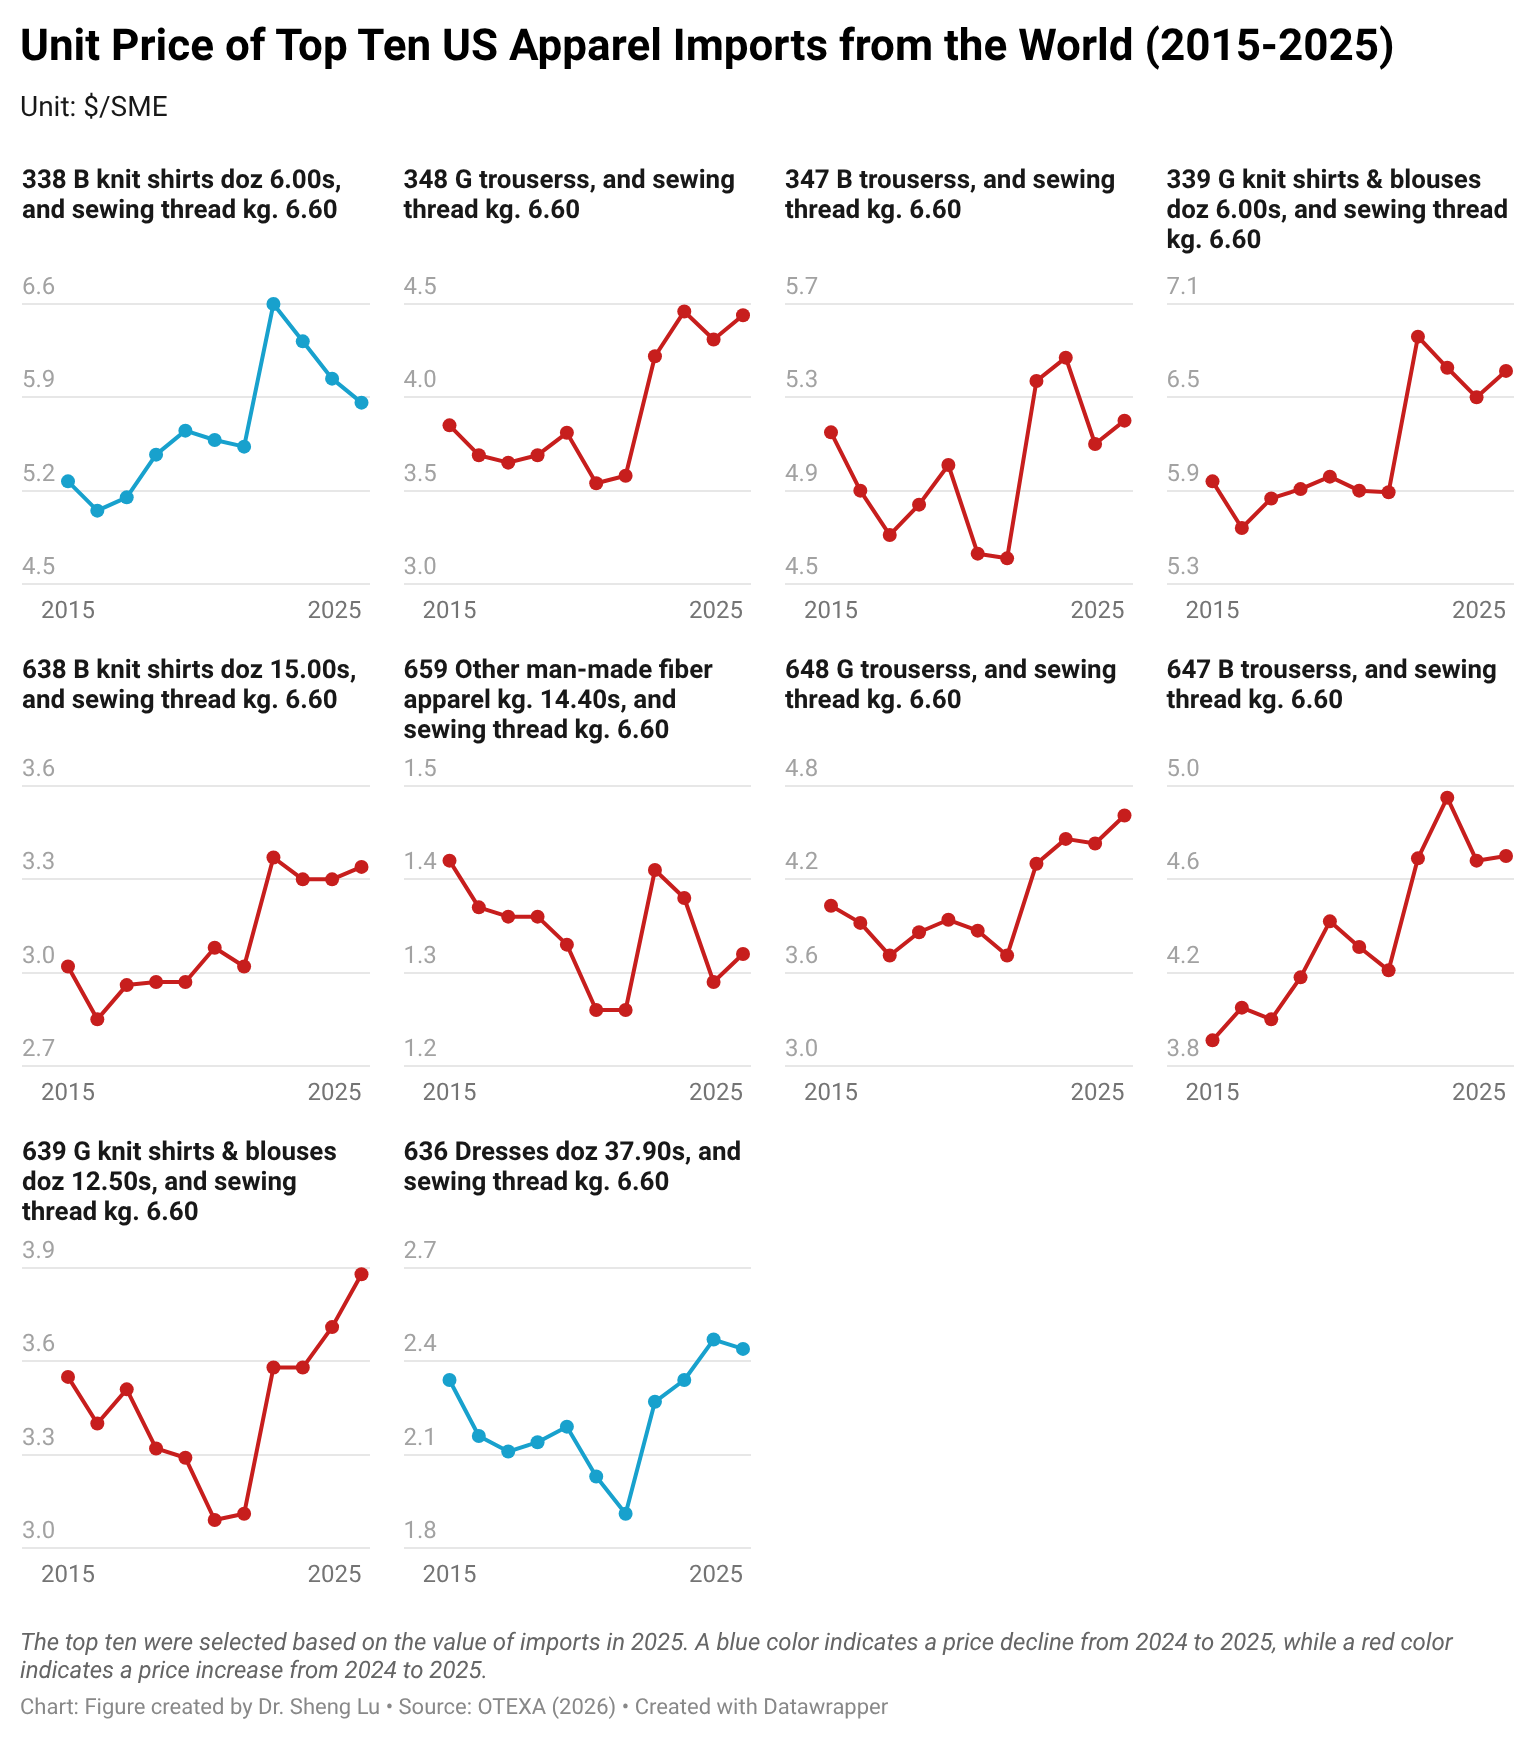
Amid higher tariffs, the unit import price for over half of the apparel import categories increased in 2025. Specifically, of the 106 apparel types categorized by OTEXA, 55 types (or 51.9%) saw a price increase between 2024 and 2025. This includes 22 categories (or 20.8%) with a price increase of more than 10 percent. Likewise, among the top ten largest apparel import categories by value in 2025, eight (80%) experienced price increases between 2024 and 2025, with an average increase of 2.5%.  This result suggests that the upward price pressure was embedded in core, high-volume products rather than niche items. Particularly, as fashion companies navigate rising tariffs and policy uncertainty through more frequent adjustments to their original shipping schedules, it could increase their production and logistics costs more than usual. [Click here for detailed top ten U.S. apparel imports price data]

Impact on clothing retail price

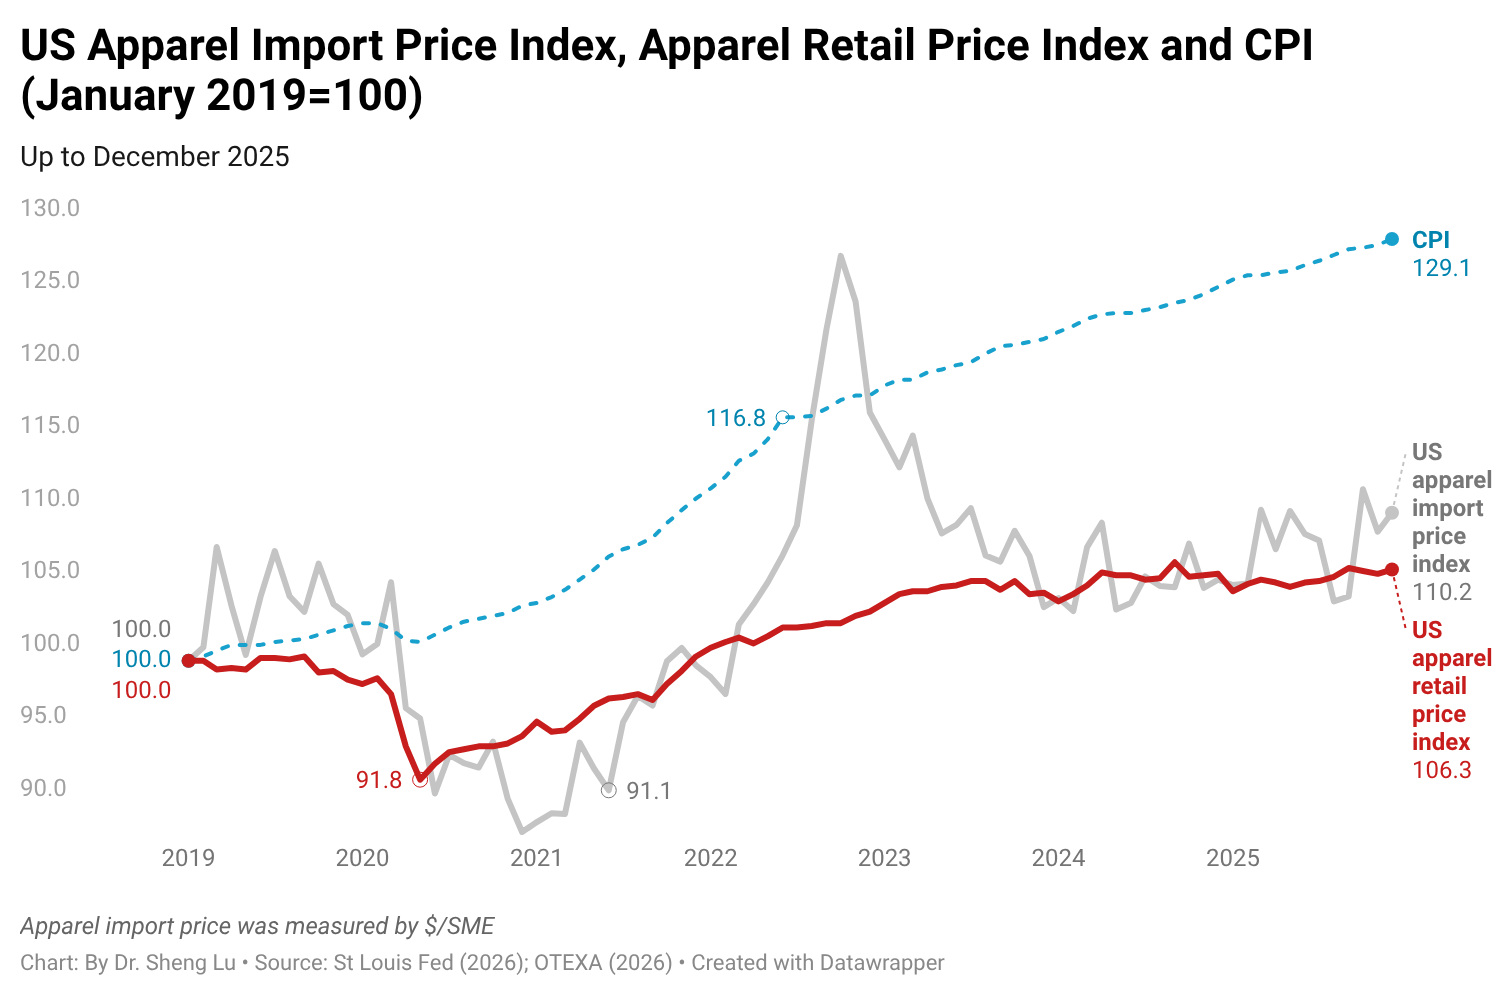
While the average U.S. apparel tariff rate rose from 14.7% in December 2024 to 31.5% in December 2025, the average U.S. clothing retail price increased only slightly by 0.3% during that time. This price rise was also much less than the 2.7% increase in the overall U.S. Consumer Price Index (CPI) during the same period. Since many apparel items are considered discretionary spending, higher inflation may lead consumers to reduce clothing purchases. [Click here for detailed U.S. apparel retail price index and CPI data]

Related, according to the Bureau of Economic Analysis (BEA), apparel accounted for 2.08% of U.S. consumers’ total personal spending in 2025, down from 2.10% in 2023 and 2.23% in 2021. As apparel retailers struggled to increase prices, younger generations, such as Gen Z, have turned to the secondhand clothing market.

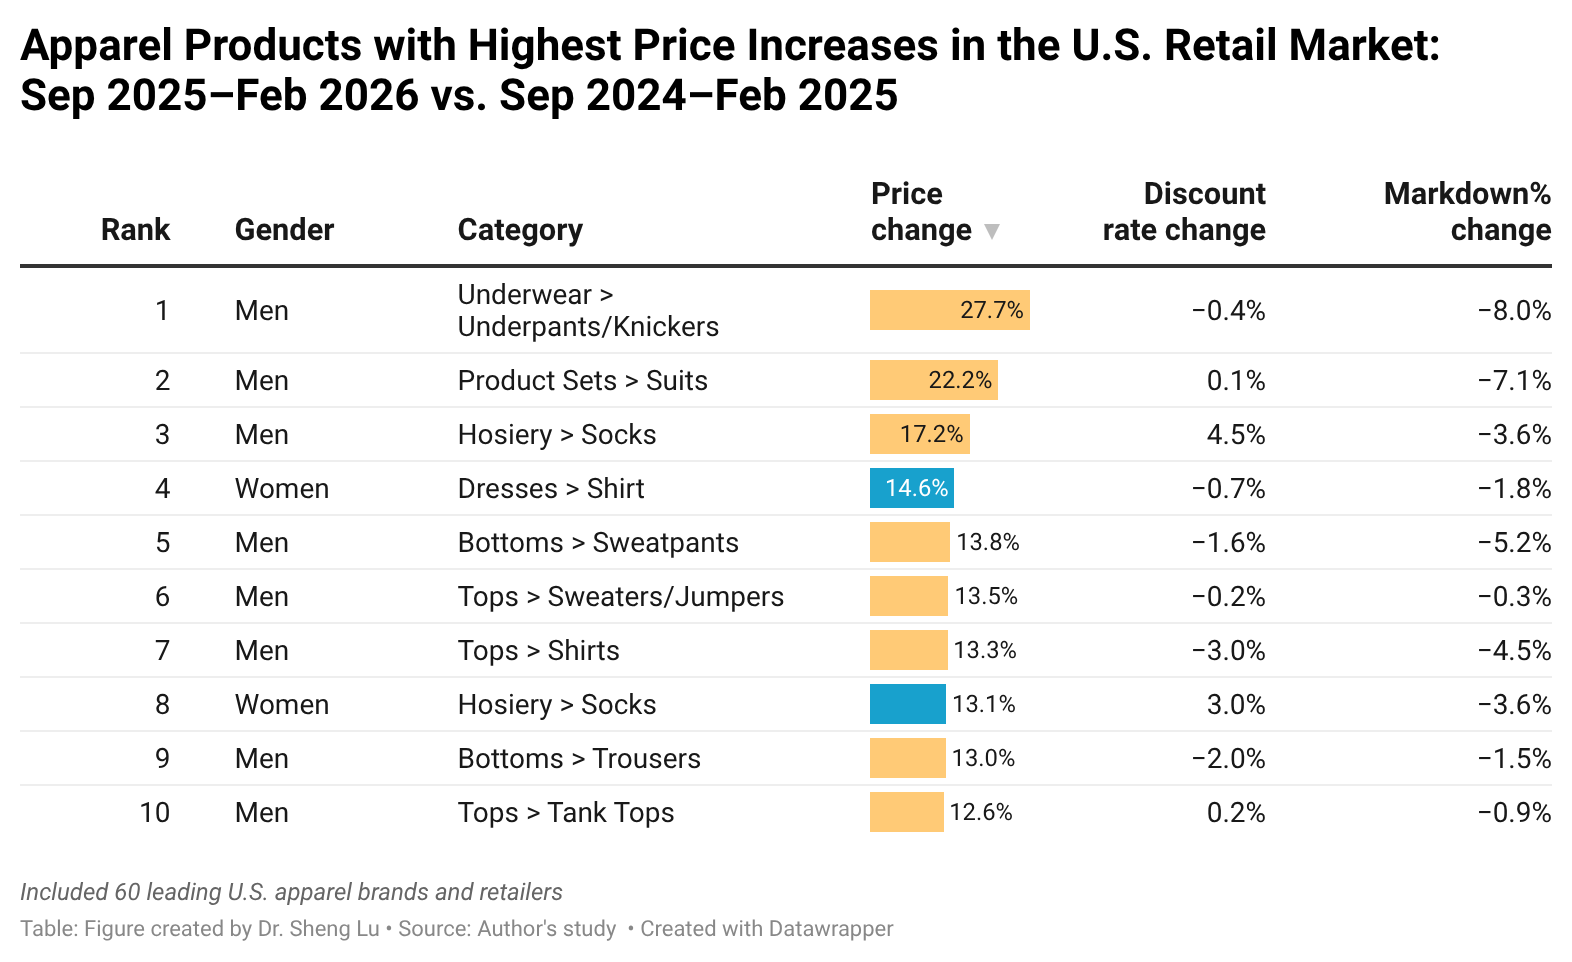
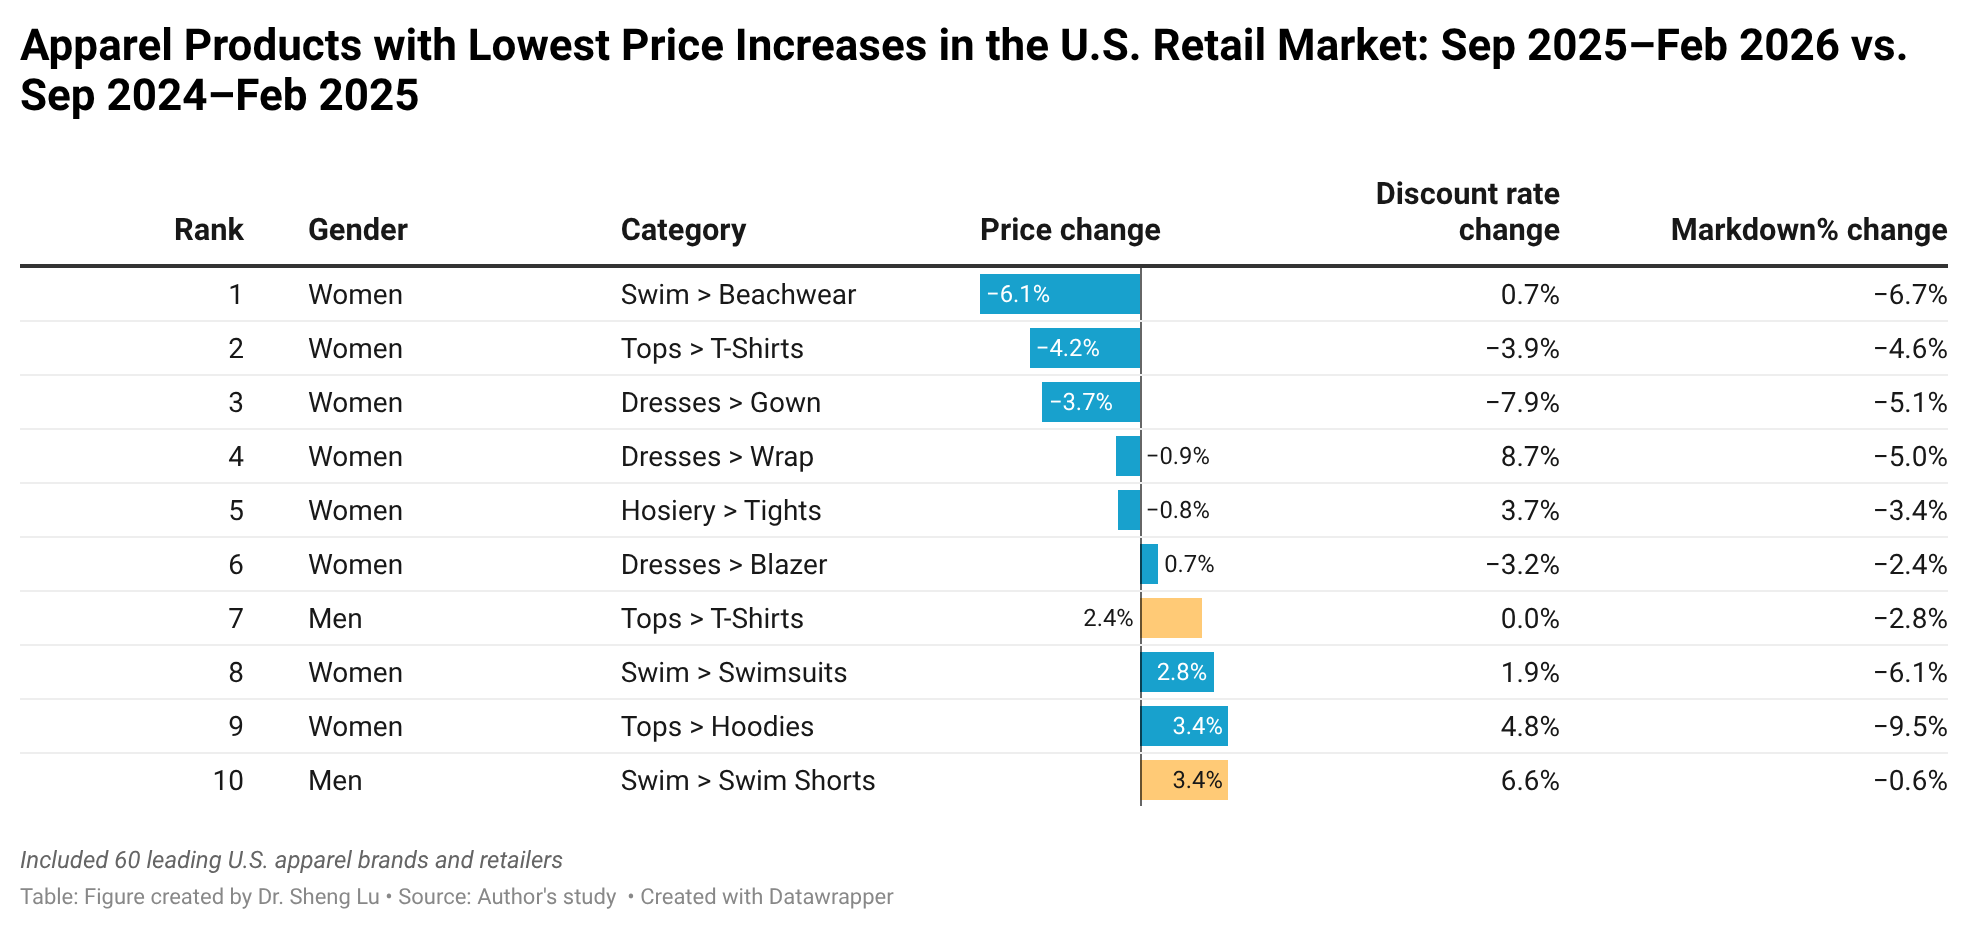
Additionally, data collected from industry sources show that the average retail price for necessities (e.g., men’s underwear) experienced the highest increase during September 2025 and February 2026 compared with the same period a year earlier (i.e., September 2024 and February 2025). In comparison, discretionary spending items such as women’s swimwear and dresses, as well as products with near-shoring opportunity (i.e., T-shirts), experienced the smallest increase over the same period.

Impact on fiber usage and sourcing base

The U.S. tariff rates not only vary by sourcing origin but also by fiber composition. Generally, apparel made with cotton fibers will face a lower tariff rate (i.e., around 8-16% Most-favored-Nation, MFN tariff rates) than apparel made only from man-made fibers (i.e., around 16-32% MFN tariff rates).

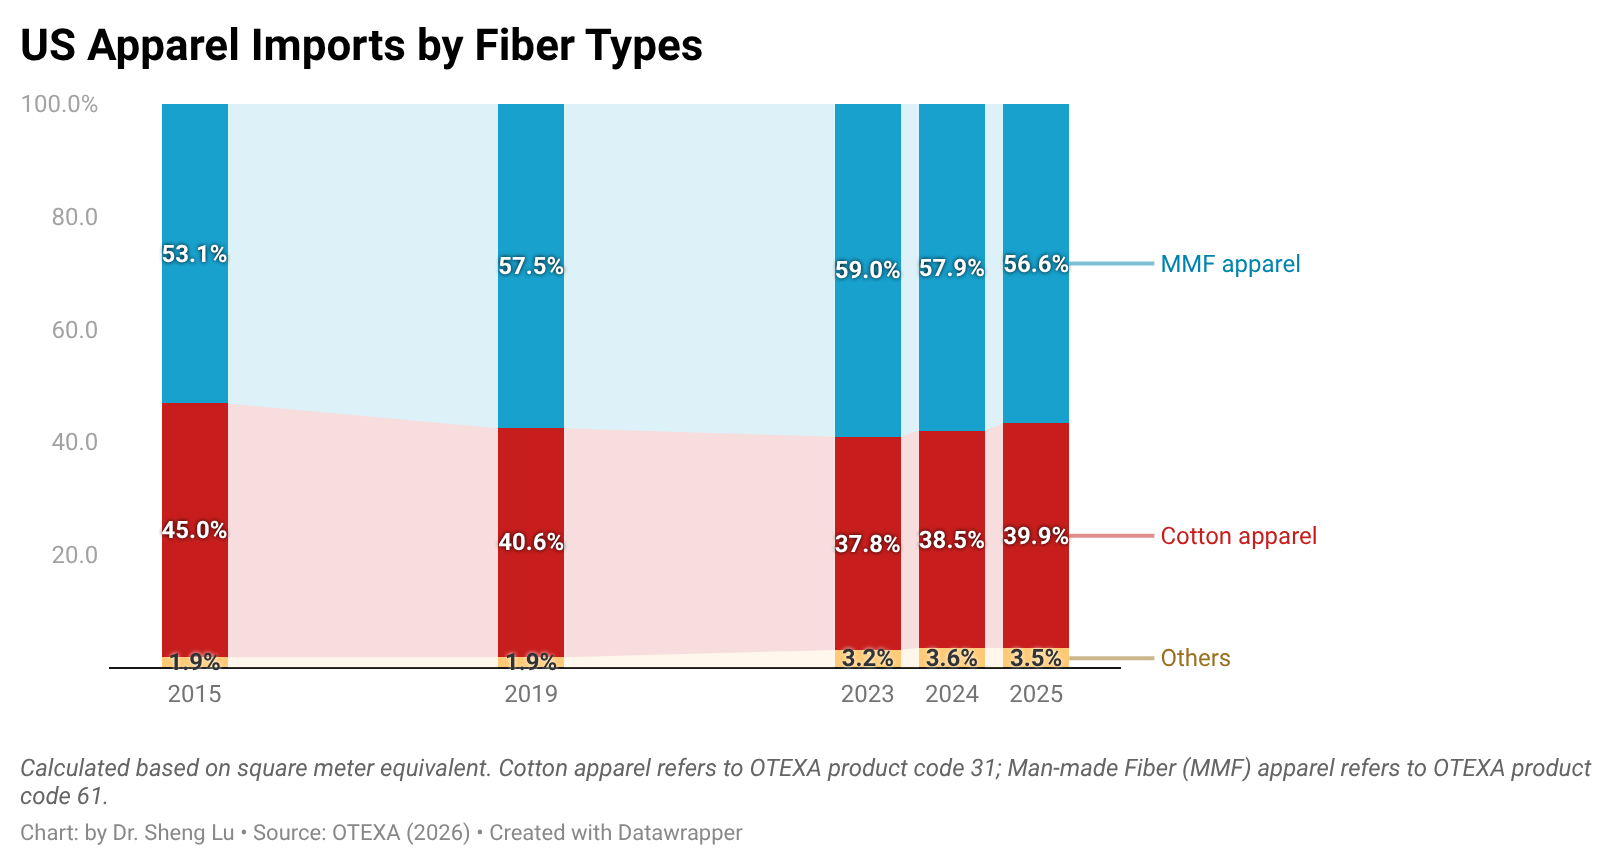
As U.S. fashion companies leverage “tariff engineering” to mitigate the import duty increase, U.S. apparel imports in 2025 included more cotton apparel and fewer of those made from man-made fiber (MMF). Specifically, measured by quantity, cotton apparel (OTEXA category 31) accounted for 39.9% of total US apparel imports in 2025, higher than 38.5% in 2024 and 37.8% in 2023. In comparison, man-made fiber (MMF) apparel accounted for 56.6% of total U.S. apparel imports in 2025, a noticeable decline from 57.9% in 2024 and 59% in 2023. [Click here for detailed U.S. apparel imports by fiber content data]

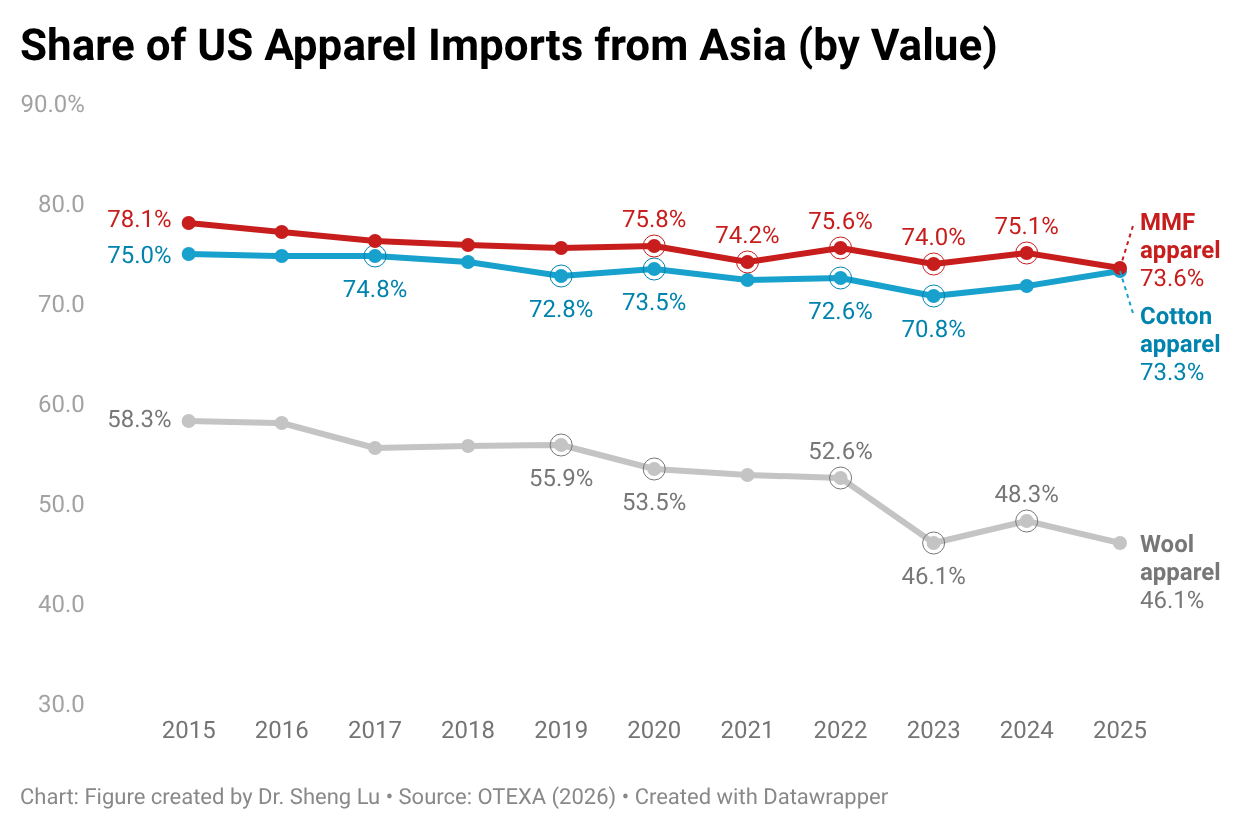
Furthermore, while Asian countries had demonstrated greater competitiveness in man-made fiber (MMF) clothing, higher tariffs on such products in 2025 led U.S. fashion companies to source fewer MMF clothing from Asia. Notably, in value terms, 73.6% of U.S. MMF clothing came from Asia in 2025, a noticeable decline from 75.1% a year earlier. In comparison, 73.1% of U.S. cotton apparel imports came from Asia in 2025, up from 71.8% in 2024. [Click here for Asia market share data]

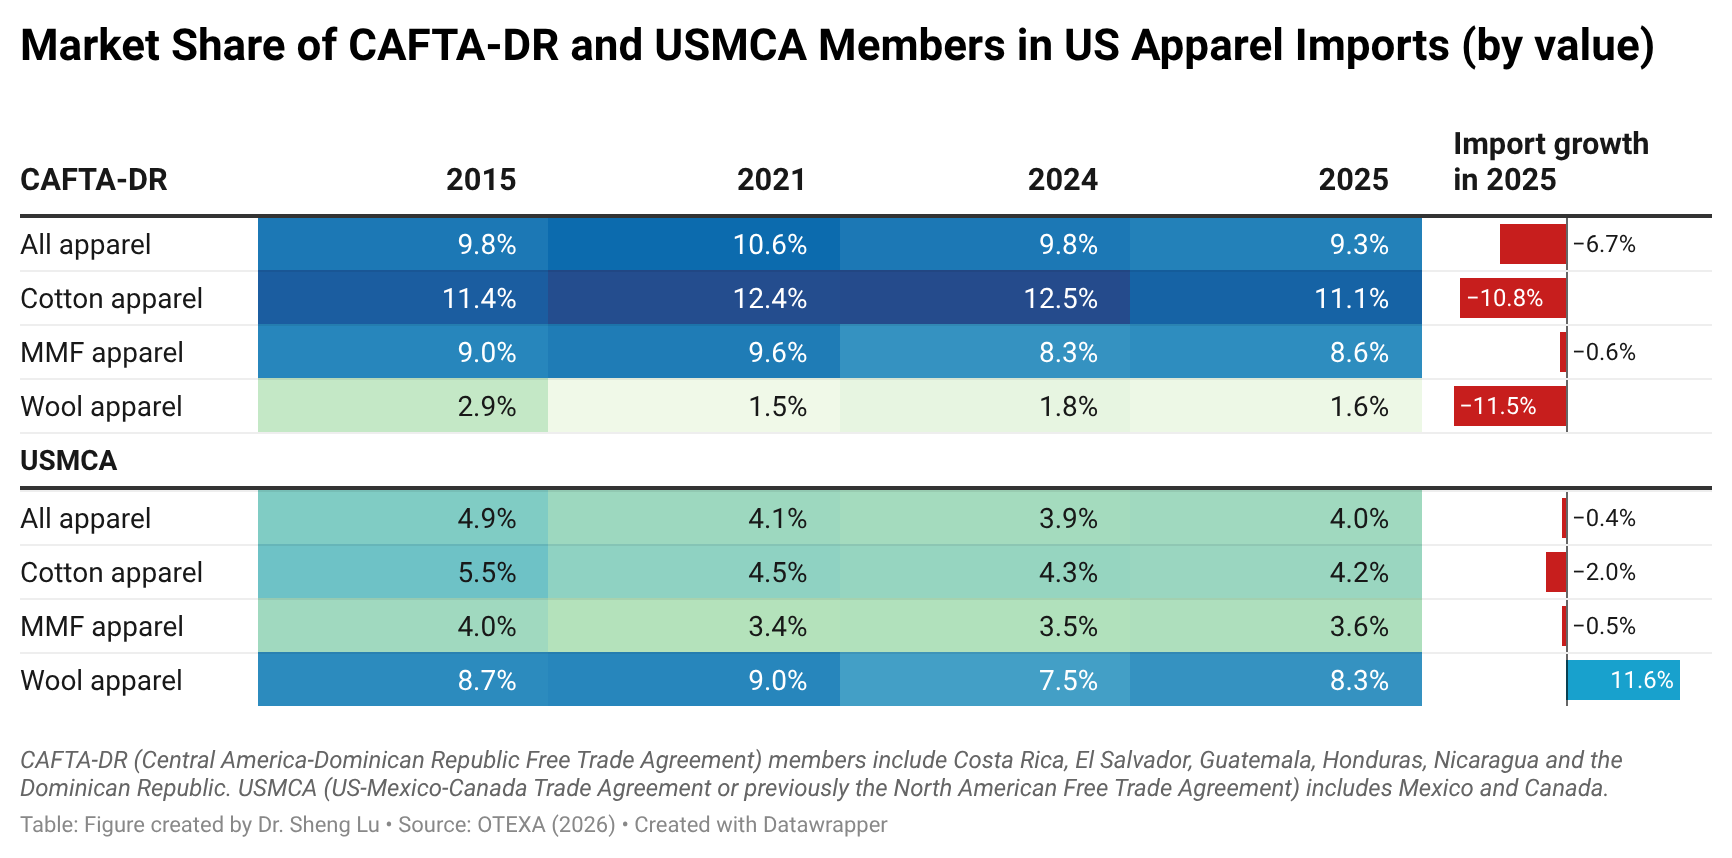
In comparison, it is interesting to note that while CAFTA-DR and USMCA members are perceived as more competitive in making and exporting cotton apparel products, due to tariff advantages, U.S. fashion companies import more man-made fiber (MMF) apparel from the regions in 2025. The same trend applied to wool apparel imports from the USMCA, which grew by 11.6%.  These results suggest that if the tariff gap between U.S. apparel imports from CAFTA-DR and USMCA members and those from Asian countries continues in 2026, it may further incentivize U.S. fashion companies to explore additional MMF apparel sourcing opportunities in the Western Hemisphere. This incentive could be reinforced by the fact that, since February 2026, apparel imports from many Asian suppliers have been subject to the new Section 122 tariffs, while qualifying apparel products from CAFTA-DR and USMCA remain exempt. It may also represent a historic opportunity to expand investment in MMF textile manufacturing in CAFTA-DR and USMCA countries, thereby increasing regional production capacity and diversifying product offerings. [Click here for CAFTA-DR and USMCA market share data]

Impact on Free Trade Agreement utilization

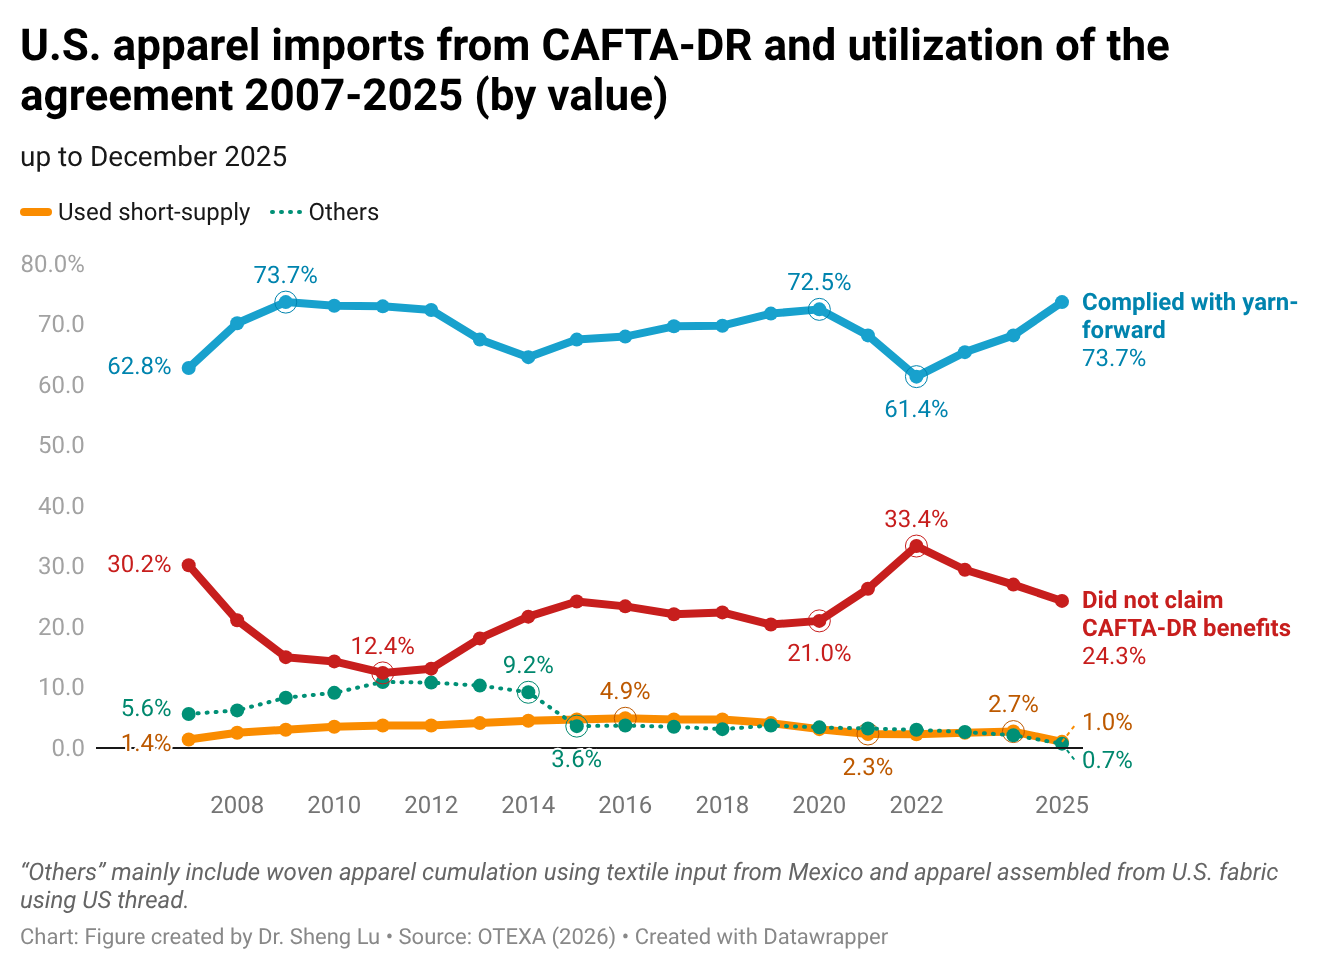
While there is no clear evidence from trade data showing that U.S. fashion companies expanded near-shoring from the Western Hemisphere in 2025, as a silver lining, the utilization of free trade agreements significantly improved. Specifically, measured in value, about 75.7% of U.S. apparel imports from members of the Dominican Republic-Central America Free Trade Agreement (CAFTA-DR) claimed duty-free benefits under the agreement, up from 73.0% in 2024 and 70.5% in 2023. Improved CAFTA-DR utilization in 2025 was driven by a higher volume of imports that met the yarn-forward rules of origin (i.e., up 1.5%). However, the utilization rate of the agreement’s short-supply mechanism decreased from 2.7% to 1.2%, despite more products being added to the list. [Click here for CAFTA-DR utilization data]

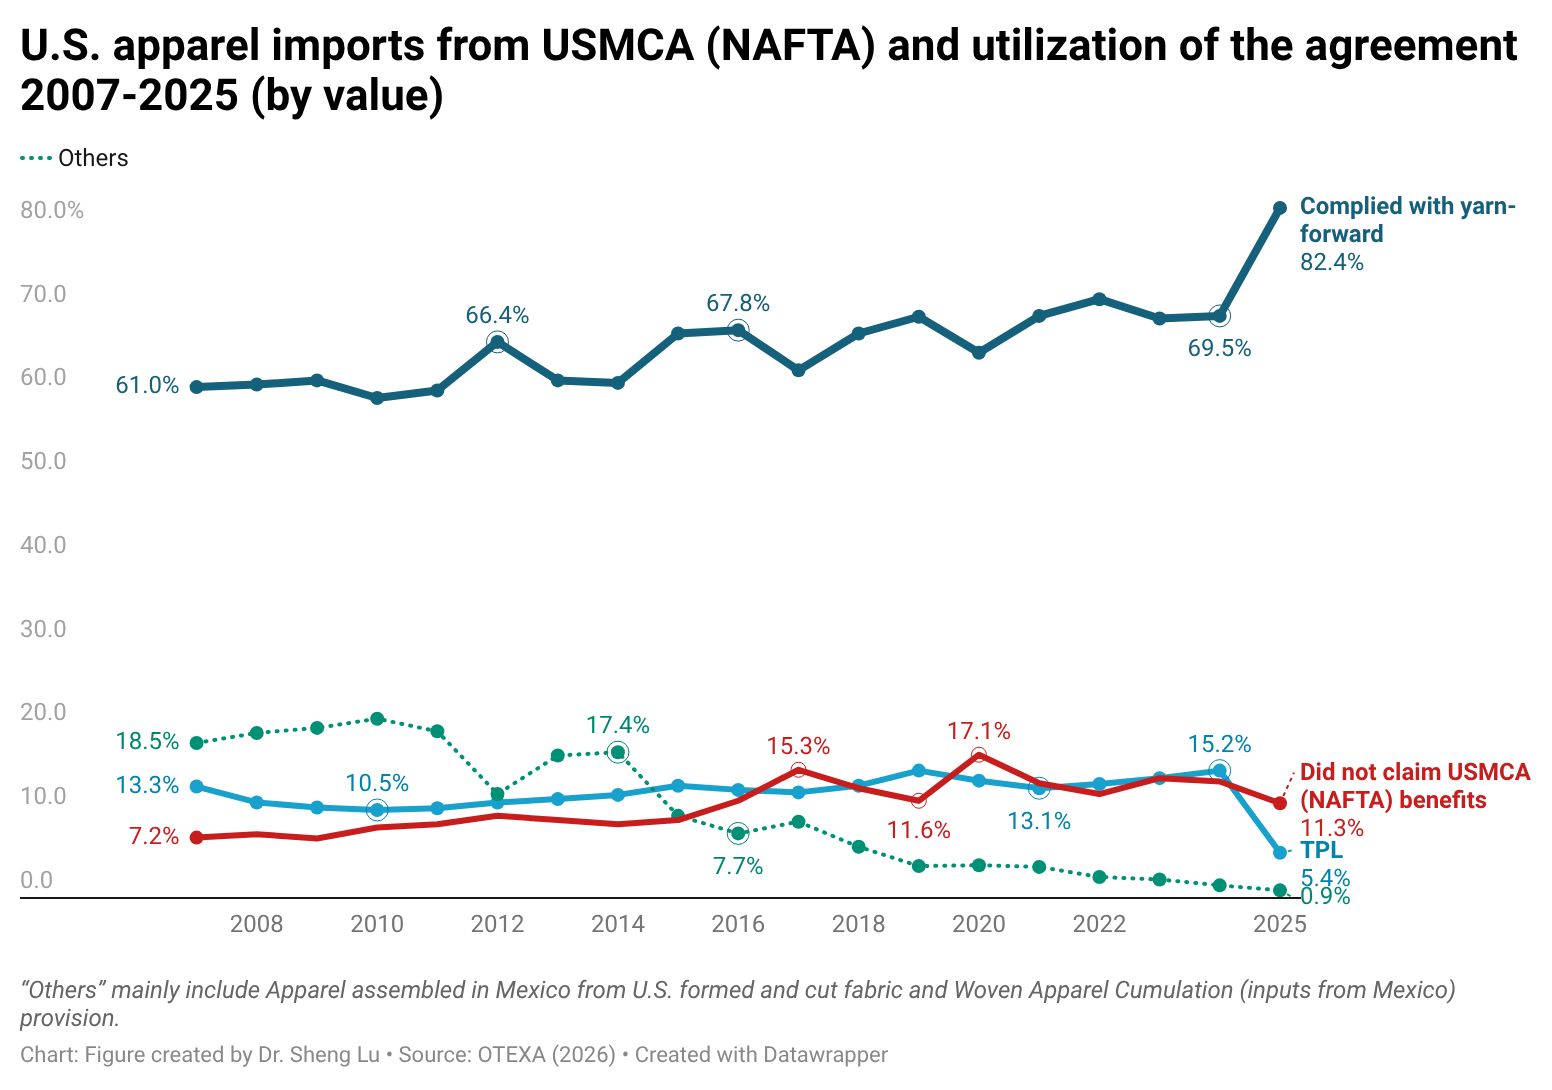
Similarly, in value, about 88.7% of U.S. apparel imports from Mexico and Canada claimed duty-free benefits under the U.S.-Mexico-Canada Agreement (USMCA), up from 86.1% in 2024 and 85.7% in 2023. Notably, in the past, only around 20% of U.S. apparel imports from Canada met the yarn-forward rules of origin; however, this percentage increased dramatically to 69.9% in 2025. Since March 2025, USMCA-qualifying products have been exempt from the “reciprocal tariffs” imposed by the Trump administration, which likely encouraged more U.S. apparel imports from Canada to take advantage of the rules. [Click here for USMCA utilization data]

By Sheng Lu

Read the full paper: Lu, Sheng (2026). US Apparel Import and Sourcing Patterns in 2025. Global Textile Academy, International Trade Centre (ITC). Geneva, Switzerland

[Comment for this post is closed]