U.S. Textile and Apparel Industry Responds to Trump’s Tariff Announcement against China

FOREIGN201708211521000183597989940

On June 15, 2018, the Trump Administration announced to impose a 25% punitive tariff on a list of Chinese goods based on the results of its Section 301 investigation, which targeted against China’s unfair trade practices related to the forced transfer of American technology and intellectual property. The additional duty will first apply to 818 lines of products on July 6, 2018, which cover approximately $34 billion worth of imports from China. Office of the U.S. Trade Representative (USTR) said it would issue a final determination on the second set of 284 proposed tariff lines, which cover approximately $16 billion worth of imports from China shortly. The total 1,102 tariff lines targeted by USTR generally focuses on products from industrial sectors that contribute to or benefit from the “Made in China 2025” industrial policy, which include industries such as aerospace, information and communications technology, robotics, industrial machinery, new materials, and automobiles.

In response to the U.S. action, China’s Ministry of Commerce (MOFCOM) quickly announced its proposed countermeasures, including a 25% punitive tariff on approximately $34 billion worth of U.S. soybean, autos, and fruits effective July 6, 2018. China is also ready to impose the punitive tariff on another list of products, which cover approximately $16 billion worth of medical device, chemicals and energy imports from the United States.

The U.S. textile and apparel industry keeps a close watch on the U.S.-China trade dispute since as much as 36% of U.S. textile and apparel imports come from China. In an announcement released on June 16, 2018, the American Apparel and Footwear Association (AAFA) called a victory that no textile and apparel products are subject to the punitive tariff proposed by USTR. The June 15 USTR list also removes the majority of the textile machinery initially on the retaliation product list back in April 2018. However, U.S. fashion brands and apparel retailers remain deeply concerned about Trump’s tariff action and its potential negative economic impacts on the apparel sector.

In contrast, the U.S. textile industry, represented by the National Council of Textile Organizations (NCTO) praised the Trump administration’s tariff announcement. NCTO also called on the Trump administration to include finished textile and apparel products on any future lists of imports from China to be made subject to Section 301 tariffs.  Not surprisingly, NCTO’s proposal is opposed strongly by AAFA and the U.S. Fashion Industry Association, representing U.S. fashion brands and apparel retailers. As argued by USFIA, the U.S. tariff rates on apparel and fashion products are already the highest among manufactured goods, reaching 32 percent for man-made fiber apparel and 67 percent for footwear. Any additional tariff would constitute a huge, regressive tax increase and have a negative impact on the American jobs.

Appendix: Timeline of U.S. Section 301 Investigation against China

June 15, 2018: The Trump Administration announced to impose a 25% punitive tariff on a list of Chinese goods based on the results of its section 301 investigation

June 4, 2018: Secretary of Commerce Wilbur Ross concluded his two-day trade negotiation with China in Beijing. A White House statement said “the meetings focused on reducing the United States’ trade deficit by facilitating the supply of agricultural and energy products to meet China’s growing consumption needs, which will help support growth and employment in the United States. The United States officials conveyed President Donald J. Trump’s clear goal for achieving a fair trading relationship with China.” While the announcement didn’t mention the next round, it says that the delegation will “receive guidance on the path forward.”

May 29, 2018: President Trump suddenly announced that the United States will impose a 25 percent tariff on $50 billion of goods imported from China containing industrially significant technology, including those related to the “Made in China 2025” program.  The final list of covered imports will be announced by June 15, 2018. The announcement also said that the U.S. Trade Representative Office (USTR) will continue WTO dispute settlement against China originally initiated in March to address China’s discriminatory technology licensing requirements. Additionally, the United States will implement specific investment restrictions and enhanced export controls for Chinese persons and entities related to the acquisition of industrially significant technology. The list of restrictions and controls will be announced by June 30, 2018.

May 19, 2018: A joint statement released by the White House said that the United States and China had led to an agreement for China to buy more goods and services, including “meaningful increases in U.S. agriculture and energy exports.” The statement also said that both sides attach importance to intellectual property protections, agreed to encourage two-way investment and to strive to create a fair, level playing field for competition, and agreed to engage at high levels on trade and investment issues. Additionally, the statement said that the United States would send a team to China to work out the details of the agreement. However, the statement did not contain a specific target for reducing the $375 billion trade deficits.

April 5, 2018: President Trump announced that he has instructed the Office of the U.S. Trade Representative (USTR) to consider $100 billion additional retaliatory tariffs on China, in response to China’s own retaliation against the Section 301 tariffs announced in late March. In a statement released the next day, USTR confirms the proposed new measures. USTR also says that any additional tariffs proposed will be subject to a similar public comment process as the proposed tariffs announced on April 3, 2018. No tariffs will go into effect until the respective process is complete. 

April 3, 2018: USTR released the proposed list of Chinese products to be subject to the retaliatory tariff under the Section 301 action. The proposed list covers approximately 1,300 separate tariff lines and will undergo further review in a public notice and comment process, including a hearing (scheduled at around May 15, 2018). The USTR statement says it will make a final decision on whether to implement the proposed tariff action after the whole process. 

March 26, 2018: USTR filed a WTO case against China’s discriminatory technology licensing requirements (DS542). The US claimed that China’s measures appear to be inconsistent with Articles 3, 28.1(a) and (b) and 28.2 of the Trade-Related Intellectual Property Rights Agreement (TRIPS). As of April 8, 2018, the European Union, Japan, Ukraine and Saudi Arabia have requested to join the dispute as third parties. According to the WTO rule, China shall enter into consultation with the US no later than April 26, 2018. If the dispute is not resolved by May 25, 2018 (i.e., 60 days after the request for consultation), the United States may request a WTO panel. As of June 17, 2018, the case is still in consultations.

March 22, 2018: President Trump announced his decisions on the actions the Administration will take in response to China’s unfair trade practices covered in the USTR Section 301 investigation of China’s Acts, Policies, and Practices Related to Technology Transfer, Intellectual Property, and Innovation. U.S. Trade Representative Robert Lighthizer initiated the investigation in August 2017 at the direction of President Trump. In the Memorandum he signed, President Trump directed the US Trade Representative to level tariffs on about $50 billion worth of Chinese imports. 

January 2018: the U.S. Trade Representative Office submitted its annual report on China’s WTO Compliance to U.S. Congress. The report says that “It seems clear that the United States erred in supporting China’s entry into the WTO on terms that have proven to be ineffective in securing China’s embrace of an open, market-orientated trade regime.”

August 14, 2017: President Trump issued a memorandum directing the USTR to determine if China’s policies regarding IPR theft and forced technology requirements “may be harming American intellectual property rights, innovation, or technology development,” and thus warrant USTR action under Section 301of the 1974 Trade Act.

Related reading: The Section 301 Investigation against China Divides the U.S. Textile Industry and U.S. Fashion Brands and Retailers
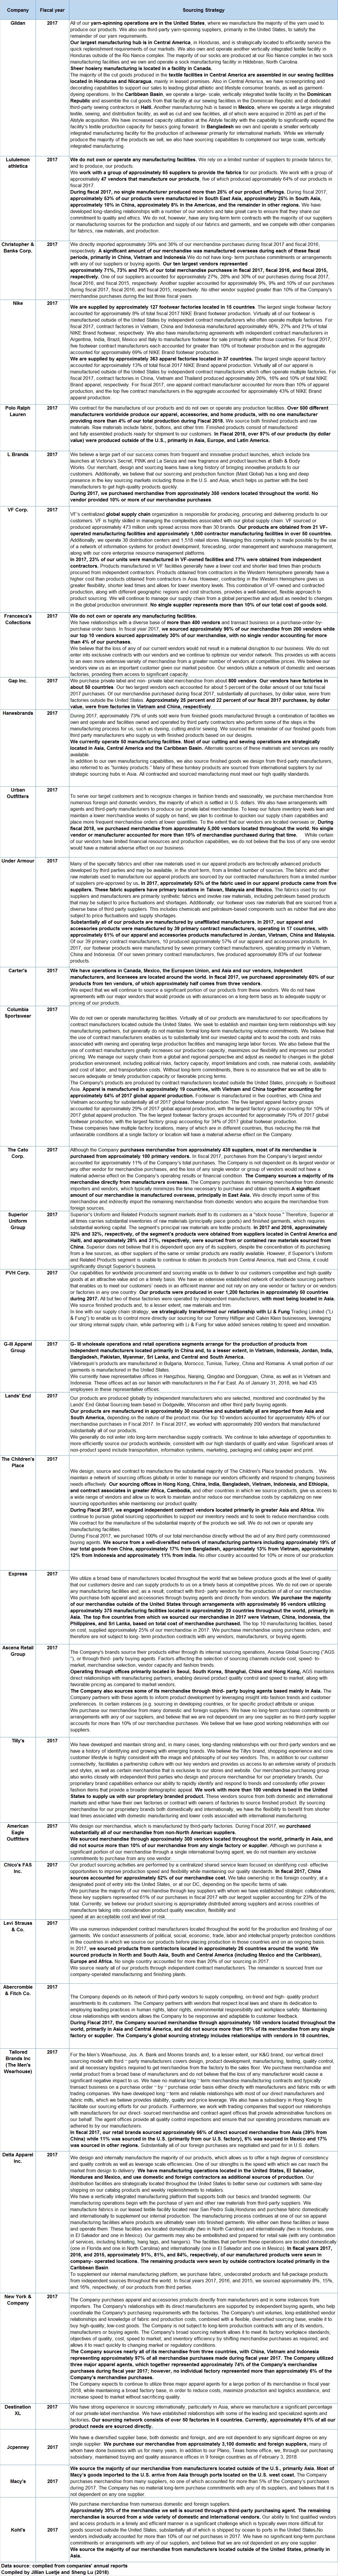
Sourcing Strategy of Leading U.S. Fashion Brands and Apparel Retailers (updated in May 2018)

The Section 301 Investigation against China Divides the U.S. Textile Industry and U.S. Fashion Brands and Retailers
FOREIGN201708211603000328832175771

On April 3, 2018, the U.S. Trade Representative Office (USTR) released the proposed list of Chinese products to be subject to the retaliatory tariff under the Section 301 action. The proposed list covers approximately 1,300 separate tariff lines, including textile machinery. However, textile and apparel (HS chapters 50 to 63) were not on the list.

USTR says it will make a final decision on whether to implement the proposed tariff action after a public hearing process scheduled at around May 15, 2018. Most U.S.-based textile and apparel industry associated have submitted their public comments regarding the section 301 investigation. Because of their respective commercial interests, not surprisingly, the U.S. textile industry favors the retaliatory tariffs on imports from China whereas U.S. fashion brands and retailers oppose the action strongly. Specifically:

National Council of Textile Organizations (NCTO)

  • NCTO applauds the Trump Administration’s formal initiation of a Section 301 case designed to address China’s persistent and highly damaging actions in the area of intellectual property theft. NCTO argues that illegal activity on the part of the government of China has gone on for far too long, at the direct expense of U.S. manufacturers and the loss of millions of U.S. manufacturing jobs.
  • The U.S. textile industry is severely disappointed that the retaliation list published by USTR on April 3 does not contain a single textile or apparel product.
  • NCTO argues that China’s illegal IPR activities have damaged the U.S. textile industry and recommend that textile and apparel products be added to the retaliation list.

The United States Fashion Industry Association (USFIA)

  • USFIA opposes adding apparel (items classifiable under chapters 61 and 62 of the HTSUS) and other fashion products (such as footwear, handbags, and luggage) to the retaliation list against China.
  • USFIA argues that tariffs are NOT the appropriate mechanism to redress the activities outlined in USTR’s report to the White House. Imposing tariffs on imports of fashion products would do nothing to solve the concerns about China’s IP policies and practices outlined in USTR’s Section 301 report.
  • USFIA believes that the best way to address concerns about China’s IPR practices is action at the multilateral level that includes other US trading partners.

American Apparel and Footwear Association (AAFA)

  • AAFA strongly opposes the proposed imposition of tariffs on textile, apparel, and footwear equipment and machinery as this will result in increased costs for AAFA members who are making yarns, fabrics, clothes, and shoes in the United States.
  • AAFA believes that a tariff on textile and apparel products would be a hidden tax on U.S. consumers, particularly since China represents such a large source of U.S. imports of these products.
  • AAFA strongly supports the Trump Administration’s efforts to improve the protection of intellectual property rights in China.

New CRS Report: U.S. Trade with Free Trade Agreement (FTA) Partners

3Key findings:

  • Between 1985 and 2011, the United States entered into 14 free trade agreements (FTAs) with 20 countries. Data from the Census shows that U.S. merchandise trade (or trade in goods) with FTA partner countries represents nearly 70% of all U.S. exports in goods and services, and more than 80% of all U.S. imports of goods and services.
  • In 2016, the United States ran a merchandise trade deficit of -$71.3 billion with the 20 FTA partner countries and a services surplus of $68.9 billion. The share of the U.S. trade deficit with FTA partners, however, has fallen by nearly half over the 2007-2017 period, from 18% to only about 10% of the total -$734.4 billion U.S. merchandise trade deficit.

  • Regarding the economic impact of FTAs on the United States, a study conducted by the U.S. International Trade Commission suggests that bilateral and regional trade agreements increased U.S. aggregate trade by about 3%, but less than 1% for U.S. employment (or 159,300 full-time equivalent employees). Specifically, the study finds that rising imports, due in part to the Agreement on Textiles and Clothing (ATC), accounted for most of the reduction in U.S. employment in the apparel industry between 1998 and 2014.
  • Current trade data treat exports and imports as though the full value of an export was produced domestically and the full value of an import was produced abroad. However, the rapid growth of global value chains and intra-industry trade (importing and exporting goods in the same industry) has significantly increased the amount of trade in intermediate goods in ways that can blur the distinction between domestic and foreign firms and goods. For example, foreign value added accounts for about 11% of the content of U.S. exports in 2010. As a result of the growth in value chains, traditional methods of measuring trade may obscure the actual sources of goods and services and the allocation of resources that are used in producing those goods and services.

  • Trade agreements of the type currently being negotiated by the United States comprise a broad range of issues that could have significant economic effects on trade and commercial relations over the long run between the negotiating parties, particularly for developing and emerging economies. However, the negative effects of international trade and trade agreements, particularly potential job losses and lower wages, often are distributed disproportionately with the effects falling more heavily on some workers and on some firms.

The full report can be downloaded from HERE

Resources for Learning about Cotton: FASH455 Exclusive Interview with Shannon Brady, CottonWorks™ Student Ambassador

IMG_1605

The picture above: Shannon Brady, Junior, UD Fashion Merchandising Major (Fourth one from the left in the front row) visited Cotton Inc together with other Cotton Student Ambassadors.

Question: What is the CottonWorks™ Ambassador program about and what is your role as an ambassador?

The CottonWorks™ ambassador program is a program where students in fashion and apparel related majors get to promote CottonWorks™ on their college campuses. Ambassadors are charged with helping faculty and students understand the resources available through CottonWorks™ as well as promote this resource through social media. This semester there are twelve ambassadors (including myself) from 12 different schools across the country.

My role as an ambassador is to raise awareness about CottonWorks™ on campus as it is a new program here at the University of Delaware. In January of this year, I had the opportunity to visit the Cotton Incorporated Headquarters in Cary, North Carolina. I, along with other CottonWorks™ ambassadors participated in an all-day CottonWorks™ training as well as a tour of the production facilities at Cotton Incorporated. I got to see everything from raw cotton to state-of-the-art laser finished denim. It was a unique experience and such a cool way to see the material I learned about in class come to life. 

Question: Cotton Incorporated recently launched a new CottonWorksTMprogram to help industry professionals and emerging professionals (like our FASH students) know more about cotton. Can you give us an overview of the program, particularly the learning resources related to the sourcing of cotton products?

CottonWorks™ is a free website where students and professionals can access a multitude of resources about cotton and the fashion and apparel industry.  The site offers many learning resources. Detailed guides are offered on topics such as sourcing and manufacturing, retail and marketing, fabric and technology, fashion and trend, and sustainability. These topics really apply to the fashion curriculum at UD. Additionally, the site offers a mobile-friendly textile encyclopedia where students can look up any textile related word anytime, anywhere.

However, the site offers more than just learning resources. CottonWorks™ is a great supplemental learning tool, but the site also offers emerging professionals ways to get engaged with their industry. Free webinars and workshops are offered through the website and are a great way to engage with industry professionals and learn about the issues pressing the industry right now. Their next webinar is on Tuesday 24 April 2018 registration is open on the CottonWorks™ website, and the topic of discussion is Cotton’s Biodegradability in Aquatic Environments.

Particularly regarding learning resources on sourcing cotton products, the sources and manufacturing topic on the website offers dozens of guides all kinds of cotton products, ranging from denim to cotton nonwovens.

Last but not the least, the Executive Cotton Update and Monthly Economic Letter, both posted every month at cottonworks.com/news are great resources for students and industry professionals interested in knowing what is happening in the U.S. and world cotton industry.

Question: Developing a sustainable supply chain is critical for the textile and apparel industry. So how is cotton related to sustainability? What are the facts important to know?

Cotton Incorporated is committed to being at the forefront of cotton sustainability, and the CottonWorks™ site offers many resources on how cotton is related to sustainability, including guides on responsible cotton production and manufacturing because sustainability happens throughout the lifecycle of cotton.

Cotton is a natural fiber, unlike some manmade fibers such as polyester it can biodegrade. If you log on to CottonWorks™ website you can view a recap of their webinar last month that went in depth about cotton’s biodegradability in soil and septic environments.

Additionally, CottonWorks™ has information on campaigns such as Cotton LEADS™ and Blue Jeans Go Green™ to promote the sustainability of cotton. Cotton LEADS™ is a joint program with Australia and the United States that supports a reliable and responsible cotton supply chain through five core principles of sustainability, use of best practices and traceability in the supply chain. Blue Jeans Go Green™ initiative collects denim sent to landfills and recycles it in partnership with Bonded Logic Inc. You can learn more about both these initiatives on the CottonWorks™ site at cottonworks.com/topics/sustainability.

Question: What are the opportunities for our FASH and UD students to get involved with CottonWorks™ and learn more about cotton?

Students can get started today! By registering for a free account on cottonworks.com, they have access to all of the amazing resources I touched on and many more. Additionally, they can follow @cotton_works on Instagram and Twitter to learn more about cotton and get cotton inspiration for their projects. 

I will also be hosting a tabling event where students can learn more about these resources, talk to me, and win free food and prizes on Thursday 19 April 2018 in Perkins! There will be more tabling events in the future that I will be posting about in my social media as well.

This slideshow requires JavaScript.

Regional Textile and Apparel Supply Chains–Questions from FASH455

References and tables_Page_1

NAFTA and Textile and Apparel Rules of Origin

#1 How do rules of origin (RoO) and free trade agreement (FTA) regulations affect speed to market in apparel sourcing? Do countries who are part of an FTA find it to be easier to get to market in a shorter amount of time if they are working with other FTA members? Or could RoO slow down the production process because producers have to be more careful about compliance with the complicated RoO?

#2 Why or why not the “yarn forward” rules of origin remains an effective way to promote textile and apparel production in the Western-Hemisphere?  What other options are available to improve the competitiveness of the Western-Hemisphere textile and apparel supply chain?

#3 What would happen to the Western-Hemisphere textile and apparel supply chain should NAFTA no longer exist?

#4 Should NAFTA be responsible for the loss of US apparel manufacturing jobs? Any hard evidence?

#5 If you were U.S. trade negotiators, what would you do with TPL in NAFTA given the competing views from the U.S. textile industry and U.S. fashion brands and retailers?

The Outlook of “Factory-Asia”

#6 From the perspective of the U.S. textile and apparel industry, is it a good idea for the United States to reach free trade agreement (FTA) with Asian countries? If so, what countries should be included in the new FTA? If not, why?

#7 How can U.S. companies get involved in the Asia-based textile and apparel supply chain?

#8 Why or why not is the “Flying geese model” unique to Asia? Can the model be replicated in America too?

(Welcome to join our online discussion. Please mention the question number in your reply)

Competition in the U.S. Apparel Import Market (Updated March 2018)

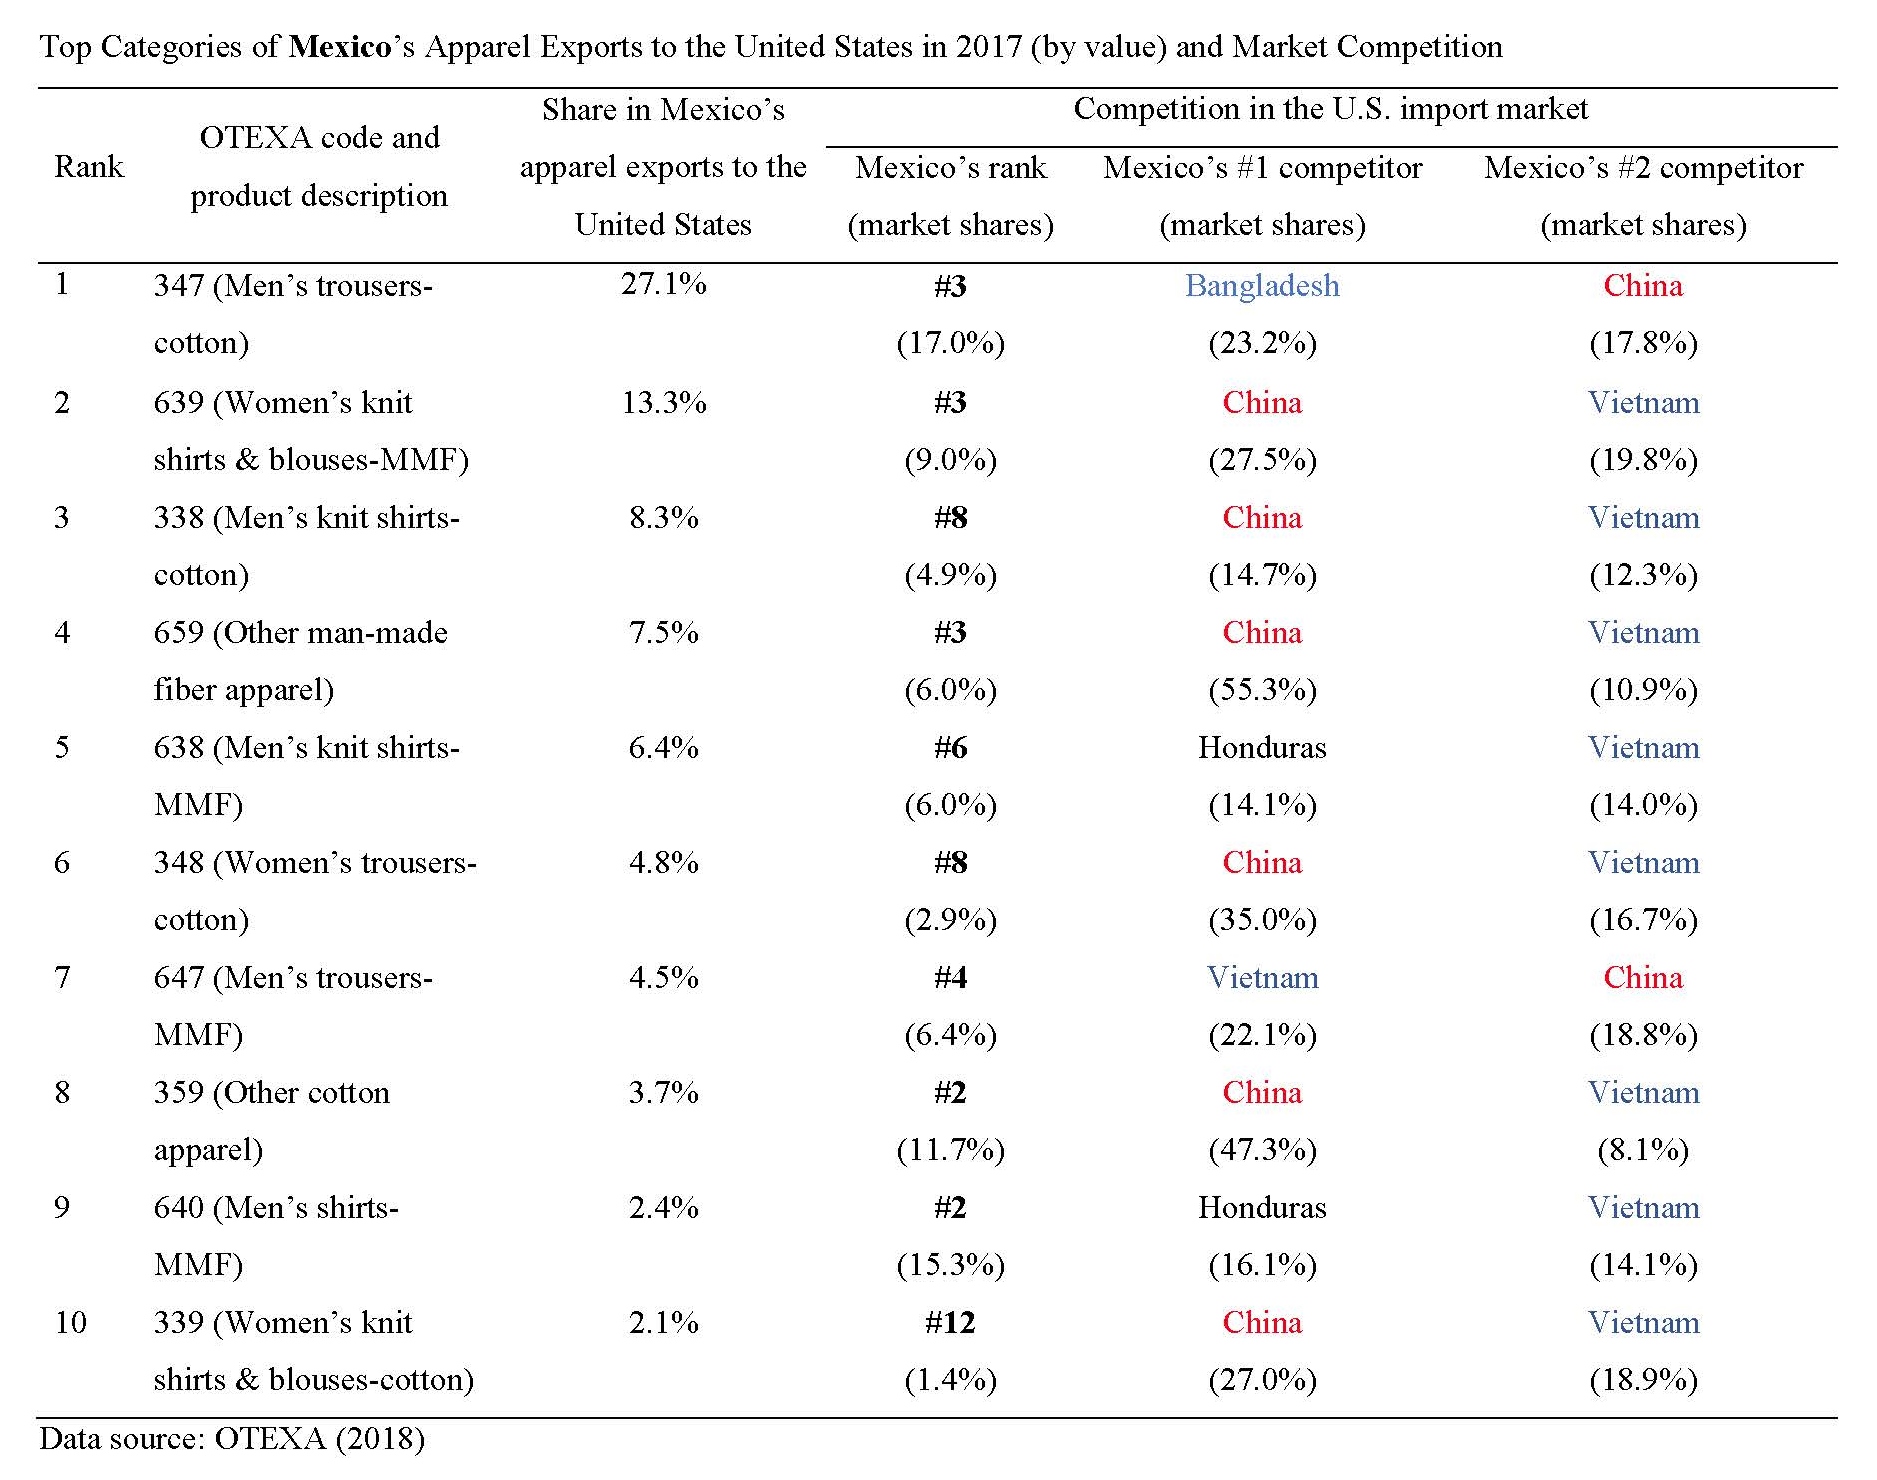
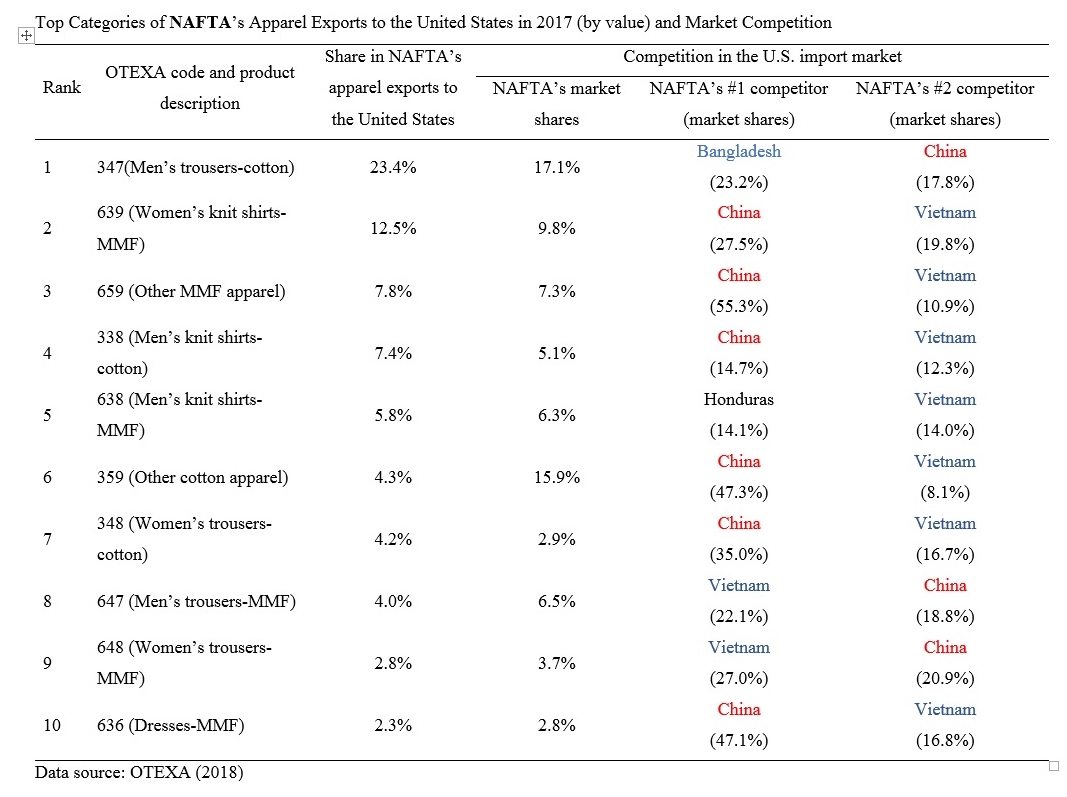
market shares in the US (2017)_Page_2market shares in the US (2017)_Page_3CAFTA-DRNAFTA

Automation Comes to Fashion

Video Discussion Questions:

#1 Why do you agree or disagree with the video that automation will post a significant challenge to garment workers in developing countries such as Bangladesh? How should policymakers react to the challenges?

#2 Can automation be a permanent solution to the social responsibility problem in the garment industry?

#3 In your view, how will automation affect the big landscape of apparel sourcing and the patterns of world textile and apparel trade?

#4 Why or why not do you anticipate a sizable return of apparel manufacturing to the United States if apparel production can be largely automated?

Additional reading: The robots are coming for garment workers. (WSJ, 2018)

Please feel free to share your views and join our online discussion!

US Continues to Lose Textile and Apparel Manufacturing Jobs in 2017

textile

apparel

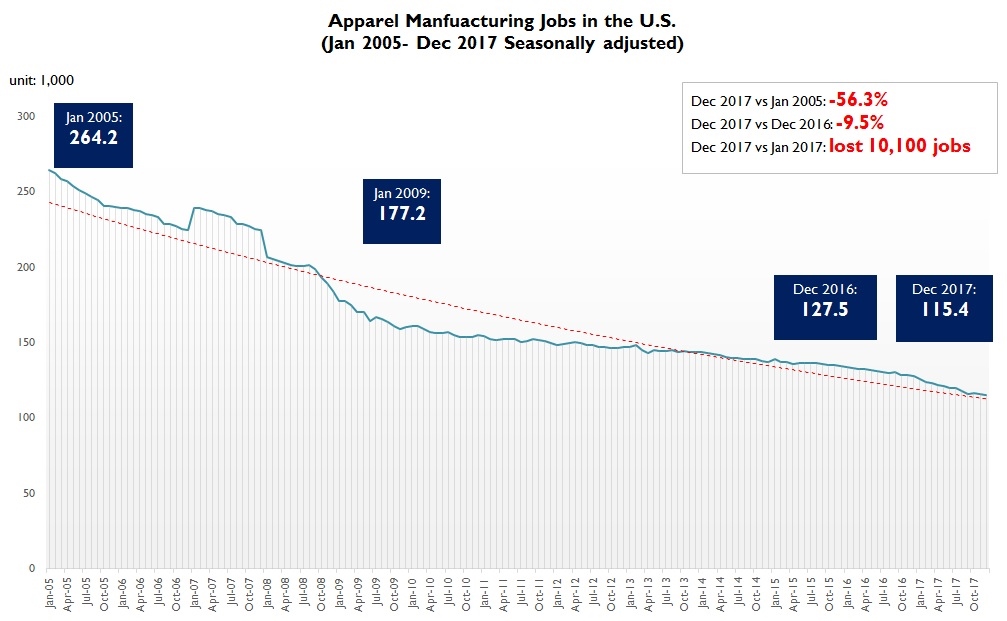
It may disappoint those who are hoping a return of textile and apparel manufacturing jobs in the United States. But according to latest statistics from the Bureau of Labor Statistics (BLS), the U.S. textile industry (NAICS 313 and 314) and apparel industry (NAICS 315) respectively lost another 4,100 and 10,100 jobs in 2017.  Between January 2005 and December 2017, 44.2% and 56.3% of jobs in the U.S. textile and apparel sectors were gone.  

From the academic perspective, a sizable return of textile and apparel manufacturing job in the United States seems to be extremely unlikely given the nature of the U.S. and the global economy in the 21st century.

Notably, the rising import is found NOT a significant factor leading to the decline in employment in the U.S. textile industry (NAICS 313). As estimated by a US International Trade Commission study in 2016, imports were found only contributed 0.4 percent of the total 7.6 percent annual employment decline in the U.S. textile industry between 1998 and 2014. Instead, more job losses in the sector were caused by: 1) the improved productivity as a result of capitalization and automation (around 4.6 percent annually); and (2) the shrinkage of domestic demand for the U.S. made textiles (around 3.5 percent annually).

And consistent with the prediction of classic trade theories, as capital and technology abundant developed country, the United States, not surprisingly, continues to lose its comparative advantage in making labor-intensive apparel. Hypothetically, apparel “Made in the USA” may come back if apparel manufacturing can be substantially automated like textile manufacturing. However, net job creation in the sector as a result of automation is hard to tell. Additionally, most U.S. apparel companies heavily rely on global sourcing and non-manufacturing activities such as branding, marketing, and design today. Few companies still regard “manufacturing” a key competitive advantage or an area of strategic importance to invest in the future.

Related reading: Creating High-Quality Jobs in the U.S. Textile and Apparel Industry (UD Biden Institute)

Outlook 2018: Apparel Industry Issues in the Year Ahead

Outlook 2019: Apparel Industry Issues in the Year Ahead is available 

th.jpg

In January 2018, Just-Style consulted a panel of industry leaders and scholars in its Outlook 2018–Apparel Industry Issues in the Year Ahead management briefing. Below is my contribution to the report. All suggestions and comments are most welcome!

1. What do you see as the biggest challenges – and opportunities – facing the apparel industry in 2018, and why?

One of the biggest opportunities facing the apparel industry in 2018 could be the faster growth of the world economy. According to the International Monetary Fund (IMF), the global growth forecast for 2018 is expected to reach 3.7 percent, about 0.1 percent points higher than 2017 and 0.6 percent points higher than 2016. Notably, the upward economic growth will be broad-based, including the United States, the Euro area, Japan, China, emerging Europe and Russia. Hopefully, the improved growth of the world economy will translate into increased consumer demand for clothing in 2018.

Nevertheless, from the macroeconomic perspective, oversupply will remain a significant challenge facing the apparel industry in 2018. Data from the World Bank and the World Trade Organization (WTO) shows that, while the world population increased by 21.6 percent between 2000 and 2016, the value of clothing exports (inflation-adjusted) surged by 123.5 percent over the same period. Similarly, between 2000 and 2016, the total U.S. population increased by 14.5 percent and the GDP per capita increased by 22.2 percent, but the supply of apparel to the U.S. retail market surged by over 67.8 percent during the same time frame. The problem of oversupply is the root of many challenges faced by apparel companies today, from the intense market competition, pressure of controlling production and sourcing cost, struggling with excessive inventory and deep discounts to balancing sustainability and business growth.

2: What’s happening with sourcing? How is the sourcing landscape likely to shift in 2018, and what can apparel firms and their suppliers do to stay ahead?

The 2017 US Fashion Industry Benchmarking Study, which I conducted in collaboration with the US Fashion Industry Association (USFIA) earlier this year, provides some interesting insights into companies’ latest sourcing strategies and trends. Based on a survey of 34 executives at the leading U.S. fashion companies, we find that:

First, most surveyed companies continue to maintain a relatively diversified sourcing base, with 57.6 percent currently sourcing from 10+ different countries or regions, up from 51.8 percent last year. Larger companies, in general, continue to have a more diversified sourcing base than smaller companies. Further, around 54 percent of respondents expect their sourcing base will become more diversified in the next two years, up from 44 percent in 2016; over 60 percent of those expecting to diversify currently source from more than 10 different countries or regions already. Given the uncertainties in the market and the regulatory environment (such as the Trump Administration’s trade policy agenda), companies may use diversification to mitigate potential market risks and supply chain disruptions due to protectionism.

Second, although U.S. fashion companies continue to seek alternatives to “Made in China” actively, China’s position as top sourcing destination remains unshakable. Many respondents attribute China’s competitiveness to its enormous manufacturing capacity and overall supply chain efficiency. Meanwhile, it is interesting to note that the most common sourcing model is shifting from “China Plus Many” to “China Plus Vietnam Plus Many” (i.e. China typically accounts for 30-50 percent of total sourcing value or volume, 11-30 percent for Vietnam and less than 10 percent for other sourcing destinations). I think this sourcing model will likely to continue in 2018.

Third, social responsibility and sustainability continue to grow in importance in sourcing decisions. In the study, we find that nearly 90 percent of respondents give more weight to sustainability when choosing where to source now than in the past. Around 90 percent of respondents also say they map their supply chains, i.e., keeping records of name, location, and function of suppliers. Notably, more than half of respondents track not only Tier 1 suppliers, suppliers they contract with directly, but also Tier 2 suppliers, i.e., supplier’s suppliers. However, the result also suggests that a more diversified sourcing base makes it more difficult to monitor supply chains closely. Making the apparel supply chain more socially responsible, sustainable and transparent will continue to be a hot topic in 2018.

3: What should apparel firms and their suppliers be doing now if they want to remain competitive further into the future? What will separate the winners from the losers?

I assume many experts will suggest what apparel firms should change to stay competitive into the future. However, the question in my mind is what should companies keep doing regardless of the external business environment? First, I think companies should always strive to understand and impress consumers and control their supply chains. Despite the growing popularity of e-commerce and the adoption of transformative new technologies, the fundamental nature of apparel as a buyer-driven business will remain the same. Second, companies should always leverage their resources and stay “unique,” no matter it means offering differentiated products or value-added services, maintaining exclusive distribution channels or keeping the leadership position in a particular niche market. Third, apparel firms should always follow the principle of “comparative advantage” and smartly define the scope of their core business functions instead of trying to do everything. Additionally, winners will always be those companies that can take advantage of the mega-development trends of the industry and be willing to make long-term and visionary investments, both physical and intangible (such as human talents).

4: What keeps you awake at night? Is there anything else you think the apparel industry should be keeping a close eye on in the year ahead? Do you expect 2018 to be better than 2017, and why?

I think the apparel industry should keep a close eye on the following issues in 2018:

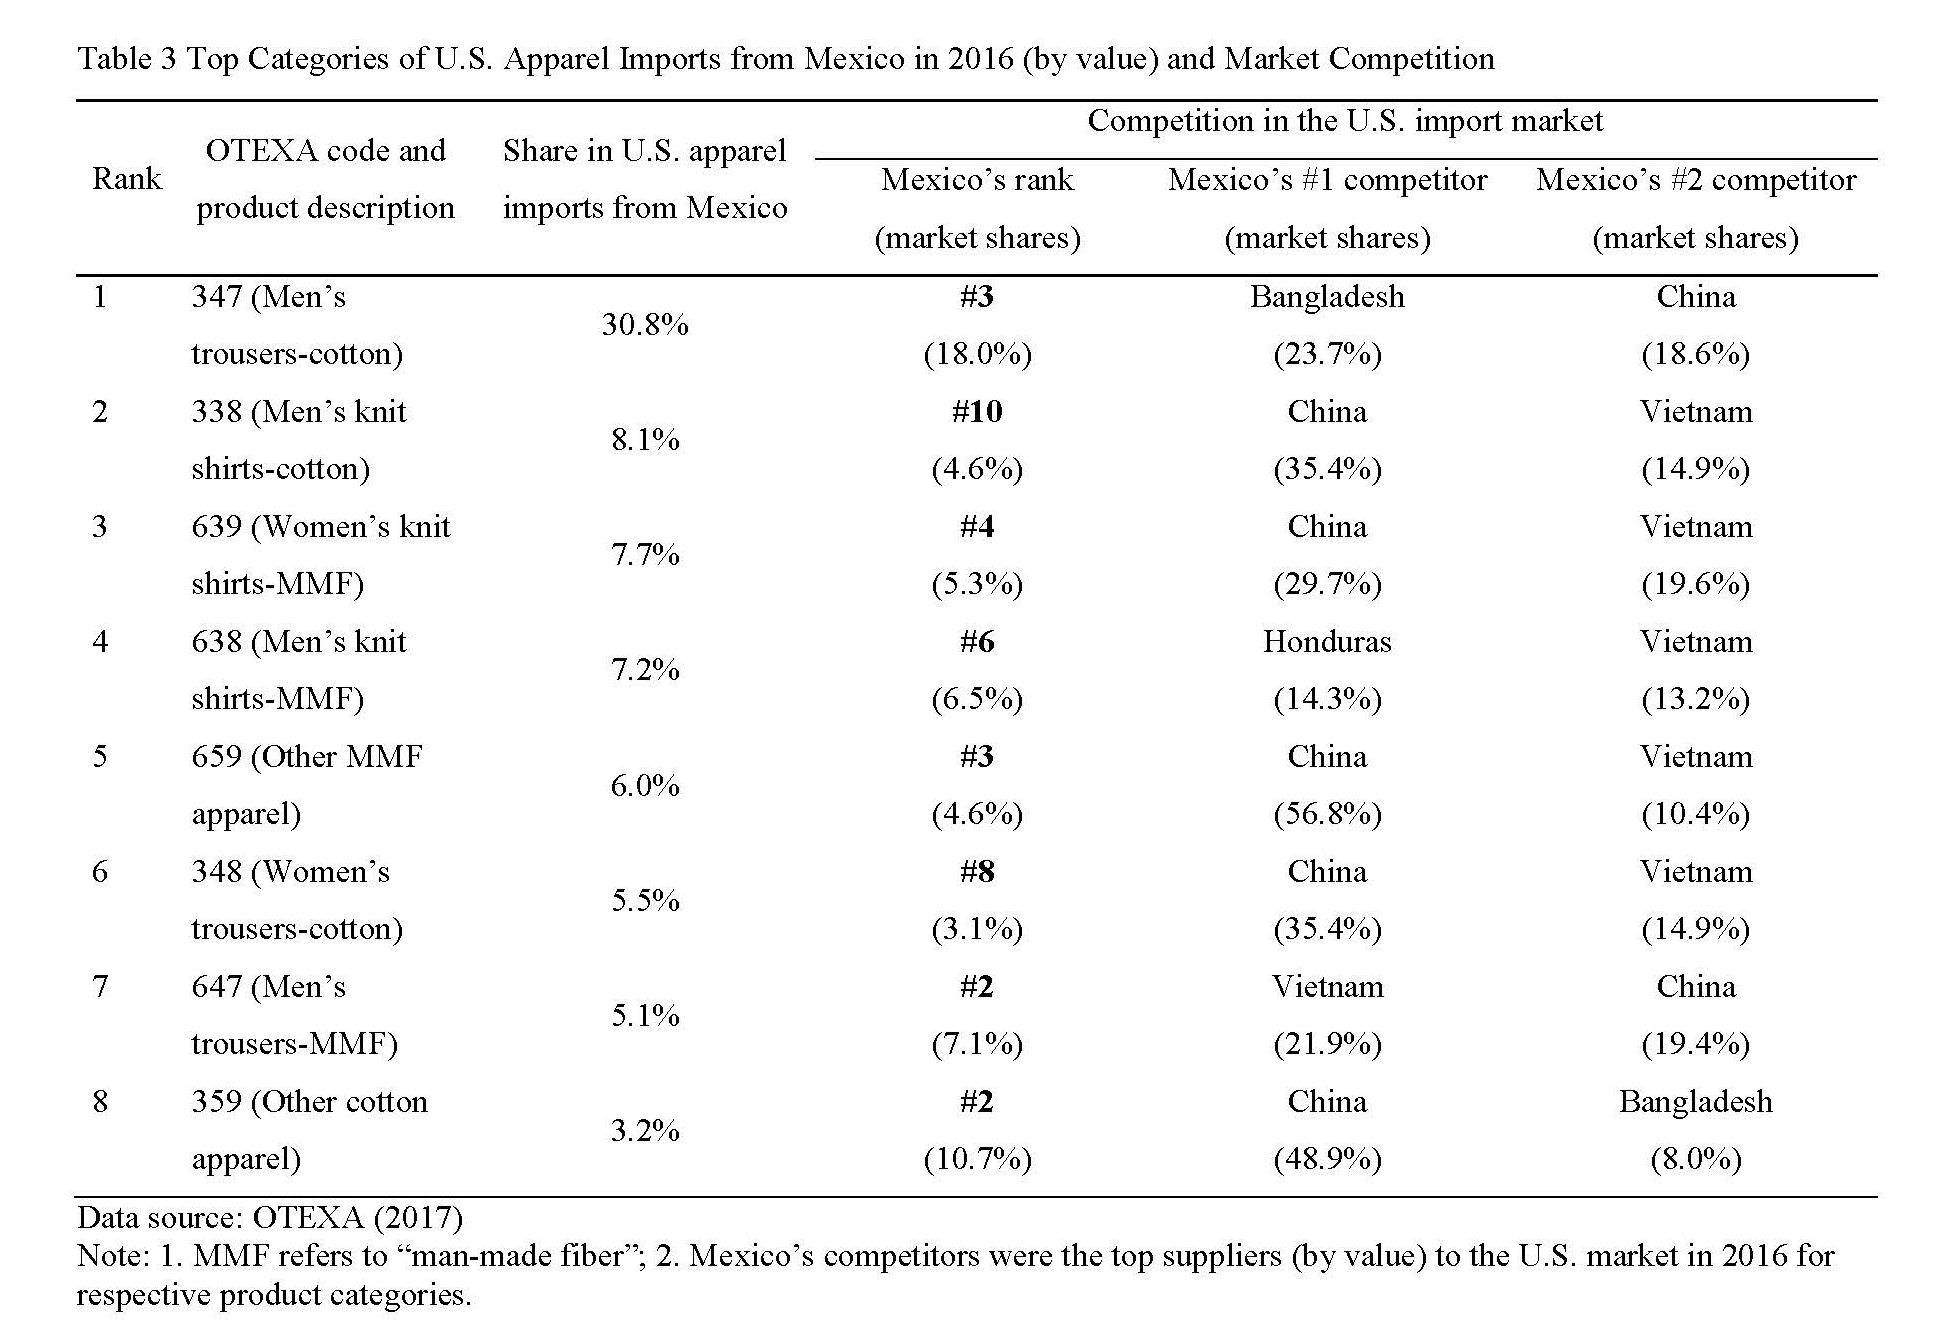
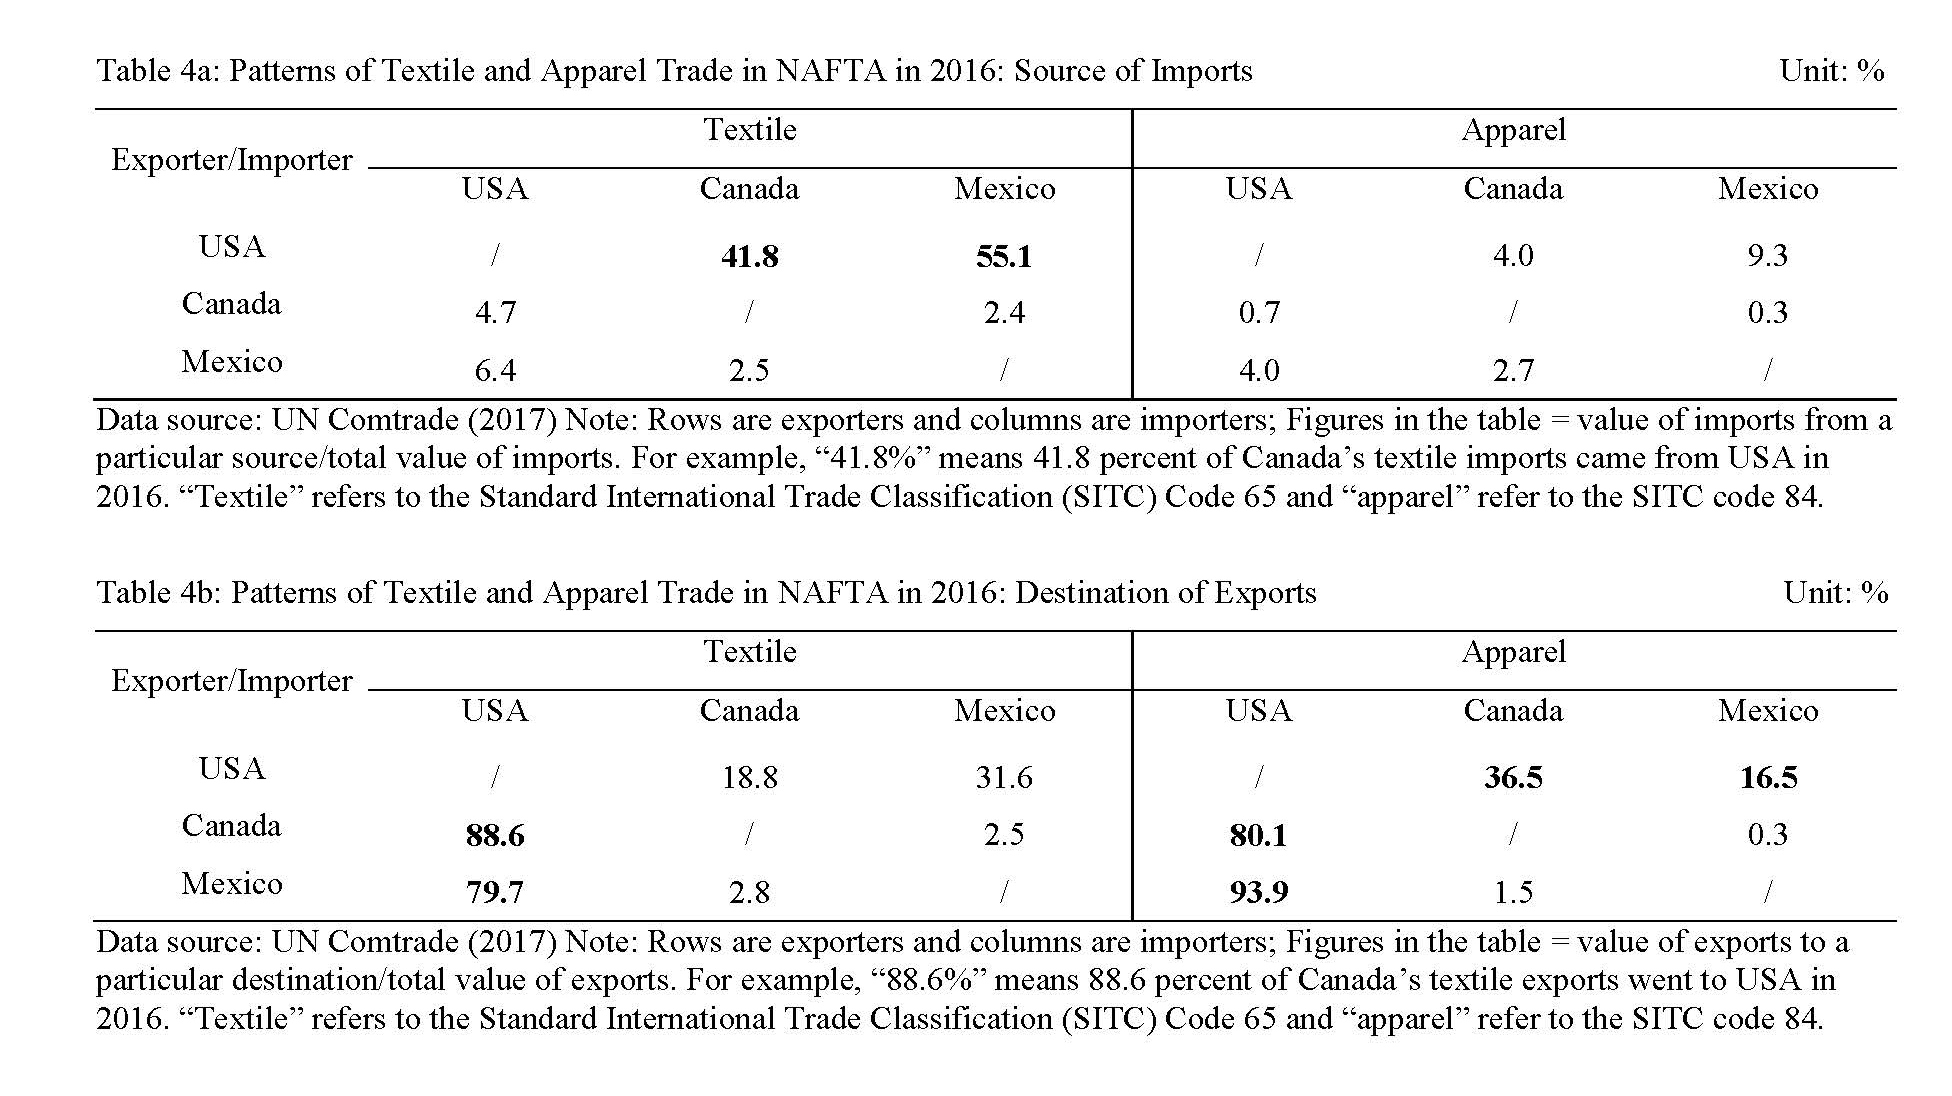
  • The destiny of the North American Free Trade Agreement (NAFTA): The potential policy change to NAFTA means so much to the U.S. textile and apparel industry as well as suppliers in other parts of the world. Notably, through a regional textile and apparel supply chain facilitated by the agreement over the past 23 years, the NAFTA region has grown into the single largest export market for U.S. textile and apparel products as well as a major apparel sourcing base for U.S. fashion brands and retailers. In 2016, as much as half of U.S. textile and apparel exports went to the NAFTA region, totaling US$11billion, and U.S. apparel imports from Mexico and Canada exceeded US$3.9billion. Understandably, if NAFTA no longer exists, sweeping changes in the trade rules, such as import duties, could significantly affect the sourcing and manufacturing behaviors of U.S. textile and apparel companies and consequentially alter the current textile and apparel trade patterns in the NAFTA region. For example, Mexico’s focus on basic apparel items suggests that U.S. importers could quickly source from elsewhere if duty savings under NAFTA are eliminated.
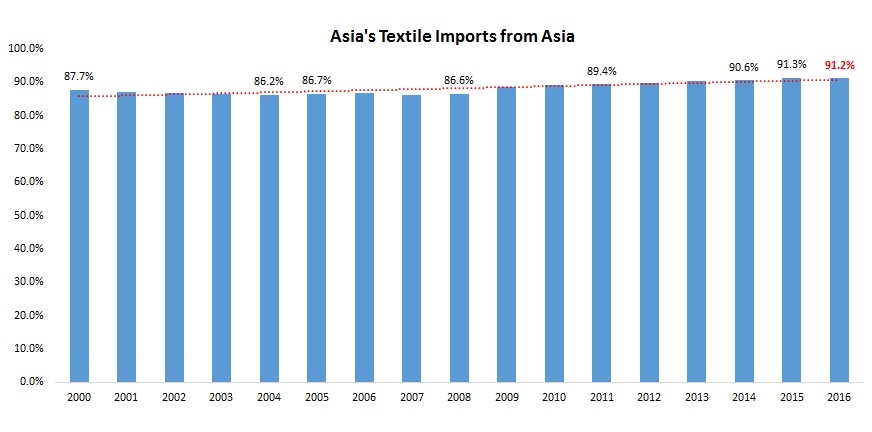
  • The possible reaching of the Regional Comprehensive Economic Partnership (RCEP): Even though RCEP is less well-known than the Trans-Pacific Partnership (TPP), we should not ignore the potential impact of the agreement on the future landscape of textile and apparel supply chain in the Asia-Pacific region. One recent study of mine shows that the RCEP will lead to a more integrated textile and apparel supply chain among its members but make it even harder for non-RCEP members to get involved in the regional T&A supply chain in the Asia-Pacific. This conclusion is backed by the latest data from the World Trade Organization (WTO): In 2016, around 91 percent of Asian countries’ textile imports came from other Asian countries, up from 86 percent in 2006. The more efficient regional supply chain as a result of RCEP will further help improve the price competitiveness of apparel made by “factory Asia” in the world marketplace. Particularly in the past few years, textile and apparel exports from Asia have already posted substantial pressures on the operation of the textile and apparel regional supply chain in the Western Hemisphere.
  • Automation of apparel manufacturing and its impact on the job market: Recall my observations at the MAGIC this August, several vendors showcased their latest technologies which have the potential to automate the cut and sew process entirely or substantially reduce the labor inputs in garment making. The impact of automation on the future of jobs is not a new topic, but the apparel industry presents a unique situation. Globally, over 120 million people remain directly employed in the textile and apparel industries today, a good proportion of whom are females living in poor rural areas. According to the World Trade Organization (WTO), for quite a few low-income and lower-middle income countries such as Bangladesh, Gambia, Pakistan, Madagascar, Sri Lanka, and Cambodia, as much as over 70 percent of their total merchandise exports were textile and apparel products in 2016. Should these labor-intensive garment sewing jobs in the developing countries were replaced by machines, the social and economic impacts will be consequential. I think it is the time to start thinking about the possible scenarios and the appropriate policy responses.

Regional Supply Chain Remains an Important Feature of Global Textile and Apparel Trade (Updated: November 2017)

Regional supply chain (or production-trade network, RPTN) or refers to a vertical industry collaboration system between countries that are geographically close to each other. Within a regional supply chain, each country specialized in certain portions of production or value-added activities based on their respective comparative advantages to maximize the efficiency of the whole supply chain.

There are three primary textile and apparel (T&A) regional supply chains in the world today:1

4

Asia: within this regional T&A supply chain, more economically advanced Asian countries (such as Japan, South Korea, and China) supply textile raw material to the less economically developed countries in the region (such as Myanmar, Cambodia, and Vietnam). Based on relatively lower wages, the less developed countries typically undertake the most labor-intensive processes of apparel manufacturing and then export finished apparel to major consumption markets around the world.

2

5

Europe: within this regional T&A supply chain, developed countries in Southern and Western Europe such as Italy and Germany serve as the primary textile suppliers. Regarding apparel manufacturing in the European Union,  products for the mass markets are typically produced by developing countries in Southern and Eastern Europe such as Poland and Romania, whereas high-end luxury products are mostly produced by Southern and Western European countries such as Italy and France. Furthermore, a high portion of finished apparel is shipped to developed EU members such as UK, Germany, France, and Italy for consumption.

3

6

America: within the region, the United States serves as the leading textile supplier, whereas developing countries in North, Central and South America (such as Mexico and countries in the Caribbean region) assemble imported textiles from the United States or elsewhere into apparel. The majority of clothing produced in the area is eventually exported to the United States for consumption.

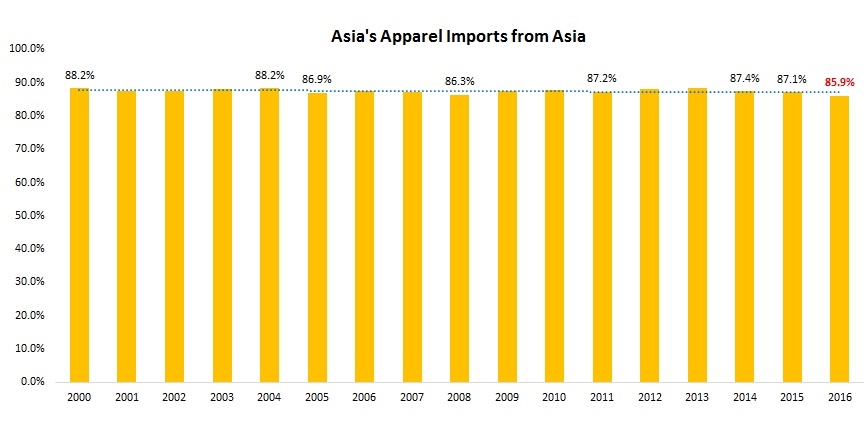
Data from the World Trade Organization (WTO) shows that regional supply chain remains an essential feature of today’s global textile and apparel trade.  Notably, three trade flows are worth watching:

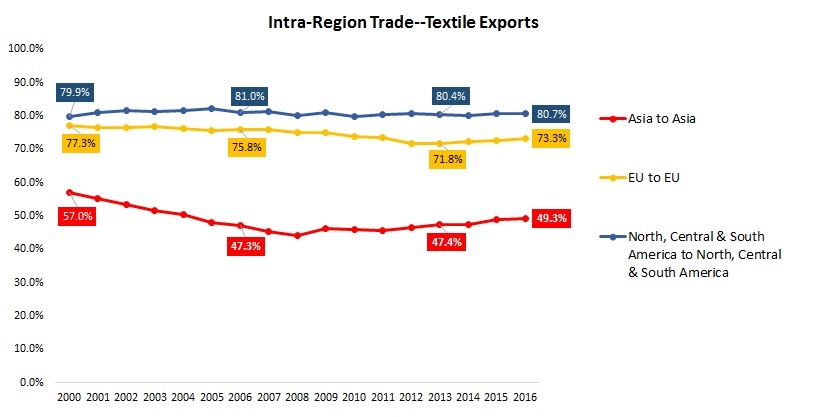
First, Asian countries are increasingly importing more textiles from within the region. In 2016, around 91.2% of Asian countries’ textile imports came from other Asian countries, up from 86.8% in 2006. This change reflects the formation of a more integrated T&A supply-chain in Asia. The more efficient regional supply chain also helps improve the price competitiveness of apparel made by “factory Asia” in the world marketplace. Particularly in the past few years, T&A exports from Asia is posting substantial pressures on the operation of the T&A regional supply chains in the Western Hemisphere.

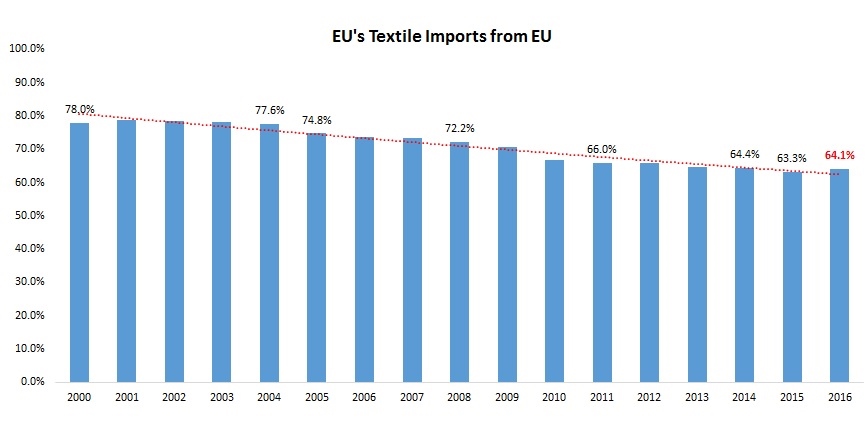
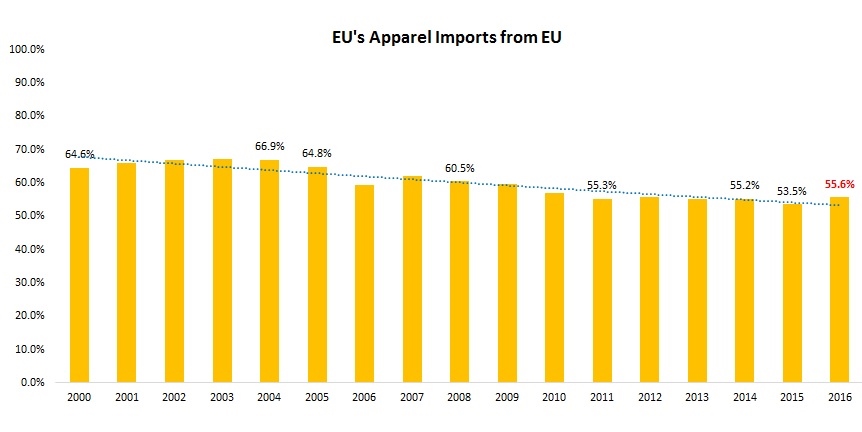
Second, the intra-region T&A trade in EU remains stable. In 2016, 64.1% of EU countries’ textile imports and 55.6% of EU countries’ apparel imports came from within the EU region. Over the same period, 73.3% of EU countries’ textile exports and 81.6 % of their apparel exports also went to other EU countries.

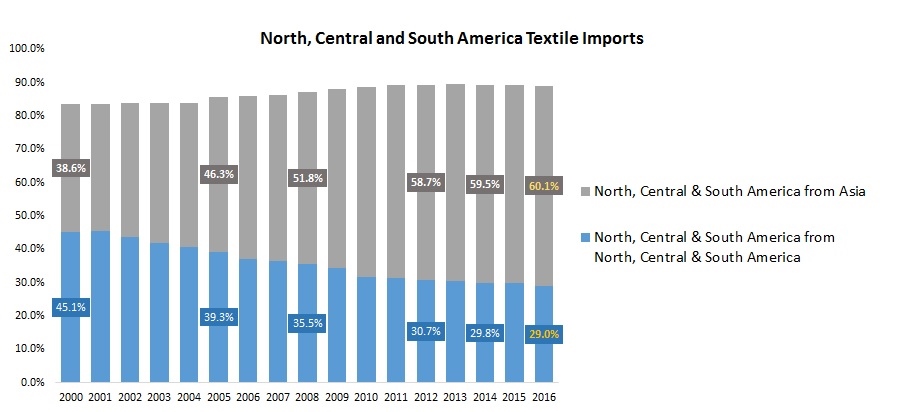
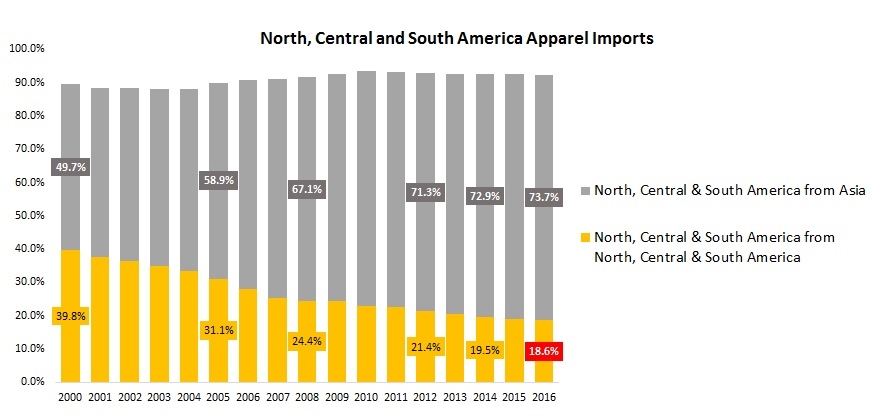
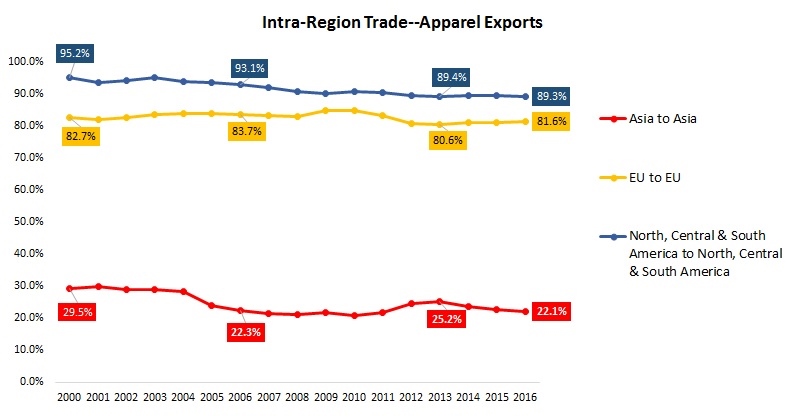
Third, the Western-Hemisphere T&A supply chain, which involves countries in North, South and Central America, is facing substantial challenges from the increasing competition from Asian T&A exporters. In 2016, only 29.0% of North, South and Central American countries’ textile imports and 18.6% of their apparel imports came from within the region, a record low in the past ten years. Meanwhile, in 2016 Asian countries supplied 60.1% of textiles and 73.7% of clothing imported by countries in the Western Hemisphere, a record high in history. Understandably, if regional free trade agreements, such as NAFTA and CAFTA-DR, no longer exist, it would be even more difficult for the Western-Hemisphere T&A supply chain to survive. The potential losers of the collapse of the Western-Hemisphere T&A supply chain will include not only US textile exporters but also apparel exporters in North, South and Central America. Notably, in 2016, 89.3% of apparel exported by countries in the Western Hemisphere were destined for the region.  

78

Data Source: World Trade Organization (2017)

by Sheng Lu

Apparel Sourcing in U.S. Trade Preference Program Countries

Speakers:

  • Tarek Kabil – Egyptian Ministry of Trade & Industry
  • Ashraf Rabiey – QIZ Minister of Egypt
  • Gabi Bar – QIZ Minister of Israel
  • Mark D’Sa – Special Project Director for Haiti
  • Moderator: Gail Strickler – former Assistant US Trade Representative for Textiles

Discussion questions:

  1. What are the financial incentives for US brands and retailers to source apparel in preference program countries? Why do U.S. apparel imports from members of AGOA, QIZs and HELP overall remain at a fairly low level despite the trade preference programs? How to improve the situation?
  2. Overall, why or why not should the US keep the trade preference programs or any critical reforms are needed?
  3. Any other interesting points you learned from the video or questions you may have?

CRS Releases Report on NAFTA Renegotiation and US Textile Manufacturing

23120124_10155817882672812_4644791366056415981_oKey findings:

U.S. textile and apparel trade with NAFTA members

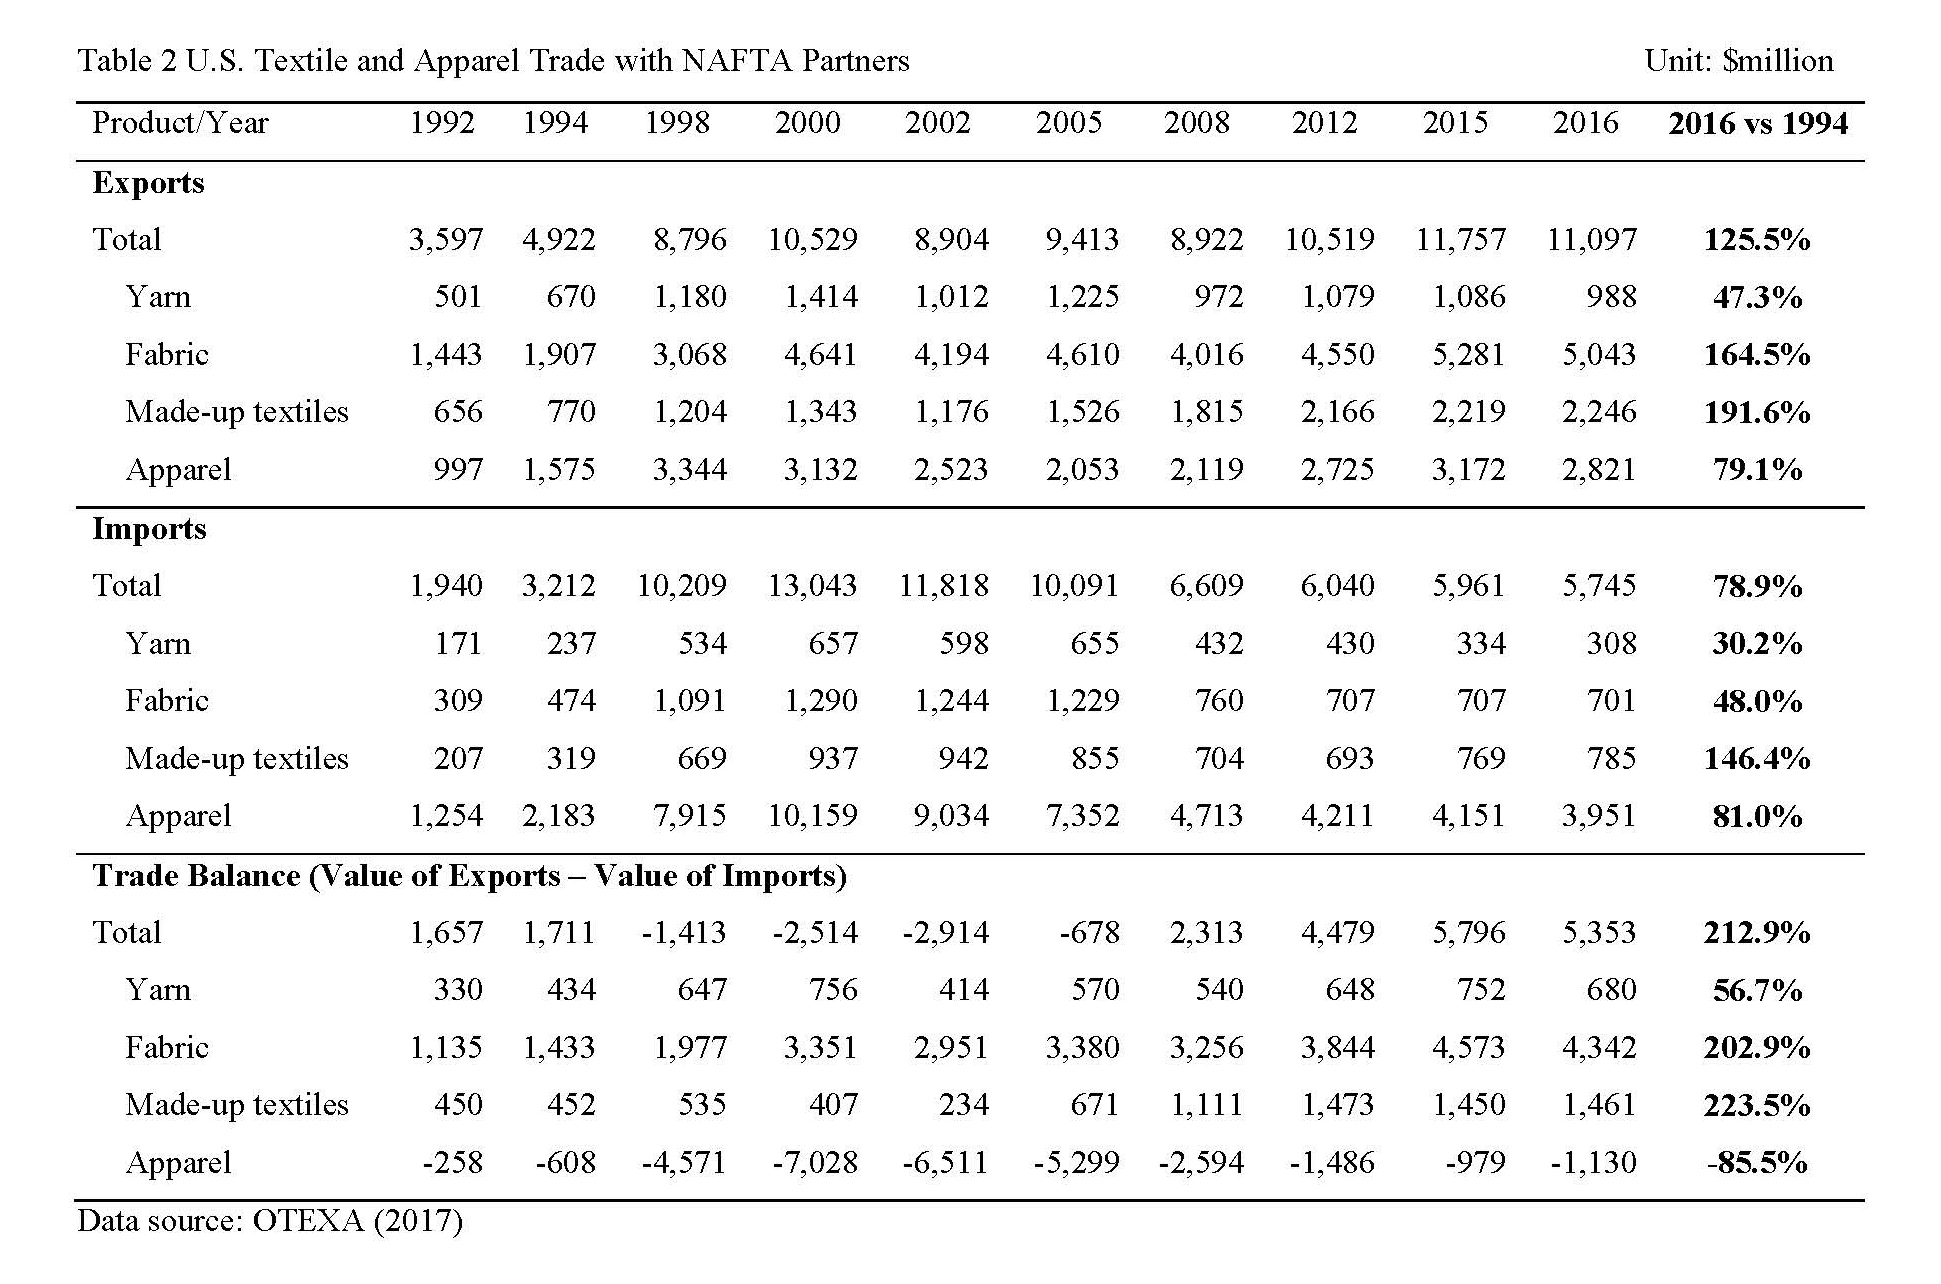
  • The United States maintains a bilateral trade surplus in yarns and fabrics ($4.1 billion in 2016) as well as made-up textiles ($720 million in 2016) with NAFTA members.
  • Regarding apparel, the United States had a trade surplus with Canada of $1.4 billion and a trade deficit with Mexico of $2.7 billion in 2016.

Impact of NAFTA on employment and production in the U.S. textile and apparel industry

  • The effects of NAFTA are NOT straightforward, and the drop in U.S. domestic textile and apparel production and jobs cannot be blamed solely on NAFTA.
  • The U.S. International Trade Commission (USITC) concluded that imports of textiles had a tiny effect on U.S. textile industry employment (a 0.4% decline) from 1998 to 2014, which covers most of the period since NAFTA’s enactment. However, the collapse of the U.S. domestic apparel industry and changing clothing tastes may have had a more significant impact on domestic textile production.
  • There is little evidence that NAFTA was the decisive factor for the loss of jobs in the U.S. apparel manufacturing sector, given that the major growth in apparel manufacturing for the U.S. market has occurred in Asian countries that receive no preferences under NAFTA.

Impact of the Tariff Preference Level (TPL) in NAFTA

  • In nearly every year since 2010, Mexico has come close to exporting the maximum allowable amount of cotton and man-made fiber apparel with duty-free foreign content. Canada’s TPL fill rates are typically highest for cotton and man-made fiber fabric and made-up products but are not usually fully filled.
  • It is not clear that eliminating the TPL program would result in a substantial return of textile production or jobs to the United States; if it were to raise the cost of Mexican apparel production, it could instead result in imports from other countries displacing imports from Mexico.
  • Other than U.S. fashion brands and retailers, Mexico and Canada reportedly oppose the elimination of the NAFTA TPL program too.

 Possible Effects of Potential NAFTA Modification

  • Mexico’s focus on basic apparel items suggests that S. importers could quickly source from elsewhere if duty savings under NAFTA are eliminated. However, even now, some U.S. fashion companies say the duty savings are not worth the time and resources required to comply with the NAFTA rules of origin and documentation requirements. In 2016, roughly 16% of qualifying textile and apparel imports from NAFTA failed to take advantage of the duty-free benefits and instead paid applicable tariffs.
  • Whatever the outcome of the NAFTA renegotiation, in the medium and long run, the profitability of the North American textile and apparel industry will likely depend less on NAFTA preferences such as yarn forward and more on the capacity of producers in the region to innovate to remain globally competitive.
  • One change in NAFTA proposed by the United States would require motor vehicles to have 85% North American content and 50% U.S. content to qualify for tariff-free treatment. If auto manufacturers were to import more passenger cars from outside the NAFTA region and pay the 2.5% U.S. import duty rather than complying with stricter domestic content requirements, automotive demand for U.S.-made technical textiles could be adversely affected.
  • If the TPP-11 countries strike a trade deal, one possible effect is that Canada and Mexico may import more textile and apparel products from other TPP countries, including Vietnam. This could ultimately be a disadvantage for U.S.-based producers. How the inclusion of Canada and Mexico in a fresh TPP-11 arrangement would affect their participation in NAFTA is unknown.

The full report can be downloaded from HERE

“Made in America”: A New Reality?

Panelists

  • Pete Bauman, Senior VP, Burlington Worldwide / ITG
  • Joann Kim, Director, Johnny’s Fashion Studio
  • Tricia Carey, Business Development Manager, Lenzing USA
  • Michael Penner, CEO, Peds Legwear
  • Moderator: Arthur Friedman, Senior Editor, Textiles and Trade, WWD 

Video Discussion Questions 

  • How does “Made in the USA” fit into US textile and apparel companies’ overall business strategy today?
  • What measures have been taken by US textile and apparel companies to bring more production back to the US? Can any measures be linked to the restructuring strategies we discussed in the class?
  • What are the significant obstacles to bringing textile and apparel manufacturing back to the US?
  • Any other exciting points/buzzwords did you learn from the panel discussion?

US Tables Proposal Aimed at Limiting the Yarn-Forward Exceptions in NAFTA Renegotiation

NAFTA-Article-201708251513

According to Inside US Trade, in the third round the NAFTA renegotiation (September 23-27, 2017), the United States has put forward several possible changes to the existing rules related to textile and apparel in the agreement:

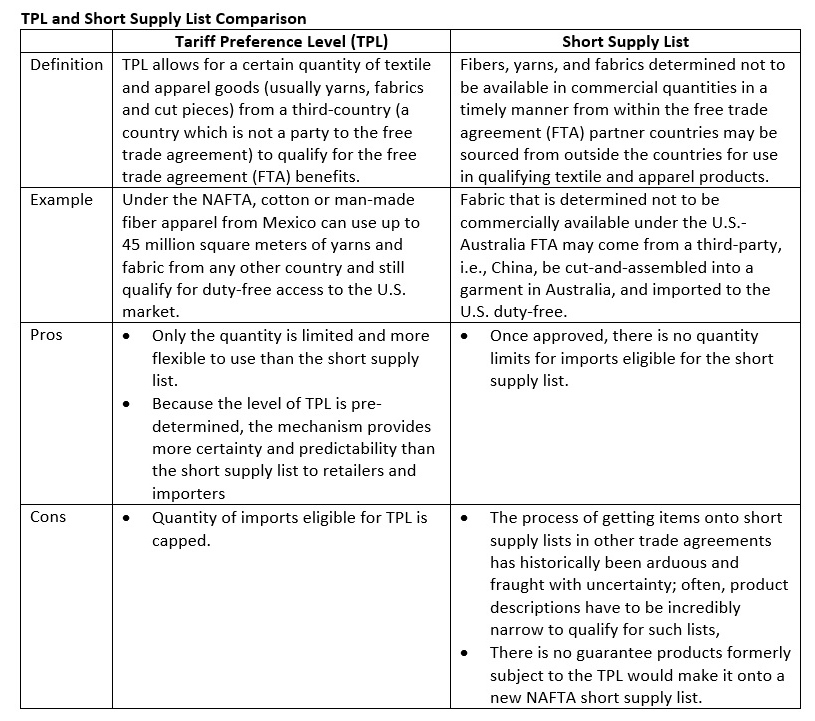
  1. USTR proposes to eliminate the tariff preference level (TPL) in NAFTA. The goal of eliminating TPL is to limit the exceptions to the yarn-forward rules of origin and “incentivize” more production in the NAFTA region as advocated by the U.S. textile industry.
  2. As a potential replacement for TPL, USTR also proses to add a short supply list mechanism to NAFTA, but details remain unclear (e.g., whether the list will be temporary or permanent; the application process).
  3. USTR further proposes a new chapter devoted to textile and apparel in NAFTA in line with more recent agreements negotiated by the U.S.. The current NAFTA does not include a textile chapter.

USTR’s proposal to remove TPL in NAFTA has met strong opposition from the U.S. apparel industry, fashion retailers, and brands as well as their partners in Mexico and Canada. According to these industry groups:

  • Eliminating TPLs would disrupt supply chains that have been in place for more than two decades.
  • Eliminating TPLs would not move production back to the U.S. but would instead further incentivize sourcing from outside the NAFTA region and put textile and apparel factories in the region out of business. For example, some apparel factories remain production in the NAFTA region largely because TPL allows them to use third-party textile inputs and the finished goods can still be treated as NAFTA originating.
  • Without the TPL, companies would opt to produce textile and apparel products in the least expensive way possible, likely outside the NAFTA region, and ship items into North America despite being hit with most-favored-nation (MFN) tariffs.
  • A short supply list would not ease the supply chain disruptions that would result from the removal of the TPLs because there is no guarantee products formerly subject to the TPL would make it onto a new NAFTA short supply list.

A potential compromise could involve a reduction in Canadian and Mexican TPLs to the U.S. and an increase in the U.S. TPLs to Mexico and Canada, which could boost the U.S. trade surplus in textiles and apparel with its NAFTA partners and throw a bone to the U.S. textile industry by ostensibly incentivizing domestic production.

Untitled

Fact-check about TPL

TPL was included in NAFTA as a compromise for adopting the yarn-forward rules of origin in the agreement. Before NAFTA, the US-Canada trade agreement adopted the less restrictive fabric-forward rules of origin.

The TPL mechanism has played a critical role in facilitating the textile and apparel (T&A) trade and production collaboration between the United States and Canada, in particular, the export of Canada’s wool suits to the United States and the U.S. cotton or man-made fiber apparel to Canada. Statistics from the Office of Textiles and Apparel (OTEXA) show that in 2016 more than 70% of the value of Canada’s apparel exports to the United States under NAFTA utilized the TPL provision, including almost all wool apparel products. Over the same period, the TPL fulfillment rate for U.S. cotton or man-made fiber apparel exports to Canada reached 100%, suggesting a high utilization of the TPL mechanism by U.S. apparel firms too (Global Affairs Canada, 2017). Several studies argue that without the TPL mechanism, the U.S.-Canada bilateral T&A trade volume could be in much smaller scale (USITC, 2016). Notably, garments assembled in the United States and Canada often contained non-NAFTA originating textile inputs, which failed them to meet the “yarn-forward” rules of origin typically required for the preferential duty treatment under NAFTA.

Related articles:


Trade Issues Facing the U.S. Apparel and Retail Industry

Panel:

  • Steve Lamar, Executive VP at the American and Apparel Footwear Association (AAFA)
  • Jon Gold, VP of Supply Chain and Customs Policy at the National Retail Federation (NRF)
  • Robert Antoshak (Host), Managing Director at Olah Inc.

Topic discussed

  • Renegotiation of the North American Free Trade Agreement (NAFTA)
  • Trump’s trade policy agenda
  • What’s going on in the retail market?
  • Technology and the future of apparel supply chain
  • US labeling requirements and a return of Made-in-USA

2017 U.S. Fashion Industry Benchmarking Study Released

The 2018 U.S. Fashion Industry Benchmarking Study is now availablecover

The report can be downloaded from HERE

Key findings of the study:

While the majority of respondents remain confident about the five-year outlook for the U.S. fashion industry, the percentage of those who are “optimistic” or “somewhat optimistic” dropped to a record low since we began conducting this study in 2014. This change could be due to concerns about the “protectionist trade policy agenda in the United States” and “market competition in the United States from e-commerce,” the top two concerns this year.

  • The percentage of those who are “optimistic” or “somewhat optimistic” fell from 92.3 percent in 2016 to 71.0 percent in 2017, a record low since we began conducting this study in 2014. As many as 12.9 percent of respondents are “somewhat pessimistic” about the next five years, mostly large-scale retailers with more than 3,000 employees.
  • Despite the challenges, demand for human talent in the industry overall remains robust. This year, around 80 percent of respondents plan to hire more employees in the next five years, especially supply chain specialists, data scientists, sourcing specialists, and marketing analysts.
  • Cost is no longer one of the top concerns; respondents are less stressed about “increasing production or sourcing cost,” which slipped from #2 challenge in 2016 to #7 challenge in 2017. Only 34 percent rate the issue among their top five challenges this year, significantly lower than 50 percent in 2016 and 76 percent in 2015. Labor cost remains the top factor driving up sourcing cost in 2017.

Although U.S. fashion companies continue to seek alternatives to “Made in China,” China’s position as the top sourcing destination remains unshakable. Meanwhile, sourcing from Vietnam and Bangladesh may continue to grow over the next two years, but at a relatively slow pace.

  • 91 percent of respondents source from China; while 100 percent sourced from China in our past three studies, China is still the top-ranked sourcing destination this year, and the percentage of those expecting to decrease sourcing from the country fell from 60 percent in 2016 to 46 percent this year—and many more expect to maintain their current sourcing value or volume from the country in the next two years.
  • Likely reflecting the United States’ withdrawal from the Trans-Pacific Partnership (TPP) and the expectation of increasing labor costs, only 36 percent of respondents expect to increase sourcing from Vietnam in the next two years, much lower than 53 percent who said the same in 2016.
  • Respondents are cautious about expanding sourcing from Bangladesh in the next two years, with only 32 percent expecting to somewhat increase sourcing While “Made in Bangladesh” enjoys a prominent price advantage over many other Asian suppliers, respondents view Bangladesh as the having the highest risk for compliance.

U.S. fashion companies continue to maintain truly global supply chains.

  • Respondents source from 51 countries or regions in 2017, close to the 56 in last year’s study.
  • 57.6 percent source from 10+ different countries or regions in 2017, up from 51.8 percent in last year’s survey. In general, larger companies have a more diversified sourcing base than smaller companies. Additionally, retailers maintain a more diversified sourcing base than brands, importers/wholesalers, and manufacturers.
  • Around 54 percent expect their sourcing base will become more diversified in the next two years, up from 44 percent in 2016; among these respondents, over 60 percent currently source from more than 10 different countries or regions.
  • The most common sourcing model is shifting from “China Plus Many” to “China Plus Vietnam Plus Many.” The typical sourcing portfolio today is 30-50 percent from China, 11-30 percent from Vietnam, and the rest from other countries.
  • While Asia as a whole remains the dominant sourcing region for U.S. fashion companies, the Western Hemisphere is growing in popularity. This year, we see a noticeable increase in sourcing from the United States (70 percent, up from 52 percent in 2016) and countries in North, South, and Central Americas, which offer a shorter lead time and relatively lower risk of compliance.

Today, ethical sourcing and sustainability are given more weight in U.S. fashion companies’ sourcing decisions. Respondents also see unmet compliance (factory, social and/or environmental) standards as the top supply chain risk.

  • 5 percent of respondents say ethical sourcing and sustainability have become more important in their company’s sourcing decisions in 2017 compared to five years ago.
  • 100 percent of respondents currently audit their suppliers, including how suppliers treat their workers, suppliers’ fire safety, and suppliers’ building safety. The majority (93 percent) use third-party certification programs to audit, with a mix of announced and unannounced audits.
  • As many as 90 percent of respondents map their supply chains, i.e., keep records of name, location, and function of suppliers. More than half track not only Tier 1 suppliers, suppliers they contract with directly, but also Tier 2 suppliers, i.e. supplier’s suppliers. It is less common for U.S. fashion companies to map Tier 3 and Tier 4 suppliers though, which could be because of the difficulty of getting access to related information with such a globalized and highly fragmented supply chain.

Free trade agreements (FTAs) and trade preference programs remain underutilized, and several FTAs, including CAFTA-DR, are utilized even less this year than in previous years.

  •  Of the 19 FTAs/preference programs we examined this year, only NAFTA is used by more than 50 percent of respondents for import purposes.
  • Even more concerning, some U.S. fashion companies source from countries/regions with FTAs/preference programs but, for whatever reason, do not claim the benefits. For example, as many as 38 percent and 6 percent of respondents, respectively, do not use CAFTA-DR and NAFTA when they source from these two regions.

Respondents unanimously oppose the U.S. border adjustment tax (BAT) proposal and call for the further removal of trade barriers, including restrictive rules of origin and high tariffs.

  • 100 percent of respondents oppose a border adjustment tax; 84 percent “strongly oppose” it.
  • Respondents support initiatives to eliminate trade barriers of all kinds, from high tariffs to overcomplicated documentation requirements, to the restrictive yarn-forward rules of origin in NAFTA and future free trade agreements.
  • Respondents say the “complex standards on labeling and testing”, “complex rules for the valuation of goods at customs” and “administrative and bureaucratic delays at the border” are the top non-tariff barriers they face when sourcing today.

The benchmarking studies from 2014 to 2016 can be downloaded from https://www.usfashionindustry.com/resources/industry-benchmarking-study 

NAFTA Renegotiating Objectives Related to the Textile and Apparel Industry

Untitled

On Tuesday (July 17, 2017), the Office of the U.S. Trade Representative (USTR) released its detailed and comprehensive summary of the renegotiating objectives of the North American Free Trade Agreement (NAFTA). In the statement, USTR says that “through the renegotiation of NAFTA, the Trump Administration will seek a much better agreement that reduces the U.S. trade deficit and is fair for all Americans by improving market access in Canada and Mexico for U.S. manufacturing, agriculture, and services.”

Several released negotiating objectives address textile and apparel (T&A) directly or are highly relevant to the sector:

Trade in Goods

  • Improve the U.S. trade balance and reduce the trade deficit with the NAFTA countries.
  • Maintain existing duty-free access to NAFTA country markets for U.S. textile and apparel products and seek to improve competitive opportunities for exports of U.S. textile and apparel products while taking into account U.S. import sensitivities.

Rules of Origin

  • Update and strengthen the rules of origin, as necessary, to ensure that the benefits of NAFTA go to products genuinely made in the United States and North America.
  • Ensure the rules of origin incentivize the sourcing of goods and materials from the United States and North America.
  • Establish origin procedures that streamline the certification and verification of rules of origin and that promote strong enforcement, including with respect to textiles.
  • -Establish origin procedures that streamline the certification and verification of rules of origin and that promote strong enforcement, including with respect to textiles.

Customs and Trade Facilitation

  • Provide for automation of import, export, and transit processes, including through supply chain integration; reduced import, export, and transit forms, documents, and formalities; enhanced harmonization of customs data requirements; and advance rulings regarding the treatment that will be provided to a good at the time of importation.

Comments:

  1. Notably, reducing the trade deficit and bringing more manufacturing jobs back to the United States are at the core of the NAFTA’s renegotiating objectives. These two goals are also highly consistent with Trump’s rhetoric on his trade policy.
  2. A dilemma facing the T&A sectoral negotiation is that the United States currently runs a robust trade surplus with Canada and Mexico for textiles: in 2016, the value of U.S. trade surplus (i.e. the value of exports minus the value of imports) totaled $680 million for yarns (up 56.7% from 1994), $4,342 million for fabrics (up 202.9% from 1994) and $1,461 million for made-up textiles (up 223.5% from 1994). Meanwhile, although the United States is in a trade deficit with NAFTA partners for apparel ($1,130 million in 2016), U.S. apparel imports from Canada and Mexico often contain textile inputs “Made in the USA” through the Western-Hemisphere supply chain. Blindly cutting the trade deficit on apparel ironically could affect the U.S. textile exports to the NAFTA region negatively.
  3. Based on the released objectives, it seems unlikely that the NAFTA renegotiation will liberalize the yarn-forward rules of origin for textile and apparel. On the contrary, USTR could review the current exceptions to the yarn-forward rules, including the tariff preference levels (TPL) and some special regimes such as the 9802 program related to fabric sourcing to strengthen the manufacturing base and create MANUFACTURING jobs in the United States. Recognizing the competing arguments between the U.S. textile industry and the apparel industry (fashion brands and retailers) regarding the necessity and impact of these exceptions, USTR also needs more inputs of how companies use exceptions like the TPL in sourcing and why they use them.
  4. Other than the rules of origin, trade facilitation and customs enforcement will be another major agenda related to the T&A sector in the NAFTA renegotiation. Elements from the newly enforced Trade Facilitation and Trade Enforcement Act of 2015 could be added to the updated NAFTA.
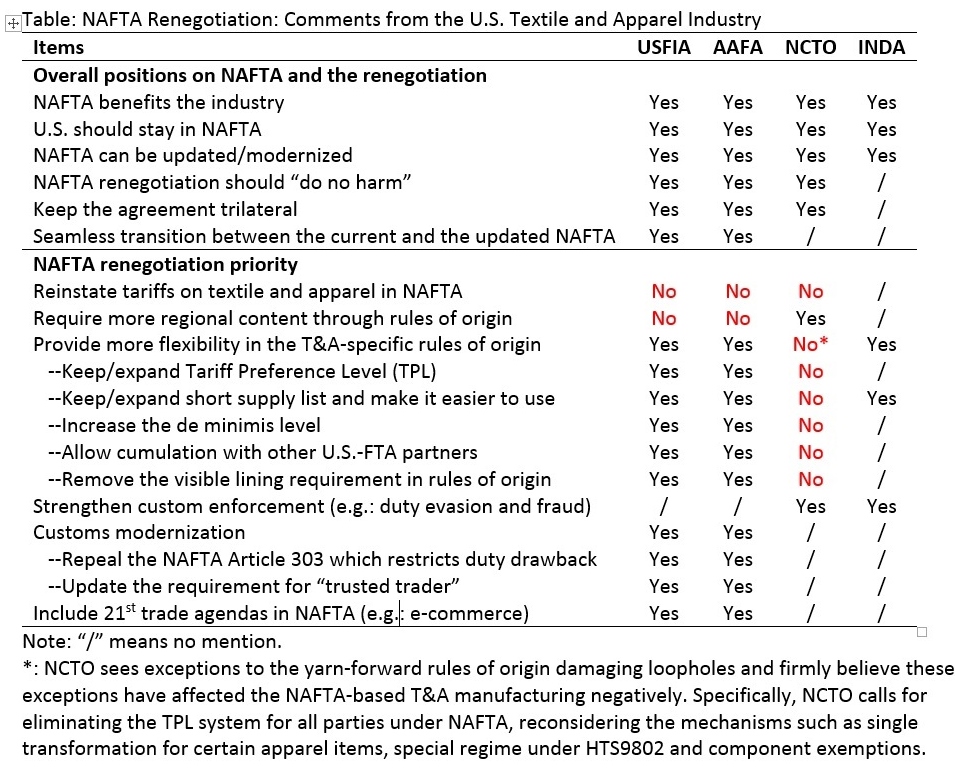
  5. A positive aspect of the NAFTA T&A sectoral negotiation is that all parties alongside the supply chain, from U.S. cotton growers, textile mills to apparel retailers and brands recognize the value of NAFTA and no one calls for pulling out of the agreement. It is also a consensus view of the U.S. T&A industry that NAFTA renegotiation should “do no harm”, i.e. strengthening rather than weakening the current supply-chain partnership between NAFTA members. Additionally, stakeholders in the U.S. T&A industry unanimously support keeping the renegotiation trilateral, but agree to use bilateral provisions to address some particular concerns.
  6. The NAFTA renegotiation may officially start on August 17 or 18, 2017. However, Time is the enemy of the NAFTA renegotiation. While there is a strong incentive for all parties to finish the negotiation by the end of 2017 given the upcoming U.S. mid-term election and the Mexican presidential election in 2018, the ambitious renegotiation agenda makes it extremely challenging to meet that goal. Risks are still there that Trump may pull the United States out of NAFTA should he lose patience for the renegotiation. Notably, Trump’s dislike of NAFTA is real.

Sheng Lu

Related: US Textile and Apparel Industry and NAFTA: Key Statistics (updated July 2017)

USTR Hearing on the Renegotiation of NAFTA: Textile and Apparel Industry

US Textile and Apparel Associations Comment on NAFTA Renegotiation

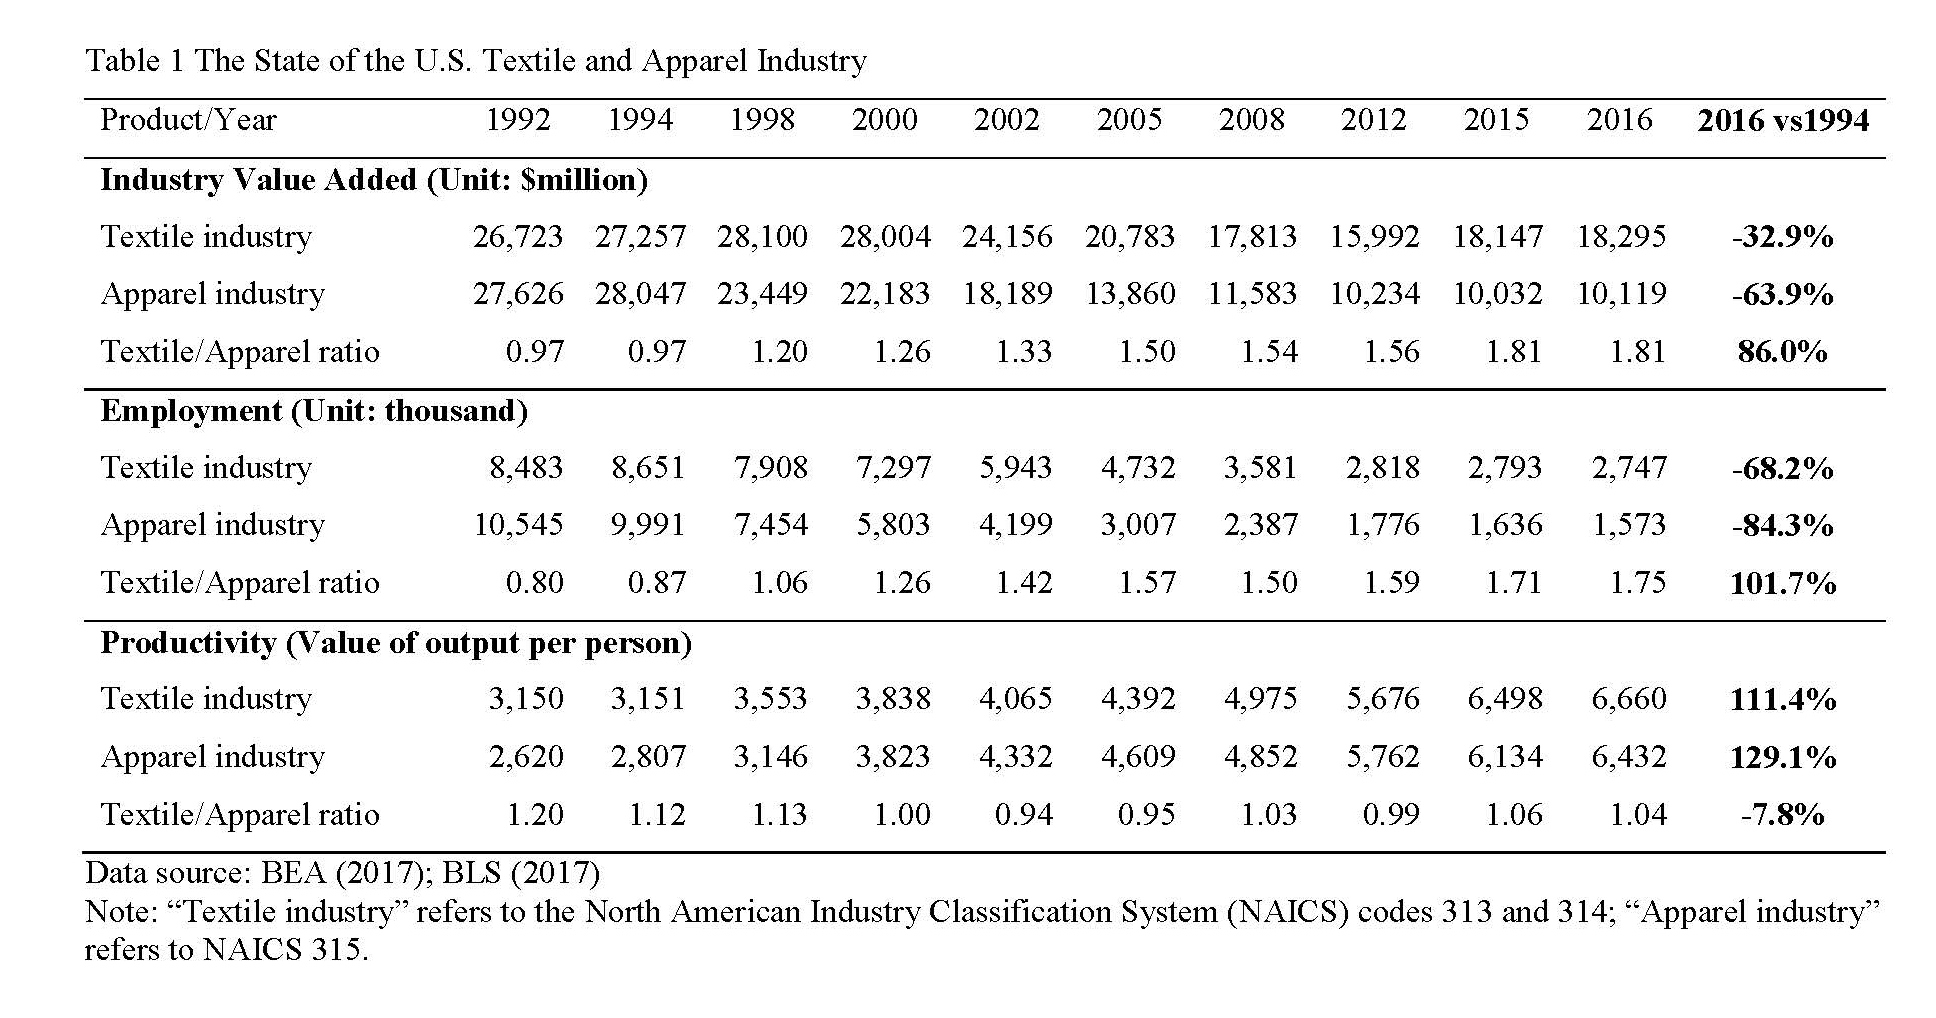
US Textile and Apparel Industry and NAFTA: Key Statistics (updated July 2017)

References and tables_Page_1References and tables_Page_2References and tables_Page_3

References and tables_Page_4

USTR Hearings on the Renegotiation of NAFTA: Textile and Apparel Industry

Panel:

  • Augustine Tantillo, President, and CEO, National Council of Textile Organizations
  • David Spooner, Counsel representing the U.S. Fashion Industry Association
  • Stephen Lamar, Executive Vice President, American Apparel and Footwear Association
  • Randy Price, VP, Managing Director Product Supply—Americas, VF Corporation
  • Marc Fleischaker, Trade Counsel, Rubber and Plastic Footwear Manufacturers Association
  • Reece Langley, VP of Washington Operations, National Cotton Council
  • Richard Gottuso, Vice President and General Counsel, Bracewell, LLP-Hunter Douglas
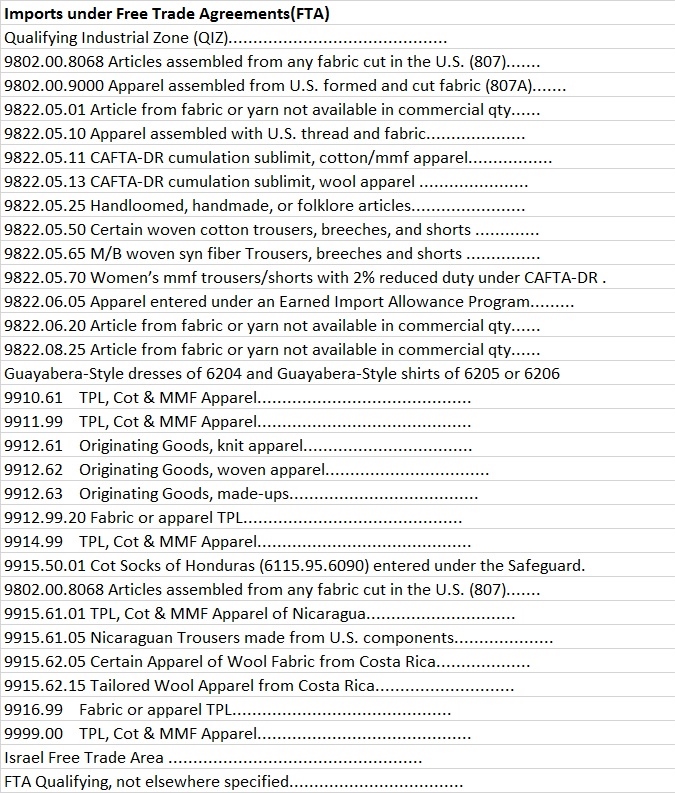
US Textile and Apparel Industry Associations Comment on NAFTA Renegotiation

This week, several leading U.S. textile and apparel industry associations submitted their comments to the Office of the United States Trade Representative (USTR) regarding the renegotiation objectives of the North American Free Trade Agreement (NAFTA). Below is a summary of these organizations’ viewpoints based on their submissions:

NAFTA renegotiation

Appendix: Submitted written comments

What Will Happen to the U.S. Textile and Apparel Industry if NAFTA Is Gone?

References and tables_Page_1.jpg

References and tables_Page_2

Since its taking effect in 1995, NAFTA, a trade deal between the United States, Mexico, and Canada, has raised heated debate regarding its impact on the U.S. economy. President Trump has repeatedly derided NAFTA, describing it as “very, very bad” for U.S. companies and workers, and he promised during his campaign that he would remove the United States from the trade agreement if he could not negotiate improvements.

The U.S. textile and apparel (T&A) industry is a critical stakeholder of the potential policy change, because of its deep involvement in the regional T&A supply chain established by the NAFTA. Particularly, over the past decades, trade creation effect of the NAFTA has significantly facilitated the formation of a regional T&A supply chain among its members. Within this supply chain, the United States typically exports textiles to Mexico, which turns imported yarns and fabrics into apparel and then exports finished apparel back to the United and Canada for consumption.

So what will happen to the U.S. T&A industry if NAFTA no longer exists? Here is what I find*:

figure 1

First, results show that ending the NAFTA will significantly hurt U.S. textile exports. Specifically, the annual U.S. textile exports to Mexico and Canada will sharply decline by $2,081 million (down 47.7%) and $351 million (down 14%) respectively compared to the base year level in 2015.Although U.S. textile exports to other members of the Central America Free Trade Agreement (CAFTA-DR), will slightly increase by $42 million (up 1.5%), the potential gains will be far less than the loss of exports to the NAFTA region.

2

Second, results show that ending the NAFTA will significantly reduce U.S. apparel imports from the NAFTA region. Specifically, annual U.S. apparel imports from Mexico and Canada will sharply decrease by $1,610 million (down 45.3%) and $916 million (down 154.2%) respectively compared to the base year level in 2015 (H2 is supported). However, ending the NAFTA would do little to curb the total U.S. apparel imports, largely because U.S. companies will simply switch to importing more apparel from other suppliers such as China and Vietnam.

3

Third, ending NAFTA will further undercut textile and apparel manufacturing in the United States rather than bring back “Made in the USA.” Specifically, annual U.S. textile and apparel manufacturing will decline by $1,923 million (down 12.8%) and $308 million (down 3.0%) respectively compared to the base year level in 2015 (H3 is supported). Weaker demand from the NAFTA region is the primary reason why U.S. T&A manufacturing will suffer a decline.

These findings have several important implications. On the one hand, the results suggest that the U.S. T&A will be a big loser if the NAFTA no longer exists. Particularly, ending the agreement will put the regional T&A supply chain in jeopardy and make the U.S. textile industry lose its single largest export market—Mexico. On the other hand, findings of the study confirm that in an almost perfectly competitive market like apparel, raising tariff rate is bound to result in trade diversion. With so many alternative suppliers out there, understandably, ending the NAFTA will NOT increase demand for T&A “Made in the USA,” nor create more manufacturing jobs in the sector. Rather, Asian textile and apparel suppliers will take away market shares from Mexico and ironically benefit most from NAFTA’s dismantlement.

*Note: The study is based on the computable general equilibrium (CGE) model developed by the Global Trade Analysis Project (GTAP). Data of the analysis came from the latest GTAP9 database, which includes trade and production data of 57 sectors in 140 countries in 2015 as the base year. For the purpose of the study, we assume that if NAFTA no longer exists, the tariff rate applied for T&A traded between NAFTA members will increase from zero to the normal duty rate (i.e. the Most-Favored-Nation duty rate) in respective countries.

by Sheng Lu

Gail Strickler, Former Assistant US Trade Representative for Textiles, on Trump’s Trade Policy

DSCF4755 (2)

Gail Strickler, Assistant U.S. Trade Representative for Textiles (2009-2015), who negotiated the textile chapter under the Trans-Pacific Partnership (TPP), visited UD on April 13 and delivered a public lecture on The Global Apparel Industry – Style and Substance. The event is part of the Fashion and Diplomacy Lecture Series sponsored by the Institute for Global Studies and the Department of Fashion and Apparel Studies.

During the talk, Gail made a few comments regarding trade policy in the Trump administration:

First, Gail believes that the existing U.S. free trade agreements (FTAs), trade preference programs (PTAs) and the U.S. commitments at the World Trade Organization (WTO) are unlikely to be undone by President Trump because retaliatory actions from other trading partners would be inevitable.

Second, regarding the North American Free Trade Agreement (NAFTA), Gail doesn’t think the proposed renegotiation would threaten the benefits presently enjoyed by the U.S. textile and apparel industry. Gail also thinks the Central America Free Trade Agreement (CAFTA-DR) is a lifeline for the U.S. domestic textile manufacturing sector. Notably, NAFTA and CAFTA-DR together account for almost 70% of U.S. yarn and fabric exports.

Third, as observed by Gail, Wilbur Ross, the Commerce Secretary, has been given an expanded role in trade in the Trump Administration. Gail believes Ross’s appointment is likely to bode well for NAFTA and CAFTA-DR on textiles because Ross until recently owned the International Textile Group (ITG), which has significant investments in Mexico and relies heavily on CAFTA-DR for its textile sales.

However, Gail doesn’t think concentrating on trade deficits to define trade policy is a very “good method” of navigating the trade world. Interesting enough, last time when the U.S. trade deficit significantly shrank was during the 2008 financial crisis.  

Gail is also a strong advocator of sustainability in the textile and apparel sector. She believes that trade programs can play a vital role in encouraging sustainable development, improving labor practices and facilitating sustainable regional supply chains. According to Gail, powerful the labor provisions in trade programs can be if strong incentives are coupled with a credible threat of rapid enforcement – little evidence of effectiveness if only one (or fewer) of these conditions is met. However, comparing with enforcing labor provisions, Gail finds promoting and enforcing environmental sustainability standards through trade agreements is much more complex in the textile and apparel sector and will require creativity and strong participation from private sectors and consumers.

Before the public lecture, Gail visited FASH455 and had a special discussion session with students on topics ranging from the textile and apparel rules of origin in TPP, NAFTA renegotiation, AGOA renewal and state of the U.S. textile and apparel industry.

Are US Textile and Apparel Imports Using Free Trade Agreements? (Updated February 2017)

Free trade agreements (FTAs) are arrangement among two or more countries under which they agree to eliminate tariffs and non-tariff (NTB) barriers on trade among themselves (Cooper, 2014). Theoretically, companies shall be interested in increasing imports from FTA regions because of the duty-free treatment (i.e., the trade creation effect). Particularly, not paying import tariff duty can be a great cost advantage for textile and apparel (T&A) companies given the fact that the average US import tariff rate was still as high as 8% for textiles and 11.6% for apparel in 2016 (WTO, 2017).

fta-2017

Despite the potential benefit of using FTAs, data from the Office of Textiles and Apparel show that 85.7% of US T&A imports came from non-FTA regions in 2016. Interesting enough, although more FTAs have taken effect in the United States, T&A imported under FTA as a percent of total T&A imports dropped from 15.1% in 2008 to 14.3% in 2016.

Among the FTAs in force, the North American Free Trade Agreement (NAFTA) and the Dominican-Republic-Central America Free Trade Agreement (CAFTA-DR) altogether accounted for 75.9% of the value of total U.S. T&A imports under FTAs in 2016.

us-fta-utlization-2016

Statistics further reveal that sometimes companies did not claim duty free benefits of FTAs even though they imported T&A from the FTA region. For example, in 2016 about 29.9% of U.S. T&A imports from South Korea, 24.3% from CAFTA-DR and 16.3% from NAFTA and 12.9% from Columbia did not enjoy the duty free treatment granted by the respective FTAs.

fta-rule-3

Some industry experts say the complex T&A rules of origin is a major factor why US T&A companies are not using FTAs enough. According to the Office of Textiles and Apparel (OTEXA), there are more than 20 different tariff lines dealing with various T&A rule of origin situations under respective FTAs.

short-supply-2016

Additionally, U.S. T&A importers seem to use the “short supply list” mechanism–an exception to the yarn forward rules of origin under FTAs, more actively. For example, in 2016 around 2.4% of US T&A imports under FTAs took advantage of the “short supply list” mechanism, increased from only 1.2% in 2008. Similarly, a record high of 6.2% of U.S. T&A imports under the CAFTA-DR used the short supply list in 2016.

Sheng Lu

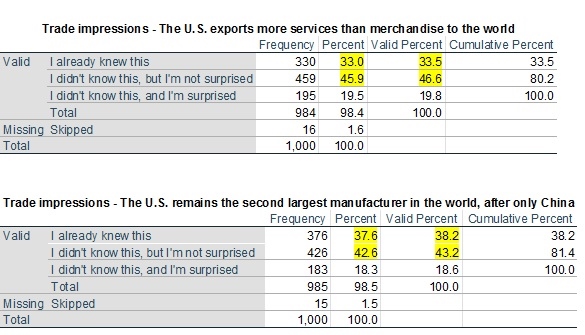
How Americans Knew about Textile and Apparel Trade: New Survey Results

The following results are preliminary findings from the Cooperative Congressional Election Study (CCES) 2016 survey. The survey was administrated by YouGov/Polimetrix and conducted from September to October 2016.

2016-survey-1

2016 survey 2.jpg

2016-survey-3

Acknowledgement:

Thanks to the University of Delaware Office of the Provost, Social Science Data Analytics Initiative, and Center for Political Communication in support of the data collection. For questions about the data, please contact Dr. Sheng Lu (shenglu@udel.edu).


Positions on Key Trade Issues: US Fashion Industry Association (USFIA) V.S. National Council of Textile Organizations (NCTO)


From left to right: Julia Hughes (president of USFIA), Auggie Tantillo (president & CEO of NCTO) and Robert Antoshak (Managing Director of Olah Inc., moderator)

In a panel discussion hosted by Kingpins on February 9, 2017, Julia K. Hughes, President of the United States Fashion Industry Association (USFIA), and Augustine Tantillo, President and Chief Executive of the National Council of Textile Organizations (NCTO) shared their respective perspectives on key trade issues facing the U.S. textile and apparel industry in 2017.

Trade and job creation in the United States

Julia Hughes: Discussion on the relationship of trade and jobs in the public is often misguided. We support U.S. manufacturing. But along the supply chain, from product development, sourcing, marketing to retailing, fashion brands and retailers have also created many well-paid non-manufacturing jobs in the United States. Study further shows that 70%-80% of the retail value of an imported clothing actually stays in the United States.

Auggie Tantillo: Pleased and excited to see the discussion on the possibility of bringing back/expanding manufacturing in the United States. Still the United States produces $65—70 billion worth of textiles annually, which support many manufacturing jobs in the sector.  The U.S. textile industry also makes around $2 billion investment annually (updating machines and equipment). We need to acknowledge the baseline value of manufacturing in the United States.  

Border Adjustment Tax(BAT)

Julia Hughes: BAT is a complicated issue. However, if the current BAT proposal is adopted, it will raise the retail price (meaning ordinary US consumers will have to pay more) and appreciate the U.S. dollar (meaning U.S. exports will get hurt). This is why USFIA along with 100+ companies and industry associations opposes any BAT.

Auggie Tantillo: NCTO strongly believes that updating the tax structure in the United States is long overdue. NCTO welcomes a serious look at the BAT proposal, since the United States is the only major economy in the world that does not adopt BAT. The United States doesn’t need to run such a high trade deficit. Instead, we need to make the tax structure supporting the U.S. manufacturing base.

North American Free Trade Agreement (NAFTA)

Julia Hughes: NAFTA is 20 years’ old and it can be improved. However, raising import tax (tariff) is NOT a good idea. NAFTA supports the Western-Hemisphere supply chain, which is critical for the U.S. textile and apparel industry. We need to defend this supply chain.  

Auggie Tantillo: NAFTA works and benefits its members on all sides of the border, including the United States. NCTO supports the continuation of NAFTA as well as to update and modernize the agreement as necessary.

Yarn-forward Rules of Origin (RoO)

Julia Hughes: Apparel is a global industry and apparel supply chain needs to be nimble. The yarn-forward RoO prevents apparel companies and retailers from fully enjoying the duty-free benefits under a free trade agreement (FTA) since not always the FTA region makes the needed products or their textile components. Exceptions to the yarn-forward rules such as the tariff preference level (TPL), provide necessary flexibility.  

Auggie Tantillo: The yarn-forward RoO has been a great success and we need to keep it (in existing and future trade agreements). The only things that need to be improved is the exception to the yarn-forward RoO (such as short supply list and trade preference level). RoO is supposed to keep benefits of a free trade agreement to its members only, yet these exceptions create loopholes and cause damages (to the U.S. textile industry).

On China

Julia Hughes: We need China, which still provides 40% of textiles and apparel consumed in the United States. It will be a disaster to trigger a trade war between the two countries.

Auggie Tantillo: We need to better help the Western-Hemisphere producers (in competing with textile and apparel made in China). China’s  40%+ market shares in the U.S. textile and apparel import market are not all based on its genuine competitiveness. Rather, China’s unfair trade practices such as IPR violation, government subsidy and unacceptable factory working conditions & environmental practices are of grave concerns.

Trans-Pacific Partnership (TPP)

Julia Hughes: TPP is not dead. On the other hand, countries around the world are actively negotiating new bilateral/regional free trade agreements. The United States doesn’t want to be left behind.

Auggie Tantillo: TPP is “in deep hibernation”, but trade agreement will never be really dead. It is still hopeful that TPP will come back later—but very likely to be in a different form, such as bilateral trade agreements. To be noted, many TPP members have already established bilateral/regional trade agreements with the United States.  

Discussion questions: 1) Why do you think Julia Hughes and Auggie Tantillo disagree on many trade issues? On which topics they actually agree with each other and why? 2) What’s your response to Julia Hughes and Auggie Tantillo’s comments on trade issues above? 3) Based on the panel discussion, why do you think textile and apparel companies need to care about trade policy? Please feel free to share your views.

Outlook 2017: Apparel Industry Issues in the Year Ahead

outlook

In January 2017, Just-Style consulted a panel of industry leaders and scholars in its Outlook 2017–Apparel Industry Issues in the Year Ahead management briefing. Below is my contribution to the report. Welcome for any suggestions and comments.

1: What do you see as the biggest challenges – and opportunities – facing the apparel industry in 2017, and why?

I see the uncertainty in the global economy will pose one of the biggest challenges facing the apparel industry in 2017. Apparel business is buyer-driven. A great number of studies have suggested that economic growth is by far the most effective and reliable predictive factor for apparel consumption. Unfortunately, it seems apparel companies have to deal with another year of economic volatility and weak demand in 2017. For example, according to the latest International Monetary Fund (IMF) forecast released in October 2016, global economic growth in 2017 is projected to only recover to 3.4 percent from 3.1 percent in 2016. There is no particular excitement among major apparel consumption markets either: outlook of the U.S. economy in 2017 is complicated by the strong U.S dollar, the Federal Reserve’s monetary policy as well as the uncertain trade and tax policy to be adopted by the new Trump administration; Economic growth in the EU region next year will continue to be hindered by the unknown fallout from UK’s referendum on leaving the EU, pervasive geopolitical uncertainties, high unemployment rates and the rising protectionist tendencies; Japan’s economic growth is projected to be as low as 1.0 percent in 2017 according to the Organization for Economic Co-operation and Development (OECD); And China’s economic growth in 2017 could slow again to 6.5 percent, which would be the slowest pace in more than 25 years. Reflecting the trend, we might see a stagnant growth or even a decline of global textile and apparel trade in 2017 as well.

Nevertheless, companies’ continuous investments on technology and innovation will create exciting new opportunities for the apparel industry. Particularly, growing areas in the apparel industry such as 3D printing, wearable technology, digital prototyping and e-commerce have made many “non-traditional” players now interested in fashion, including technology giants like Google and Apple. I think we can expect the apparel industry to become even more modern and high-tech driven in the years to come. The changing nature of the apparel industry will also increase demand for talents from an ever more diversified educational background, such as engineering, physical therapy and business analytics.

2: What’s happening with sourcing? How is the sourcing landscape likely to shift in 2017, and what strategies can help apparel firms and their suppliers to stay ahead?

One observation from me is that textile and apparel (T&A) supply chain is becoming more regional-based. For example, data from the World Trade Organization (WTO) shows that 91.4 percent of textiles imported by Asian countries in 2015 came from other Asian countries, up from 86.6 percent in 2008. This suggests that Asian countries togetherare building a more integrated T&A supply chain. Likewise, in 2015 close to 90 percent of apparel exported by North, South and Central American countries went to the United States and Canada and 81 percent of apparel exported by EU countries went to other EU countries too. To be noted, all of these three major T&A supply chains are facilitated by respective free trade agreements in the region such as the North American Free Trade Agreement (NAFTA), ASEAN–China Free Trade Area (ACFTA) and of course the common market enjoyed by the EU members. On the other hand, fashion brands and apparel retailers often use the Western-Hemisphere supply chain and EU-based supply chain as a supplement to the Asia-based supply chain for more fashion-oriented or time-sensitive items. I think such a dual-track sourcing strategy will continue in 2017.

Related, I think supply chain management will play a growing important role helping apparel companies control sourcing cost, improve speed to market and better meet consumers’ demand in 2017. An interesting phenomenon revealed by the 2016 U.S. Fashion Industry Benchmarking Study released by the U.S. Fashion Industry Association is that around 30 percent of respondents say they plan to consolidate rather than diversify their sourcing base in the next 2 years. As one respondent commented, “(Our) focus right now is really finding efficiencies and maximizing productivity in the supply chain. While we won’t necessarily move out of any countries, we are consolidating the base within regions.”

Last but not least, I think in 2017 apparel companies will continue to give more weight to sustainability and social responsibility in their sourcing decisions. Building a more transparent and sustainable supply chain is an irreversible trend in the apparel industry. 

3: What should apparel firms be doing now if they want to remain competitive into the future? What will separate the winners from the losers?

To remain competitive into the future, apparel companies need to be prepared to change and be willing to try something new. Indeed, revolution is coming for the apparel industry, including the way products are made and sourced (example: 3D printing and various digital manufacturing tools), how consumers shop (example: the see-now-buy-now trend) and where and how to sell (example: the booming e-commerce and omni-channel retailing). In the past, small and medium sized companies (SME) were regarded more vulnerable than big players in the apparel industry for business survival.  However, nowadays, without embracing the spirit of innovation and entrepreneurship, even large companies can quickly become “dinosaurs” and find their business struggling. 

4: What keeps you awake at night? Is there anything else you think the apparel industry should be keeping a close eye on in the year ahead? Do you expect 2017 to be better than 2016, and why?

One thing that keeps me awake at night as a professor is what needs to be changed or updated in our curriculum to better prepare our students for the needs of the apparel industry. Fashion programs like us directly prepare future professionals for the fashion apparel industry. This also means we are not immune to the big shift in the industry either. For example, our course offerings currently include textile science, product development, merchandising, branding and sourcing and trade. But in addition to these conventional topics, what else should be added to the curriculum? What new skill setsor knowledge points will be highly expected by the apparel industry for our students in the future? Personally I think talent training is a critical area that the apparel industry and our fashion educational programs can and should form closer partnership. And the outcomes will be mutual beneficial too.

Trade policy is another area that keeps me awake at night. Trade policy matters for the apparel industry because it affects the quantity, price and availability of products in the market. Specifically, in 2017 I will be watching closely about the following trade agendas: 1) the WTO Trade Facilitation Agreement (TFA), which is nearing entering into force. TFA aims to make customs and border procedures easier, speed up the passage of goods between countries and lower cost of trade.

2) negotiation of the Regional Comprehensive Economic Partnership (RCEP). In 2015, the sixteen RCEP members altogether exported $369 billion worth of textile and apparel (50% of world share) and imported $124 billion (34% of world share). Since the Trans-Pacific Partnership (TPP) won’t be implemented anytime soon, RCEP has the potential to influence and reshape the T&A supply chain in the Asia-Pacific region.

3) a possible revision of the North American Free Trade Agreement (NAFTA). NAFTA is a critical factor facilitating and maintaining the Western-Hemisphere textile and apparel supply chain. A recent study of mine shows that ending the NAFTA would significantly hurt apparel manufacturing in Mexico and textile manufacturing in the United States, largely because apparel “Made in Mexico” today often contains yarns and fabrics “Made in USA”.

4) Trans-Pacific Partnership (TPP) and Trans-Atlantic Trade and Investment Partnership (T-TIP). Although many people think these two agreements are dead, I disagree. TPP and T-TIP are NOT conventional free trade agreements (FTAs) that deal with tariffs and non-tariff barriers only. Just like why we need traffic rules, TPP and T-TIP address our needs to update international trade regulations on 21st century trade agendas such as digital trade, state-owned enterprises, labor and environmental standards, small and medium sized enterprises and trade related investment. On the other hand, both TPP and T-TIP still have a solid and broad supporting base, which includes the fashion apparel industry. If trade politics is why TPP and T-TIP are in trouble, for the same reason, we should expect a reversal of the fate of these two agreements when time arrives. Plus, we should never underestimate the creativity and wisdom of trade policymakers.

Sheng Lu

New USCBC Study Suggests Overall Positive Impacts of China on the US economy

oe-cover_0

Although the trade relationship with China is often blamed for causing job losses in the United States, a new study prepared for the U.S.-China Business Council (USCBC) by Oxford Economics suggests overall positive impacts of China on the US economy. According to the study:

  • China has grown to become the third-largest destination for American goods and services, only after Mexico and Canada. China purchased $165 billion in goods and services from the United States in 2015, representing 7.3 percent of all US exports and about 1 percent of total US economic output. By 2030, US exports to China are projected to rise to more than $520 billion annually.
  • The US-China trade relationship supports roughly 2.6 million jobs in the United States. Specifically, US exports to China directly and indirectly supported 8 million new jobs in 2015.
  • The reported gross US trade deficit with China is overstated and somewhat misleading. As China has become an integral part of the global manufacturing supply chain, much of its exports are comprised of foreign-produced components delivered for final assembly in China. If the value of these imported components is subtracted from China’s exports, the US trade deficit with China is reduced by half, to about 1 percent of GDP—about the same as the US trade deficit with the European Union.
  • Additionally, “Made in China” lowered prices on consumer goods in the United States. As estimated, US consumer prices are 1 percent to 1.5 percent lower because of Chinese imports — trade with China saved each American household up to $850 in 2015. Given the fact that hourly labor costs in the textile industry were $2.65 in China in 2014 compared with $17.71 in the United States, the report argues that replacing Chinese imports of textiles and clothing with US-manufactured products would significantly raise US consumer prices.

In terms of the textile and apparel (T&A) sector, the report suggests that:

  • The rising U.S. imports from China mostly represent China’s displacement of imports from other countries and regions: China has been squeezing out traditional apparel manufacturers such as Mexico, Hong Kong, and Taiwan.
  • Meanwhile, textile and apparel manufacturing is one of the very few sectors that observe a parallel pattern of rising imports from China and declining gross value added in the United States since 2000. In comparison, over the same period, other sectors that experienced the most rapid growth in Chinese imports are also the sectors where US businesses have seen the strongest growth.

The report is available HERE

Made in the USA Textiles and Apparel:Facts and Future

The presentation is the outcome of Jillian Luetje‘s honor project in FASH455 (Fall 2016). In the project, Jillian explored the facts and future of “Made in USA” textile and apparel based on her research of existing literature and interviews with U.S. trade officials. The presentation intends to help the audience (especially those new to the area of textile and apparel trade and trade policy) have a basic understanding of the topic.  

Key findings:

  • Textile and apparel manufacturing in the USA is NOT totally gone.
  • The U.S. textile industry in particular relies on the Western Hemisphere supply chain and related free trade agreements
  • Made in the USA apparel is not going to increase any time soon.

Welcome for any comments and suggestions!

Outlook for Trade Policy in the Trump Administration and Impact on the Textile and Apparel Industry: A Summary of Views from Experts

bn-qb709_1001tr_m_20161002000431

TPP is in trouble, but NOT dead

David Spooner, Partner at Barnes & Thornburg LLP, Former Chief Textile & Apparel Negotiator at the Office of the U.S. Trade Representative, and Former Assistant Secretary of Commerce for Import Administration: “it will be a tough road to pass it (the Trans-Pacific Partnership, TPP) during the Trump Administration…However, there may be opportunities for the (fashion) industry if Trump brings new faces to the Office of the U.S. Trade Representative (USTR) and takes a fresh look at trade agreements.” Source: https://www.usfashionindustry.com/news/off-the-cuff-newsletter/2803-recap-28th-apparel-importers-trade-transportation-conference

Jeffrey J. Schott, Senior Fellow of the Peterson Institute for International Economics: “What’s the future for TPP? Most likely, Trump will simply not implement it. Without US participation, the pact cannot definitively enter into force. It’s death by malign neglect.” “But the 11 other TPP countries may not sit idly on the sidelines waiting for US ratification. Instead, they could agree among themselves to extend the TPP benefits to each other on a provisional basis, leaving the door open for US participation in the future. If the United States subsequently ratifies the TPP, the pact would then enter into force on a permanent basis.” Source: https://piie.com/blogs/trade-investment-policy-watch/tpp-could-go-forward-without-united-states

Steve Warner, President/CEO BeaverLake6 Group LLC, former President and CEO of the Industrial Fabrics Association International (IFAI): “TPP was dead going forward. TPP isn’t actually bad for the technical textiles industry except in a few instances. The real bad culprit, though, is the passage of the Trade Promotion Authority (TPA), which I opposed when it was being hotly debated in 2015. TPA gave no wiggle room for lawmakers to make even slight changes in the TPP when it was presented by the Obama administration that could at least mollify a representative’s constituents. You couldn’t just like parts of the agreement; you had to like all of it. Thus, you were either with it entirely or have to go against it. It proved to be safer to go against it. As for T-TIP, it was going to be a tough deal to conclude when the European Union insisted a primary objective for them was the elimination of the Berry Amendment protection for US domestic manufacturers” Source: http://www.beaverlake6.com/in-my-opinion/

Face uncertainties but with hope

Michael Singer, vice president of customs compliance at Macy’s and chairman of the U.S. Fashion Industry Association (USFIA): “I do see some opportunities believe it or not, and I had to struggle really hard to come up with something positive. From the regulatory basis, there may be an opportunity for some easing of government laws and mandates.” “One of the key issues we now face is how the administration and Congress will handle trade issues in 2017… We all know how important trade and the access to world markets is in our ability to provide our customers the choices and products they expected, and yet there is no doubt the protectionist sentiment in our country is at historic levels. USFIA will be doing our best to make sure that this remains a top priority and we clearly communicate the importance and benefit of trade to U.S. consumers and the U.S. economy.” Source: http://wwd.com/business-news/government-trade/donald-trump-on-trade-taxes-and-regulations-10702130/

 Julia Hughes, President of the U.S. Fashion Industry Association (USFIA): “A lot of folks were surprised by the (election) outcome… We can see we have our work cut out for us…We’re going to be dealing with a lot of unknowns even with the continuation of a Republican Congress.” Source: http://www.just-style.com/analysis/tpp-is-not-going-to-happen-in-a-trump-administration_id129272.aspx

Daniel J. Ikenson, director of Cato’s Herbert A. Stiefel Center for Trade Policy Studies: “If he (Trump) is able to expand and diversify the pool of people advising him, there is a reasonable chance that President Trump’s actions will be less bellicose than his rhetoric has been. After all, as someone who wants to make America “great again,” President-elect Trump will want the policies implemented by his administration to help grow the economy. Trade agreements have succeeded in that regard and, in addition to the TPP, there are plenty of countries and regions willing to partner, including the European Union and the United Kingdom (separately), and plenty of alternative negotiating platforms for accomplishing trade and investment liberalization. ” Source: https://www.cato.org/blog/shifting-gears-contemplate-trumps-trade-policies

David Spooner, Partner at Barnes & Thornburg LLP, Former Chief Textile & Apparel Negotiator at the Office of the U.S. Trade Representative, and Former Assistant Secretary of Commerce for Import Administration: “I think there’s some opportunity in a Trump administration…Assuming chaos provides opportunities, and if Trump brings in new faces to USTR, it might give us an opportunity to do new things in trade. We’ve been screwed by the yarn-forward rule for decades. Maybe there’s an opportunity to do things, even if it’s around the margins.” Source: https://sourcingjournalonline.com/tpp-ttip-wont-happen-trump-administration/

Robert Antoshak, managing director at Olah Inc.: “First, (Trump) he’ll let TPP, the Trans-Pacific Partnership) just wither on the vine. It’s pretty easy to kill TPP by doing nothing; Congress hasn’t voted on it yet. Next, he may activate the escape clause in NAFTA (the North American Free Trade Agreement with Canada and Mexico), which gives signatories a six-month window to exit the agreement. During that time, he could use an exit for political gain in the media – imagine the headlines about the US pulling out of NAFTA – but in reality, he could use the time to renegotiate portions of the agreement. And then there’s T-TIP, the Transatlantic Trade and Investment Partnership free trade deal with the EU. Personally, I’m going to keep a close eye on relations between the White House and 10 Downing Street. The commonalities between the forces supporting Brexit and Trump are all too similar. Why negotiate with all of the EU, when it may be more politically expedient for Trump to negotiate a separate economic-trade deal with Theresa May?” “I am confident that he (Trump) will attempt to alter the global hierarchy. One way of changing the system will be to focus on trade. He can make tactical adjustments to trade policy that will not only give him the front-page news he craves, but will enact the kind of systemic change upon which he ran for president.” Source: http://www.just-style.com/comment/trump-trade-policy-who-knows-what-hell-do_id129295.aspx

US-China Trade War? Keep a close watch

Augustine Tantillo, president and chief executive officer of the National Council of Textile Organizations (NCTO): “(I) would be surprised if Trump does not take some steps to crack down on currency devaluation, particularly as it relates to China.” Source: http://wwd.com/business-news/government-trade/donald-trump-on-trade-taxes-and-regulations-10702130/

 Chad Bown, Senior Fellow of the Peterson Institute for International Economics: “What he (Trump) has said is that they (China) manipulate their currency and he has threatened to impose tariffs upwards of 45%. The concerns with doing that is that we (USA) do have a trade agreement with 163 other economies of the world, the WTO. China is a part of that and by doing that (imposing tariffs upwards of 45%) unilaterally, would be violating our commitments, legal commitments to our trading partners under that deal and China would be authorized and probably would retaliate and strike back and probably do the same thing against the United States which would mean U.S. companies and exporters that make goods and agricultural products, and send those to China would suffer as a retaliatory response.” Source: https://www.c-span.org/video/?417891-3/washington-journal-chad-bown-trade-policy-trump-administration

Textile and apparel industry needs NAFTA 

Steve Lamar, executive vice president for the American Apparel & Footwear Association(AAFA): “It is well established that CAFTA and NAFTA are critical for the U.S. textile and apparel industry. The things we have continued to argue is how to find ways to make it better… NAFTA was negotiated when there were no other free-trade agreements and the world was surrounded by quotas and rules of origin that catered to the United States. But the industry has evolved.” “Trump will renegotiate NAFTA and is only threatening to abrogate the free-trade accord… Trump likes to build up leverage to get the best possible deal, and he can view trade with that same lens.” Source: https://www.apparelnews.net/news/2016/nov/17/how-would-end-nafta-affect-la-apparel-industry/

Augustine Tantillo, president and chief executive officer of the National Council of Textile Organizations (NCTO): “there will be a ‘level of caution,’ when it comes to renegotiating NAFTA. This agreement has been in place for a while and it would be clearly disruptive to simply walk away from it at this point.” Source: http://wwd.com/business-news/government-trade/donald-trump-on-trade-taxes-and-regulations-10702130/

Leonie Barrie, Managing editor of Just-Style: “Will a Trump administration revisit NAFTA? Such a prospect is a concerning one because NAFTA’s free trade framework with Mexico has been at the heart of many sourcing strategies in North America. The US exported $6.5bn of apparel and textiles to Mexico last year and, in turn, Mexico shipped $4.2bn to the US. Earlier this year executives told just-style that if Trump went ahead with threats to build a 3,200-kilometre fence on the Mexican-American border to stem immigration, it could cut $2.2bn or 20% of the $11bn in US-Mexican textiles and apparel trade in its first year.” Source: http://www.just-style.com/comment/what-might-a-trump-presidency-mean-for-apparel_id129260.aspx

Please feel free to respond to any comments above or leave your thoughts.