FASH455 Video Discussion: Textiles, Trade & National Security: A Conversation with Parkdale Mills COO Davis Warlick

For FASH455 class: When writing your blog comment, consider addressing the following aspects:

  • #1 Based on the video, how do CAFTA-DR and USMCA help shape the Western Hemisphere textile and apparel supply chain?
  • #2 Based on the video, what do you see as the main opportunities for textile and apparel nearshoring or reshoring in the Western Hemisphere? How about the key bottlenecks (e.g., cost, infrastructure, labor, sustainability, or trade policy)?
  • #3 The speaker argues for a sectoral trade policy for textiles and apparel rather than broad “free trade.” What is your evaluation?
  • #4 How does the video help deepen your understanding of the complex economic and non-economic factors related to textile and apparel nearshoring and reshoring in the Western Hemisphere?

FASH455 Video Discussion: Vietnam Garment Factory Tour (updated: October 2025)

About the factory

  • The factory is a foreign direct investment (FDI) operation in central Vietnam specializing in ODM (Original Design Manufacturing) — producing ready-made designs that can be customized for private labels. Specific products include sportswear, casual wear, workwear, and uniforms.
  • The factory hires about 500 workers, and it aims to increase the size to 700-1000 workers, which was the pre-COVID level. The monthly pay averaged about $400.
  • The garment factory mainly exports to the U.S., Europe, and Brazil. The factory can do both full package sourcing (i.e., manages the entire production process, from procuring materials to manufacturing, quality control, and packaging—delivering finished goods ready for export) and CMT sourcing (i.e., cut make and trim–buyer provides the materials and designs, while the supplier only performs garment assembly, sewing, and finishing).
  • The factory mostly uses woven fabrics, and they are mainly sourced from China and Europe. Other sources include Taiwan, Thailand, and Malaysia. Some fabrics are Oeko-Tex certified, given the growing importance of using sustainable materials.
  • To meet the rules of origin requirements under free trade agreements (FTAs), such as the EU-Vietnam FTA, Vietnam is making efforts to enhance its local textile manufacturing capability.
  • To meet the clients’ needs, the factory has received several certifications related to social compliance and sustainability, including WRAP, BSCI, and ISO 9000.
  • Textile waste is partly sold or donated (e.g., blankets and jackets for local communities).

For FASH455 class: When writing your blog comment, consider addressing the following aspects:

  • How does the video help you understand the complexity of apparel sourcing?
  • Based on the video, what is your evaluation of the strengths of the factory as an apparel sourcing base for US fashion companies? Any specific area in which the factory can be improved?
  • If you have the chance to visit a garment factory, what would you focus on evaluating and why?

Additional reading: Vietnam overtakes China as US’s top apparel supplier (FDi intelligence, Financial Times, October 8, 2025)

FASH455 Exclusive Interview with Nicole Bivens Collinson, Managing Principal and Practice Leader of International Trade and Government Relations, Sandler, Travis & Rosenberg, P.A.

About the interview

When learning about apparel sourcing and trade, our students often notice how much they are affected by trade policies and regulations—from tariffs, and something called “de minimis” to UFLPA. These issues are not only critical for fashion companies but can also be quite technical.

We are fortunate to have Nicole Bivens Collinson, Managing Principal and Practice Leader of International Trade and Government Relations of Sandler, Travis & Rosenberg, P.A. (ST&R), a true expert in trade policy and the legal aspects of trade, join us. In the interview, Nicole clarified key U.S. trade rules and provided valuable insights into their apparel sourcing and trade implications, including:

  • What is a tariff, and why is it a big issue for US fashion brands and retailers?
  • Why have the so-called IEEPA “reciprocal tariffs” imposed by the Trump administration so far this year raised so many concerns?
  • What does the term “transshipment” mean in international trade? And why did this issue emerge in the context of higher tariffs this year?
  • What is the “20% US content” rule and its implications for fashion companies?
  • What is “tariff engineering”? Is it legal or illegal? How have fashion companies used it to mitigate the tariff impacts, potentially?
  • What is de minimis? Why was it created, and then became controversial? Since the “de minimis” rule was officially terminated recently, what impacts could we expect now? 
  • What is the Uyghur Forced Labor Prevention Act (UFLPA) and what does it aim to do? How has the implementation of the UFLPA affected U.S. fashion companies’ apparel sourcing?
  • For fashion students interested in working in trade compliance, trade policy, or the legal aspects of the fashion industry, what steps can they take to get started?

About Nicole Bivens Collinson

Nicole Bivens Collinson is the Managing Principal and Practice Leader of International Trade and Government Relations with Sandler, Travis & Rosenberg, P.A. (ST&R). Nicole is a commentator on trade matters on MSNBC, NPR, and BBC the producer of the Two Minutes in Trade podcast.

Nicole has nearly 40 years of experience in government and public affairs and lobbying. She prepares countries, companies, and associations for negotiations with the United States on free trade agreements, trade and investment agreements, labor disputes, and preferential trade programs.

Prior to joining ST&R, Nicole served as assistant chief negotiator for the Office of the U.S. Trade Representative, responsible for the negotiation of bilateral agreements with Latin America, Eastern Europe, Southeast Asia, the Sub-Continent, and Africa. She also served as a country specialist in the International Trade Administration at the Department of Commerce, where she was responsible for the preparation of negotiations on specific topics between the U.S. and Latin America, Eastern Europe, China, and Hong Kong as well as the administration of complex textile agreements.

Nicole holds a master’s degree in international relations from The George Washington University and a triple bachelor’s degree in political science, European studies, and French from Georgetown College. She also studied at the Université de Caen in France.

Nicole is past chair of the Women in International Trade Charitable Trust, past president of Women in International Trade, an advisory board member of America’s TradePolicy.com, treasurer and board member of the Washington International Trade Association, and a member of the Washington International Trade Association Foundation and Women in Government Relations. She serves on the board of trustees for Georgetown College and is the past executive director for the U.S. Hosiery Manufacturers Coalition, the U.S. Apparel Industry Coalition, and the U.S. Sock Distributors Coalition.

About Katie Yasik (moderator)

Katie Yasik is a master’s student & graduate instructor in Fashion and Apparel Studies (FASH) at the University of Delaware (UD). Katie graduated from UD & FASH with a B.S. in Fashion Design and Product Innovation & Sustainable Apparel minor. Driven by her strong passion for sustainability, she interned with the Worldwide Responsible Accredited Production (WRAP) in Spring 2024.

FASH455 Exclusive Interview with Shannon Brady, Import and Product Operations Manager at LoveShackFancy

About the interview

In this exclusive FASH455 interview, we are thrilled to welcome Shannon Brady, Import and Product Operations Manager at LoveShackFancy and a proud UD & FASH alum, to share her experiences navigating global apparel sourcing for fashion students. Shannon offered first-hand insights into the latest sourcing trends in the fashion apparel industry and reflected on her career journey in sourcing and trade. Specific topics covered in the interview include:

  • Apparel sourcing process in general
  • The current U.S. tariff situation and its impacts on apparel sourcing
  • Why do apparel sourcing orders still mostly go to Asia?
  • Outlook for apparel on-shoring and near-shoring
  • Sustainability and sourcing in practice
  • Career opportunities in apparel sourcing and trade

Note: This interview is for informational purposes only and reflects Shannon’s personal perspectives. What was shared in this interview should not be taken as, and does not constitute, official policy, position or guidance from LoveShackFancy.

About Shannon Brady

Shannon Brady is the Import and Product Operations Manager at LoveShackFancy. With over four years of experience in product development and sourcing, she specializes in driving vendor performance, optimizing supply chains, and leading cross-functional initiatives. Before her current role, she worked for the U.S. Fashion Industry Association in Washington, D.C., and then joined Party City as a Sourcing Operations Manager.

Shannon graduated magna cum laude from the University of Delaware with a B.S. in Fashion Merchandising. She was a 2018 UD summer scholar, and her co-authored case study Managing the used clothing trade  was published in the Bloomsbury Fashion Business Cases.

About Emilie Delaye (moderator)

Emilie Delaye is a master’s student & graduate instructor in Fashion and Apparel Studies at the University of Delaware, with a specific interest in supply chain, global sourcing, and sustainability. 

New USITC Report: HELP/HOPE Program Expiration Would Significantly Hurt Haiti’s Apparel Exports to the U.S.

In a newly released study, the U.S. International Trade Commission (USITC) suggests that if the HOPE (Haitian Hemispheric Opportunity through Partnership Encouragement) Acts and HELP (Haiti Economic Lift Program Act of 2010) are not renewed soon after their expiration on September 30, 2025, it could severely impact Haiti’s apparel exports to the U.S. further. Specifically: 

First, the apparel sector matters significantly for Haiti. Apparel accounted for over 90% of U.S. merchandise imports from Haiti. The apparel sector also provided over 60,000 jobs in Haiti in 2021, though this number declined to nearly 22,000 by 2024 due to political instability and security concerns. Further, according to the USITC report, “Haiti’s apparel production primarily consists of basic apparel items such as T-shirts and cotton goods. Cotton knit T-shirts and manmade fiber knit T-shirts were the top products imported to the United States during 2022–24.”

Second, the HOPE and HELP programs have been critical in supporting Haiti’s apparel exports to the U.S. Data from the Office of Textiles and Apparel (OTEXA) shows that of the total $549 million U.S. apparel imports from Haiti in 2024, about 66% claimed the duty-free benefits under HOPE/HELP.

While Haiti’s apparel exports to the US could also enjoy preferential duty benefits under other U.S. trade preference programs, particularly the Caribbean Basin Economic Recovery Act (CBERA) and its enhanced version–the Caribbean Basin Trade Partnership Act (CBTPA), the apparel rules of origin under HOPE/HELP were far less restrictive. For example, whereas CBTPA requires Haiti to use U.S.-made yarns and fabrics, HOPE/HELP allows Haiti to use textile input from any country, as long as other eligibility criteria (including value-added or quota limits) are met.

Third, related to the previous point, without HOPE/HELP, Haiti’s apparel exports to the U.S. could face significant challenges. The USITC report noted that “The expiration of the HOPE/HELP program at the end of September 2025 would significantly reduce the competitiveness of textile and apparel exports from Haiti to the United States by removing key duty-free access provisions.”

Other studies cited by the USITC report argued that “compliance costs of preferential trade agreements are associated with rules of origin requirements, which can be cumbersome, especially for small firms in developing countries…if rules of origin are not ‘sufficiently simple and transparent,’ their compliance costs (may) exceed their benefits.”

Fourth, the expiration of HOPE/HELP could complicate the regional textile and apparel supply chain that involves the U.S. textile input, Haiti, and the Dominican Republic. Specifically, in 2024, about 28.8% of U.S. apparel imports from Haiti were under CBTPA’s “Knit apparel from regional or U.S. fabric from U.S. yarn” or “T-shirts made of regional fabric from U.S. yarn” provisions. This percentage rose to a new high of 32.5% in the first seven months of 2025 (was 23.7% over the same period in 2024). As the USITC report noted that “U.S. yarn is used in downstream fabric production in the Dominican Republic-Central America FTA (CAFTA-DR) countries, which is then used in apparel production in Haiti. Haiti’s preferences further allow for integrated textile and apparel trade with the Dominican Republic, with many inputs imported and finished goods exported through the country.”

However, the report also concluded that “although Haiti would still be able to take advantage of the CBTPA provisions, without the HOPE/HELP program, CBERA exports of textile products are likely to decline sharply, as producers face increased production costs relative to other U.S. trading partners.” In other words, “forcing” Haiti to rely exclusively on U.S. yarns could make its apparel too costly compared with Asia suppliers or CAFTA-DR members, leading U.S. fashion companies to reduce or even withdraw sourcing from Haiti.

(note: due to its technical nature, this post is not open for FASH455 discussion)

Summary by Sheng Lu

Patterns of U.S. Apparel Imports (updated September 2025)

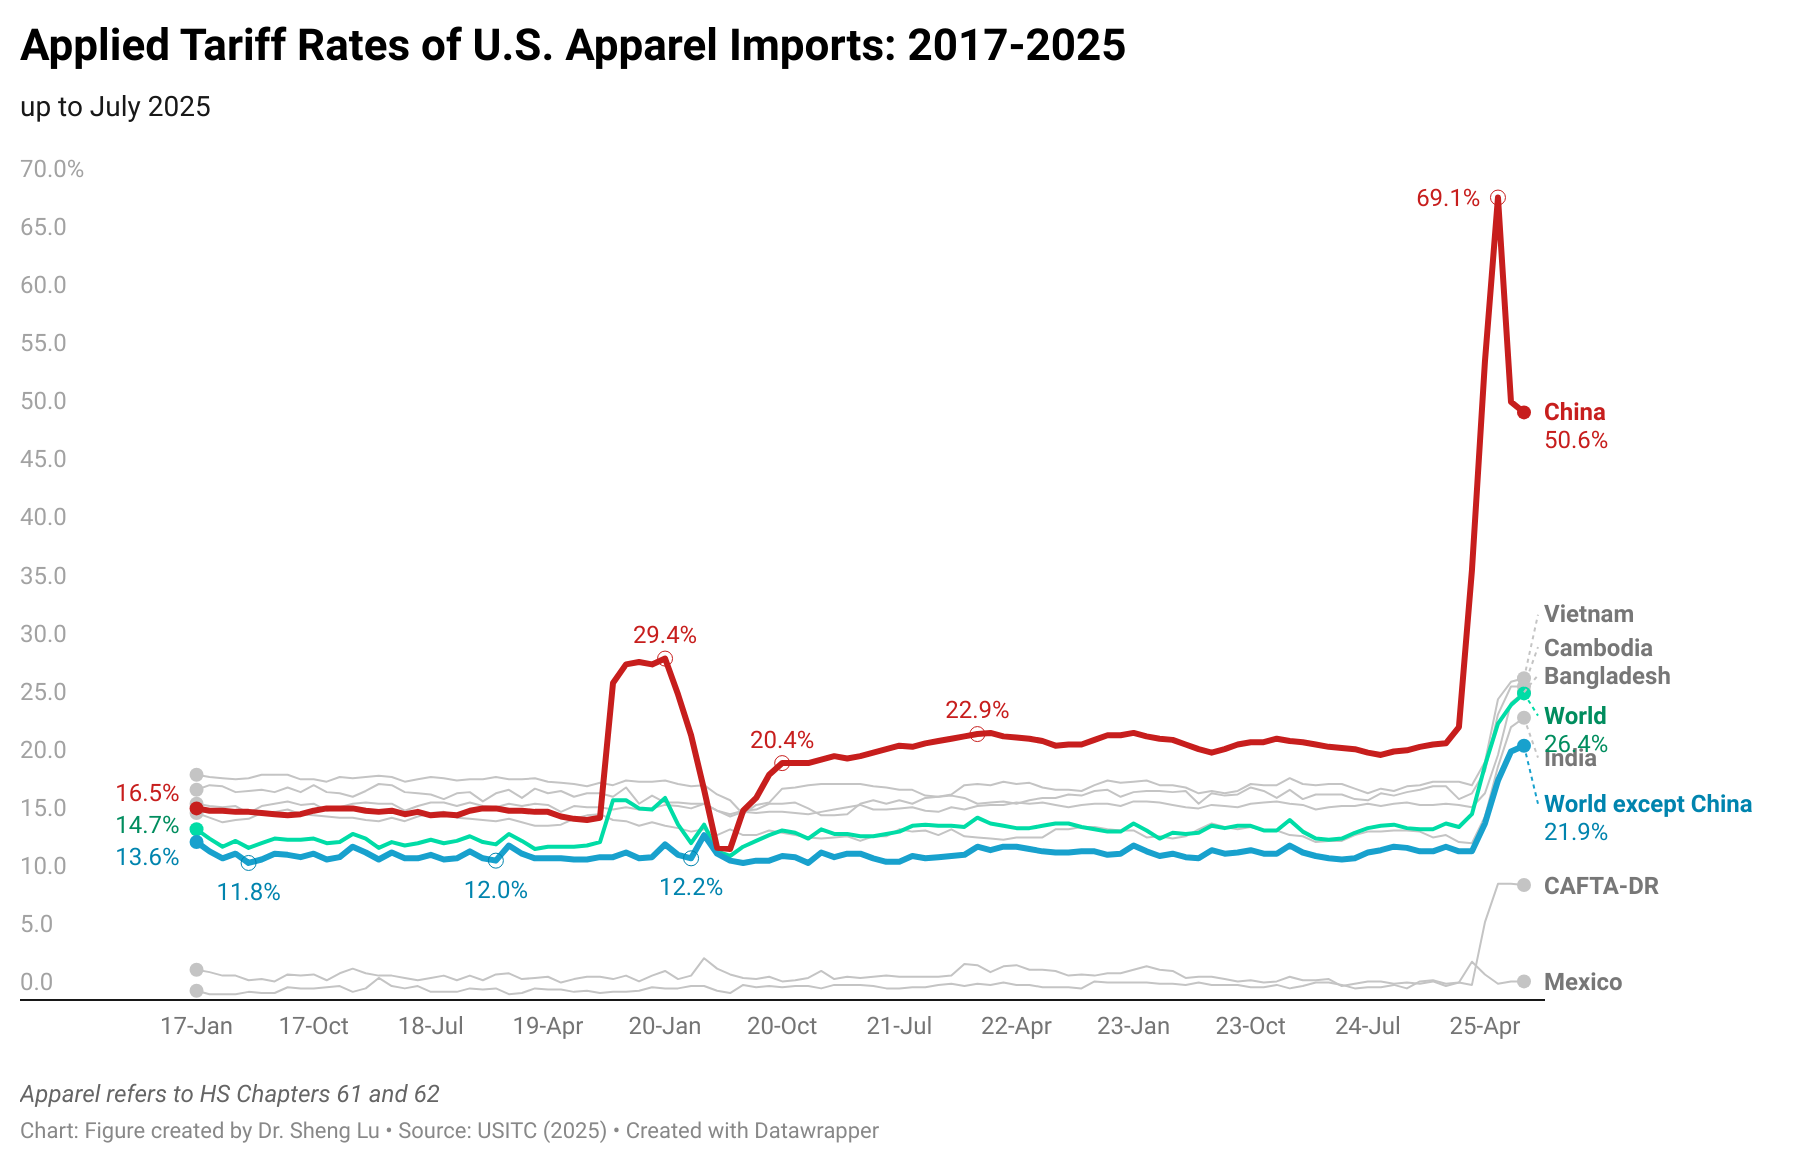
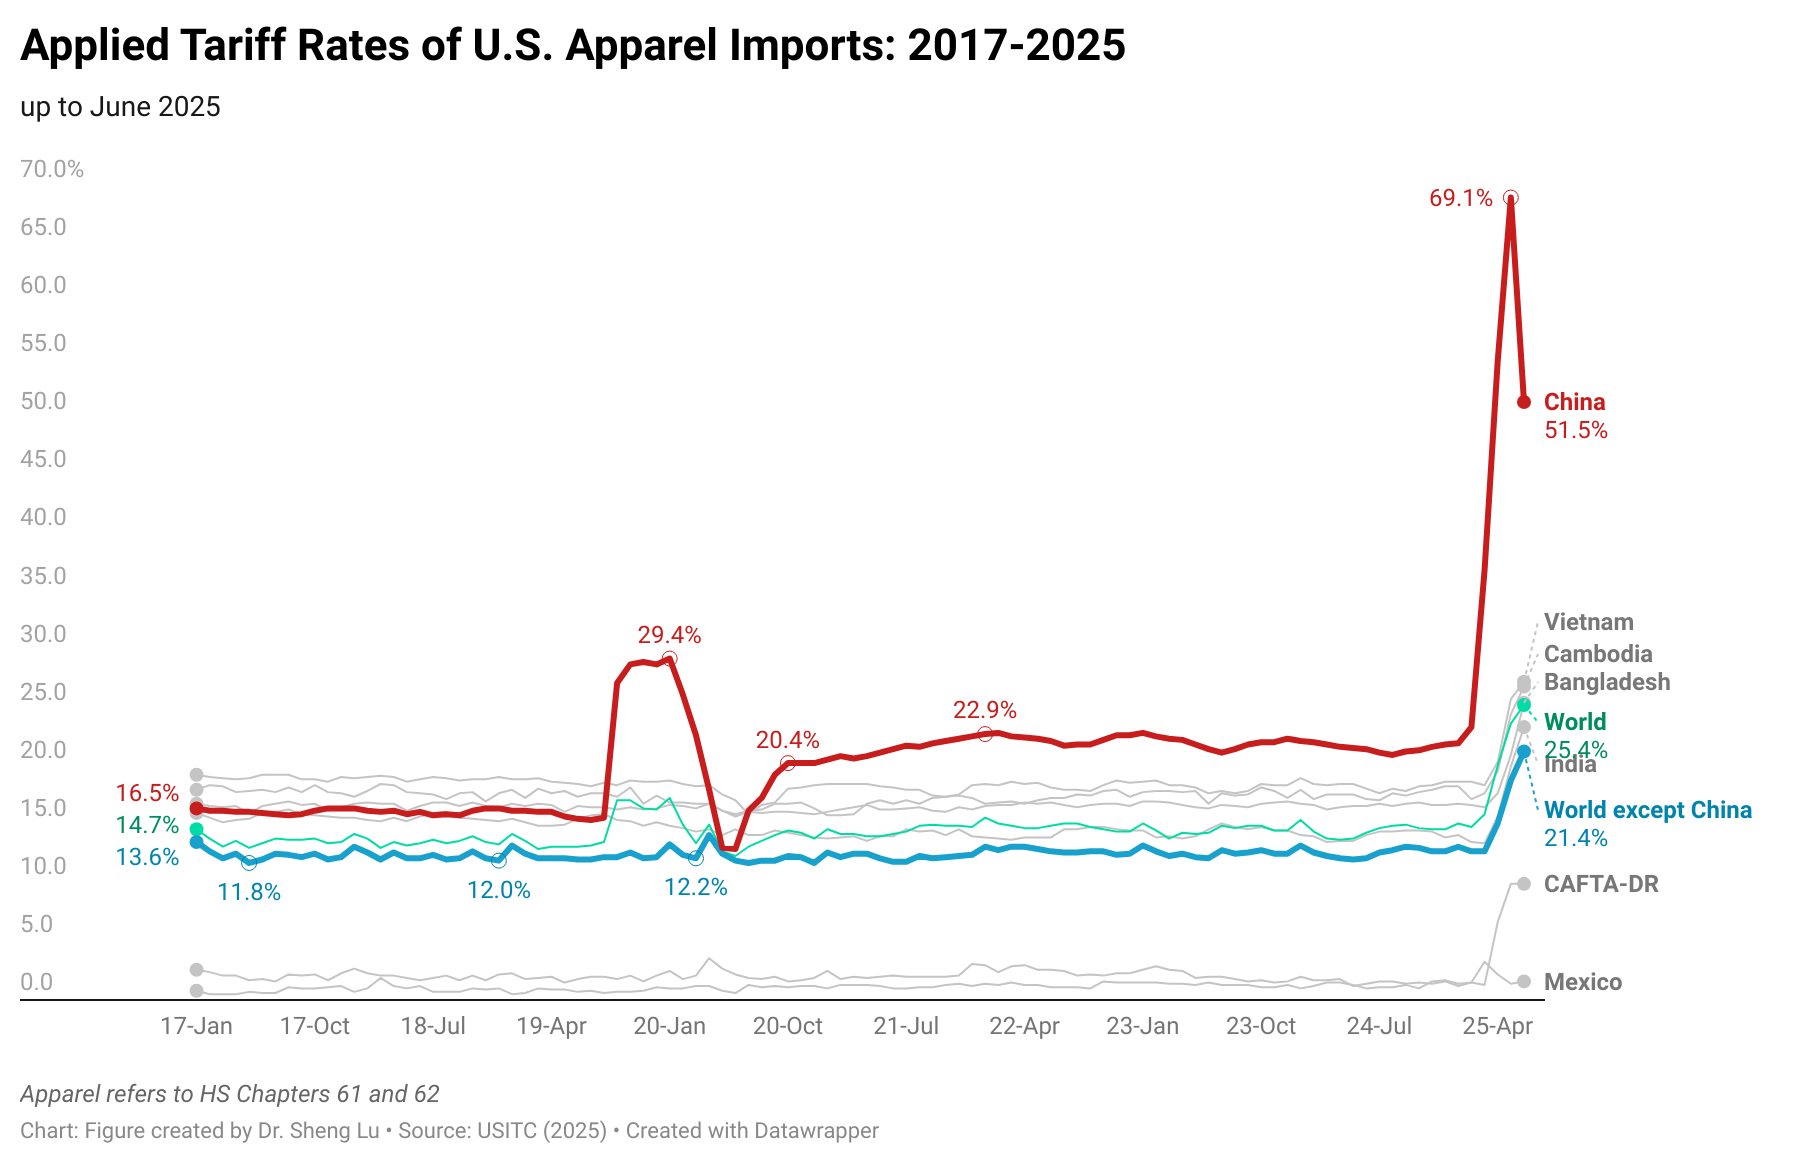
First, as a result of the IEEPA reciprocal tariff, the average tariff rate for U.S. apparel imports (HS Chapters 61 and 62) reached 26.4% in July 2025, marking a new high in decades (note: was 25.4% in June, 23.8% in May and 20.2% in April 2025), and a substantial increase from 14.7% in January 2025, prior to Trump’s second term. Even apparel imports from traditional U.S. free trade agreement partners, such as CAFTA-DR members, now have to be subject to about 10% applied tariffs. And apparel imports from Mexico still enjoyed a relatively low 1.6% tariff rate in July 2025. [Check the applied US apparel import tariff rate here]

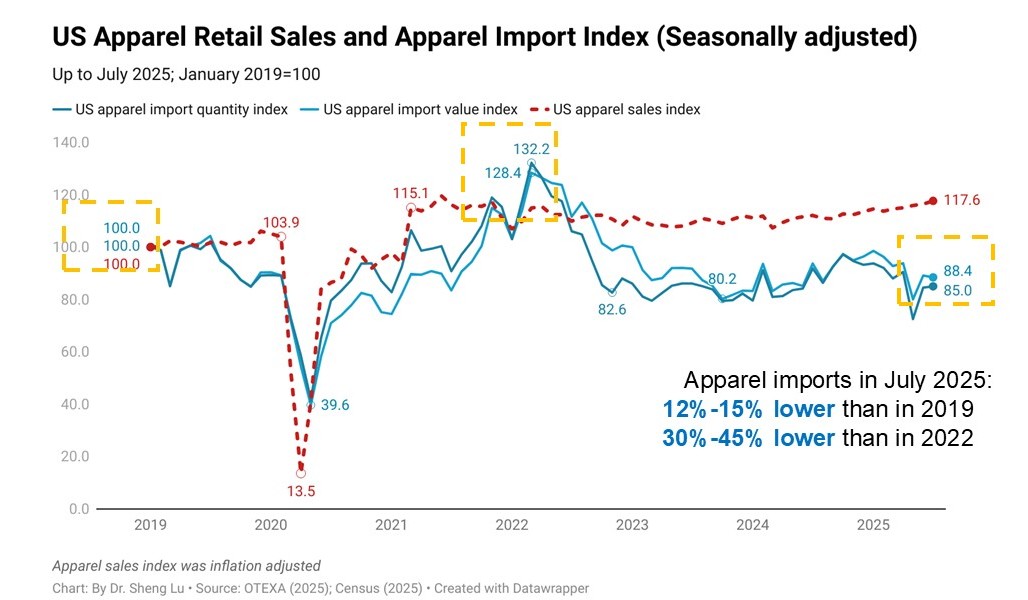
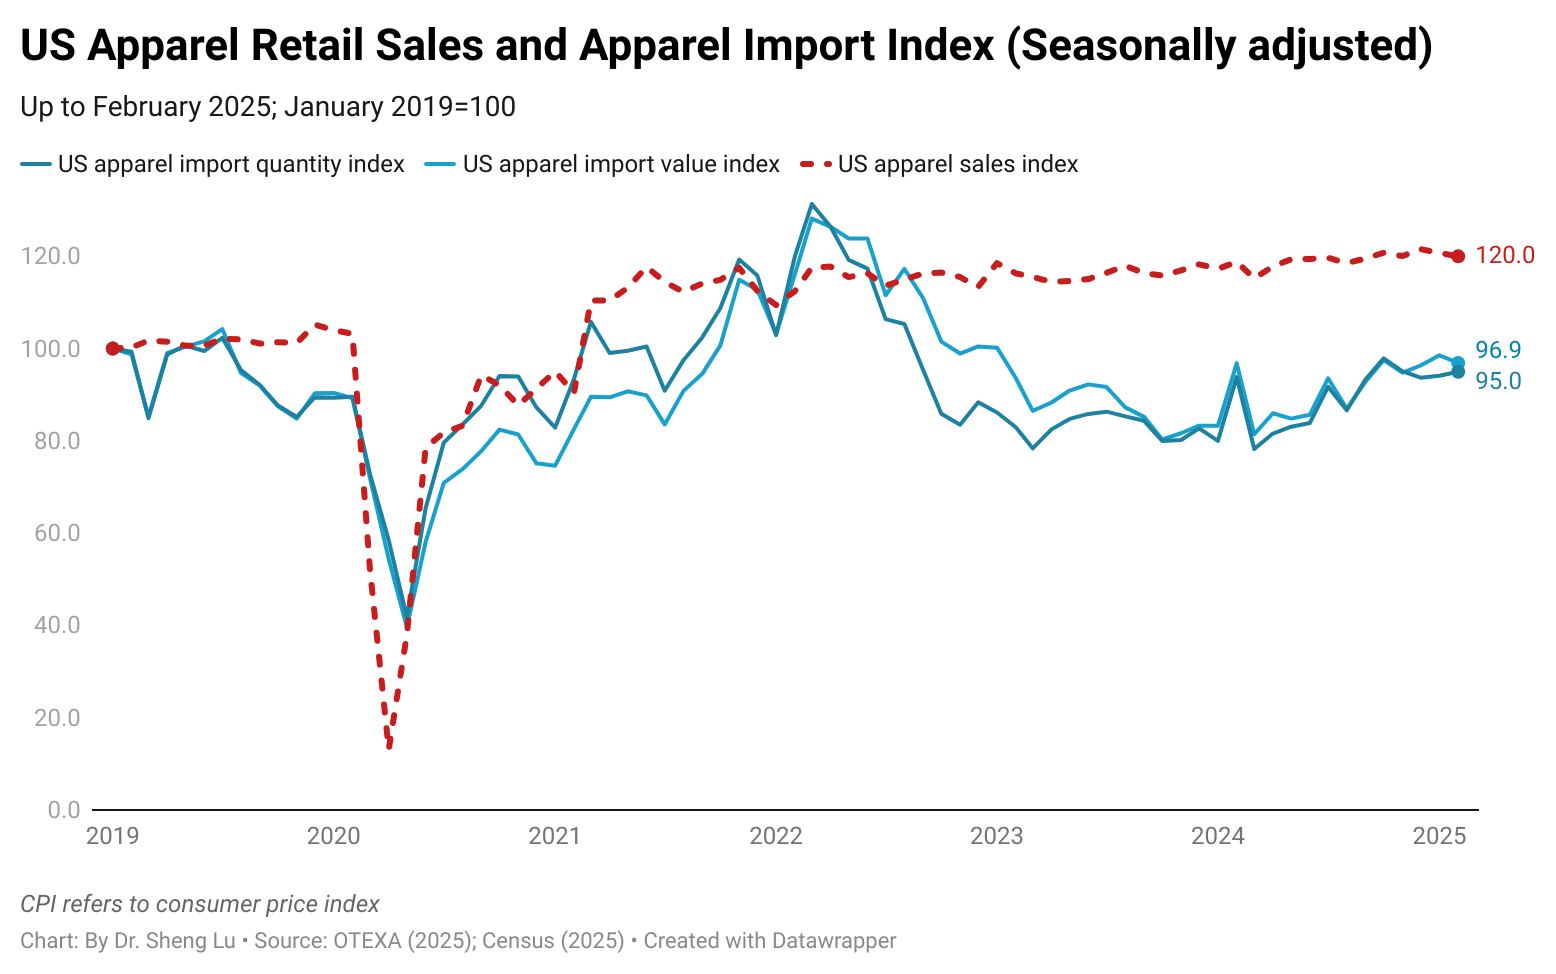
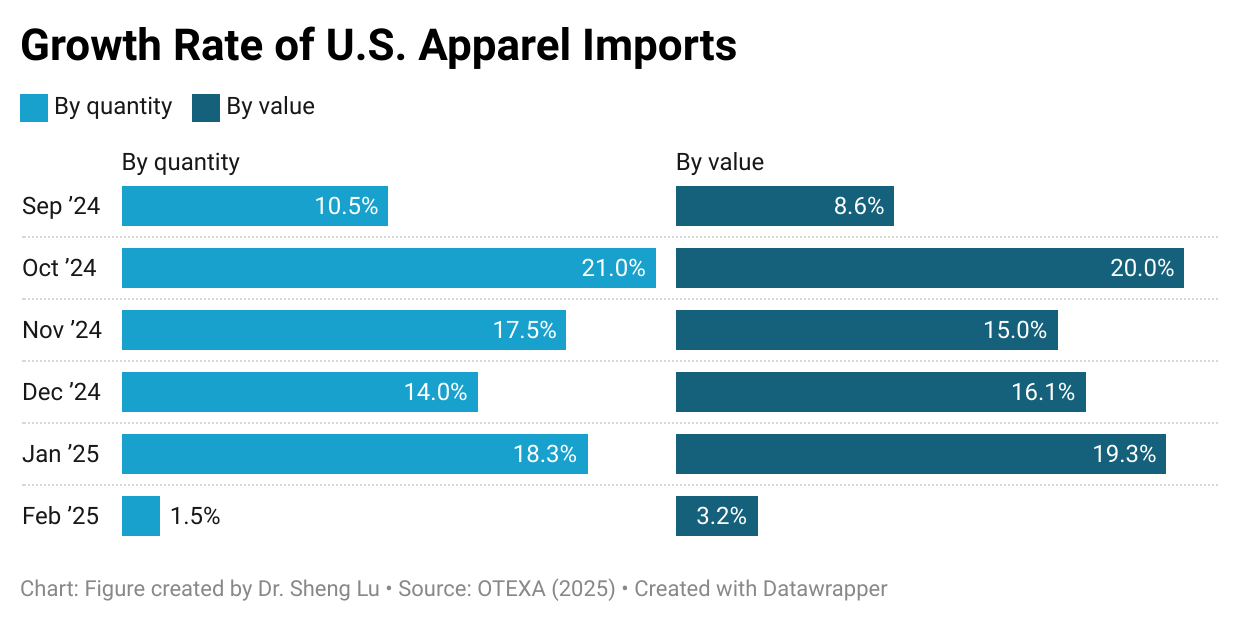
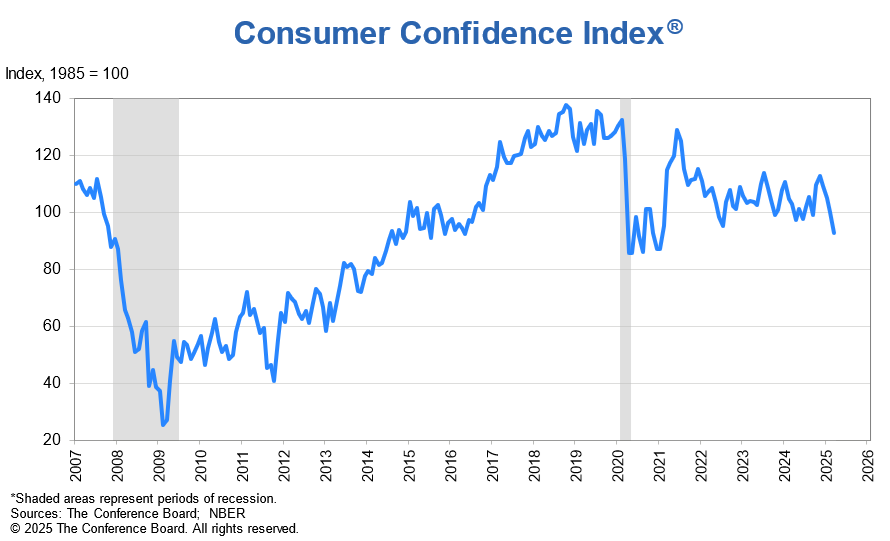
Second, U.S. apparel imports fell in July 2025, negatively impacted by the hiking of tariffs and consumers’ growing hesitancy in clothing spending amid uncertainty about their household financial outlook. Specifically, U.S. apparel imports in July 2025 decreased by 3.0% in value and 5.2% in quantity from a year ago, indicating both an overall shrinking import demand and a more notable import price increase. [Check U.S. apparel import index here]

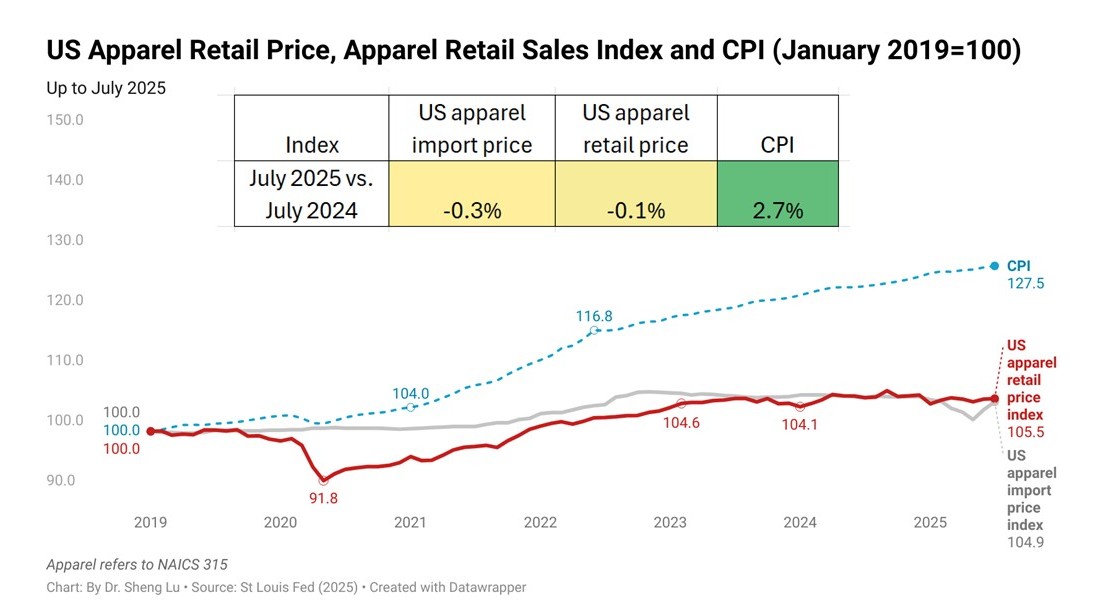
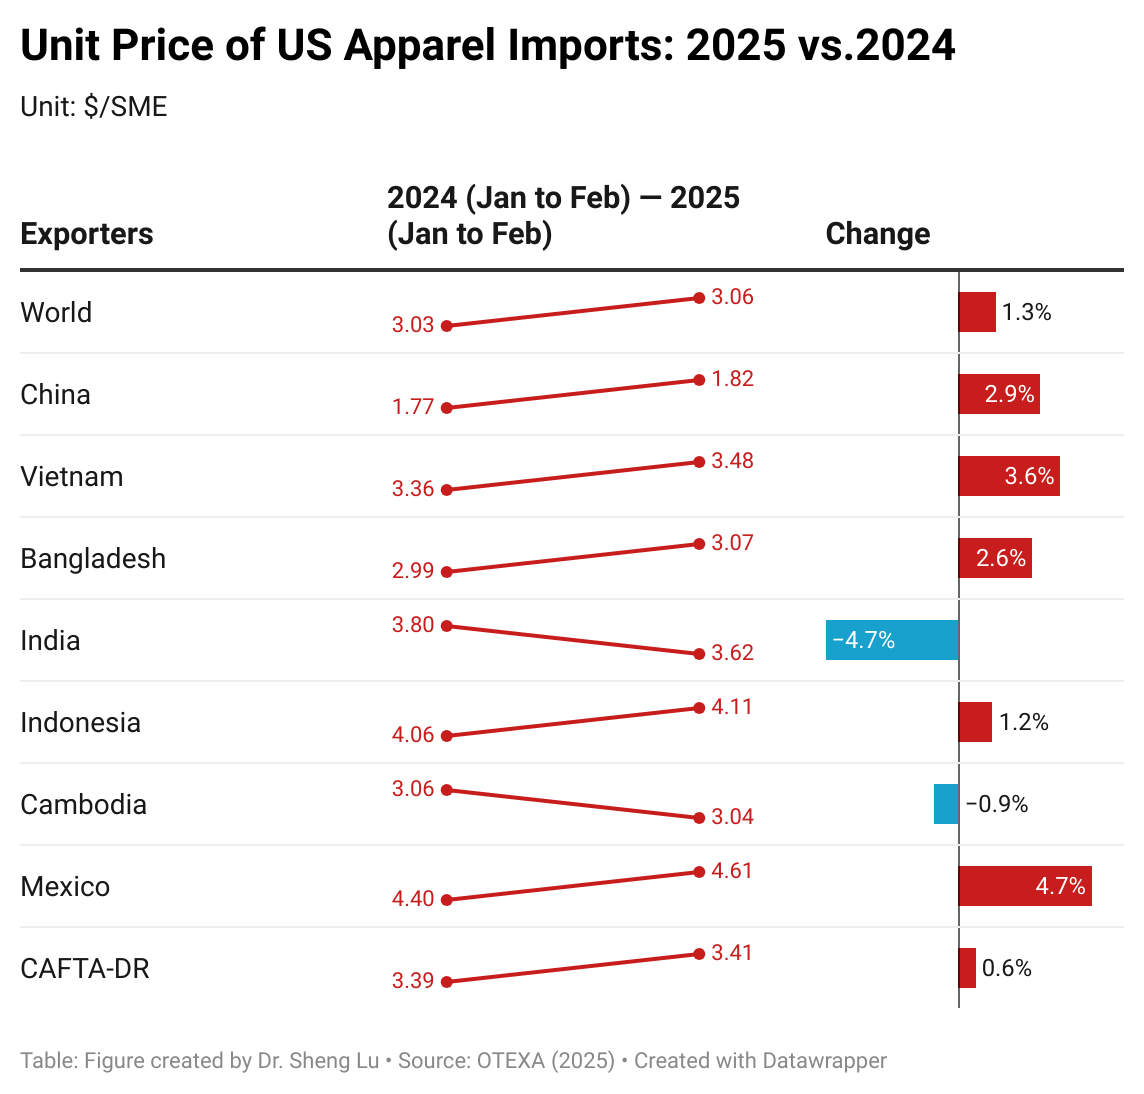
Statistics also show that after removing the seasonal factor, the average U.S. apparel import price went up by nearly 3% from April to July. This trend could become even worse in the coming months as more countries face even higher “reciprocal tariffs” starting from August 2025. However, the average U.S. apparel retail price has not significantly increased, likely because fashion companies fear losing sales at a time when consumers’ clothing spending is already weak. [Check the U.S. clothing retail price index here]

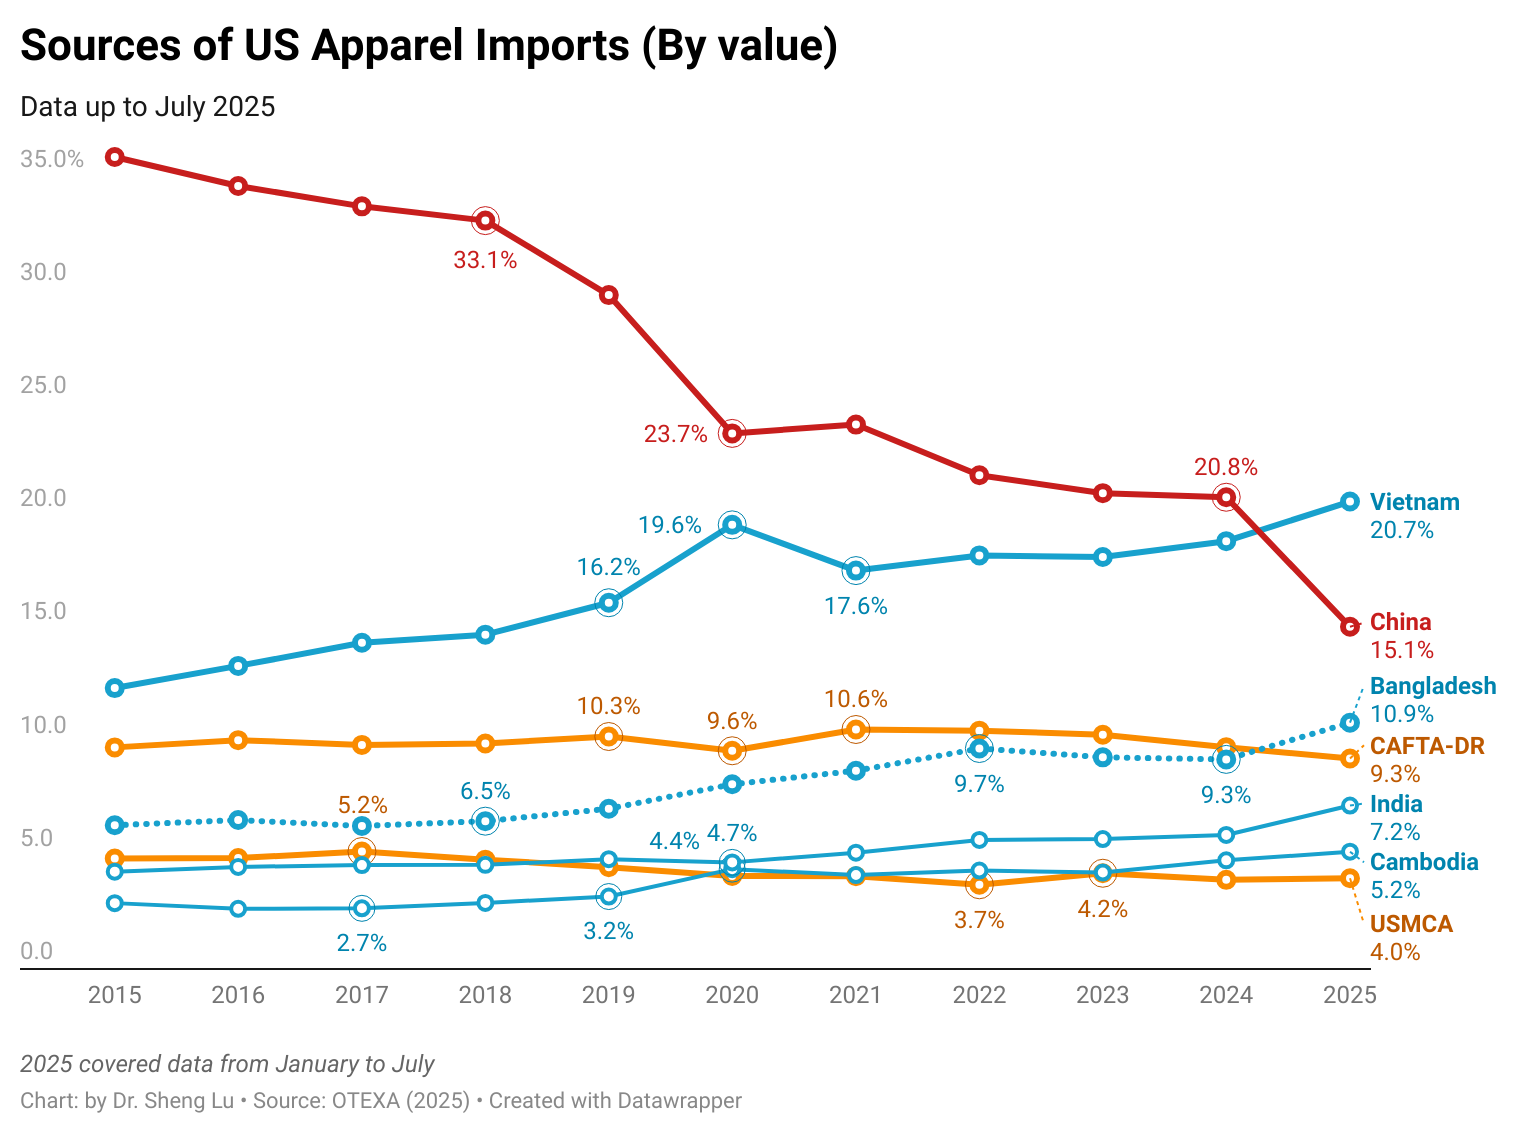
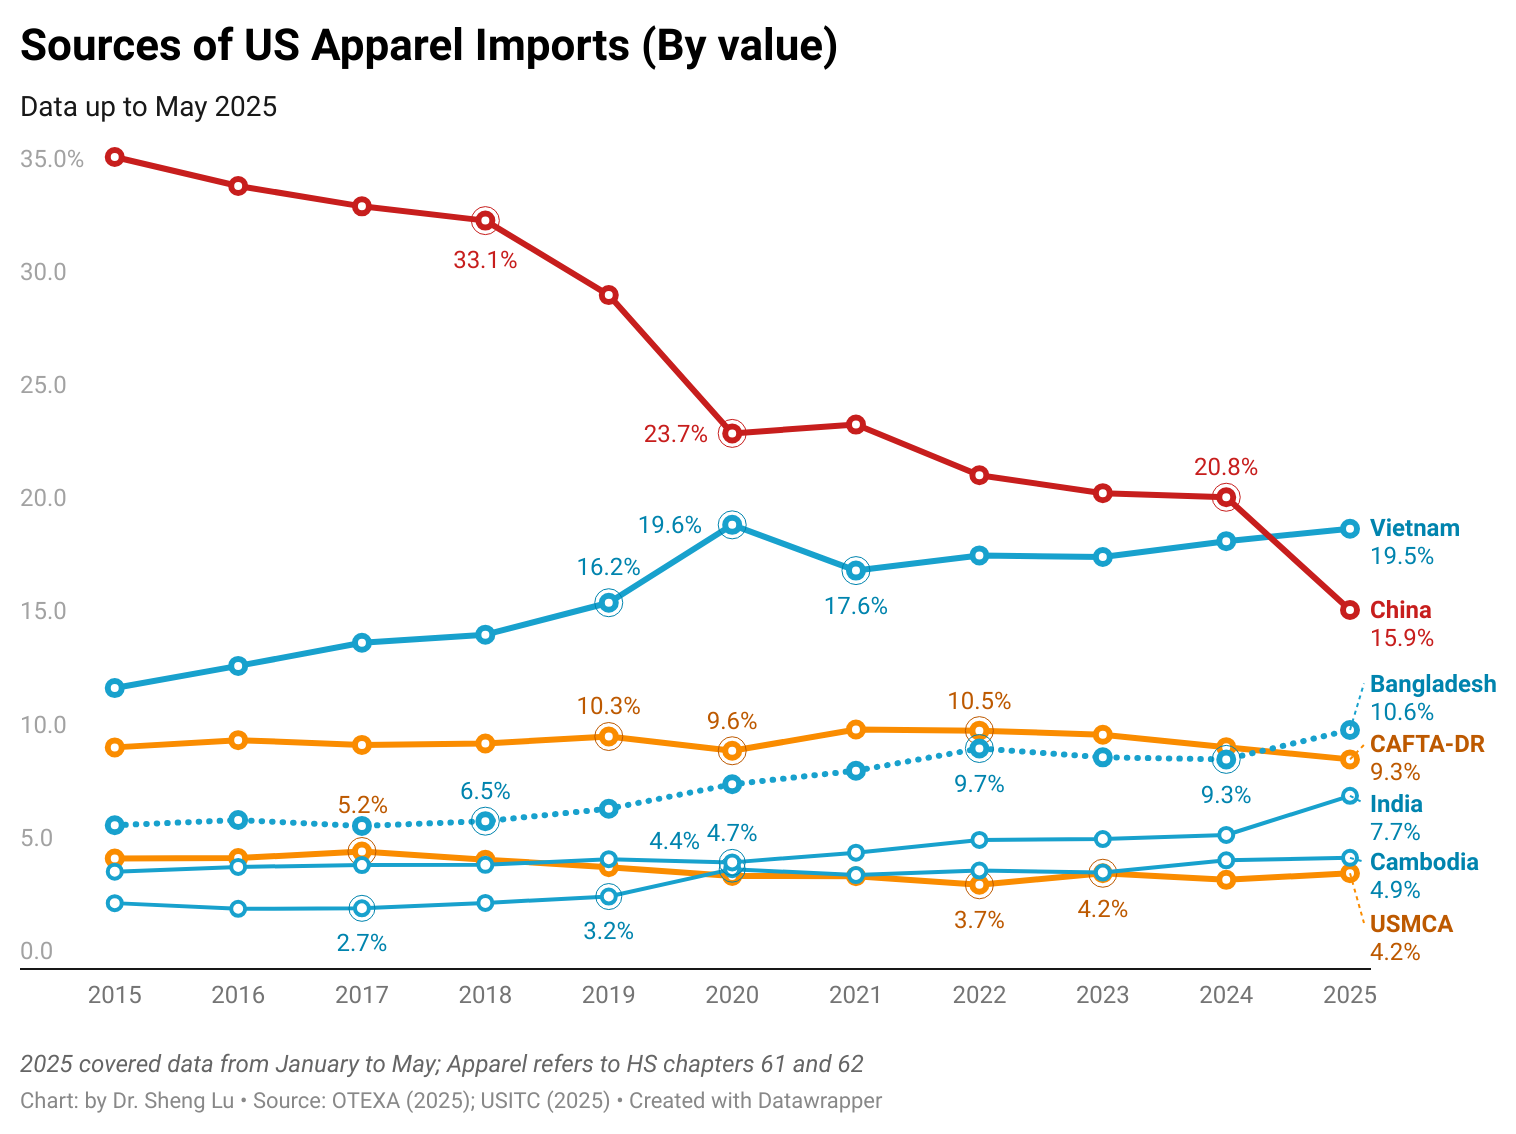
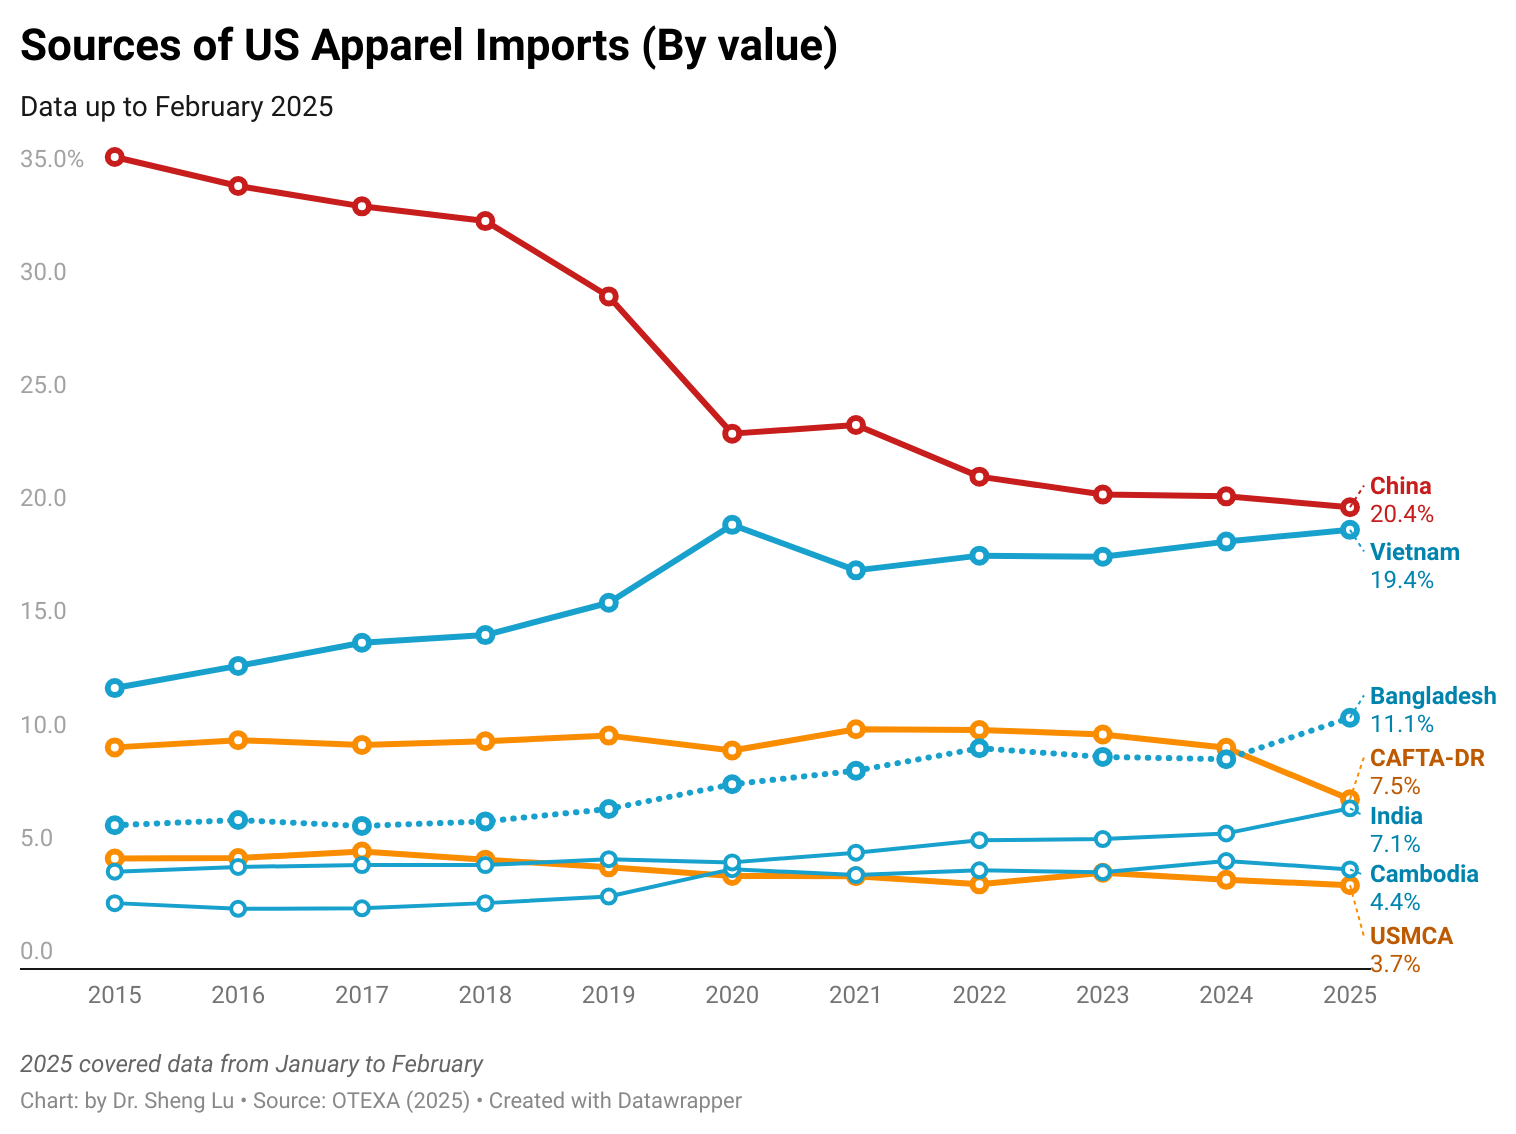
Third, continuing the trends from previous months, U.S. apparel imports from China again fell sharply in July 2025. Facing nearly 50% tariff rates—much higher than those applied to other sourcing countries—U.S. apparel imports from China decreased by 38.4% in value and 27.3% in quantity in July 2025 from a year ago. As a result, in value, China’s market share fell to just 15.6% in July 2025 (was 24.6% in July 2024), significantly lower than Vietnam’s 22.1% (was 19.1% in June 2024). In other words, it may signal a new era where China is no longer the top source of U.S. apparel imports. [Check market shares in U.S. apparel imports here]

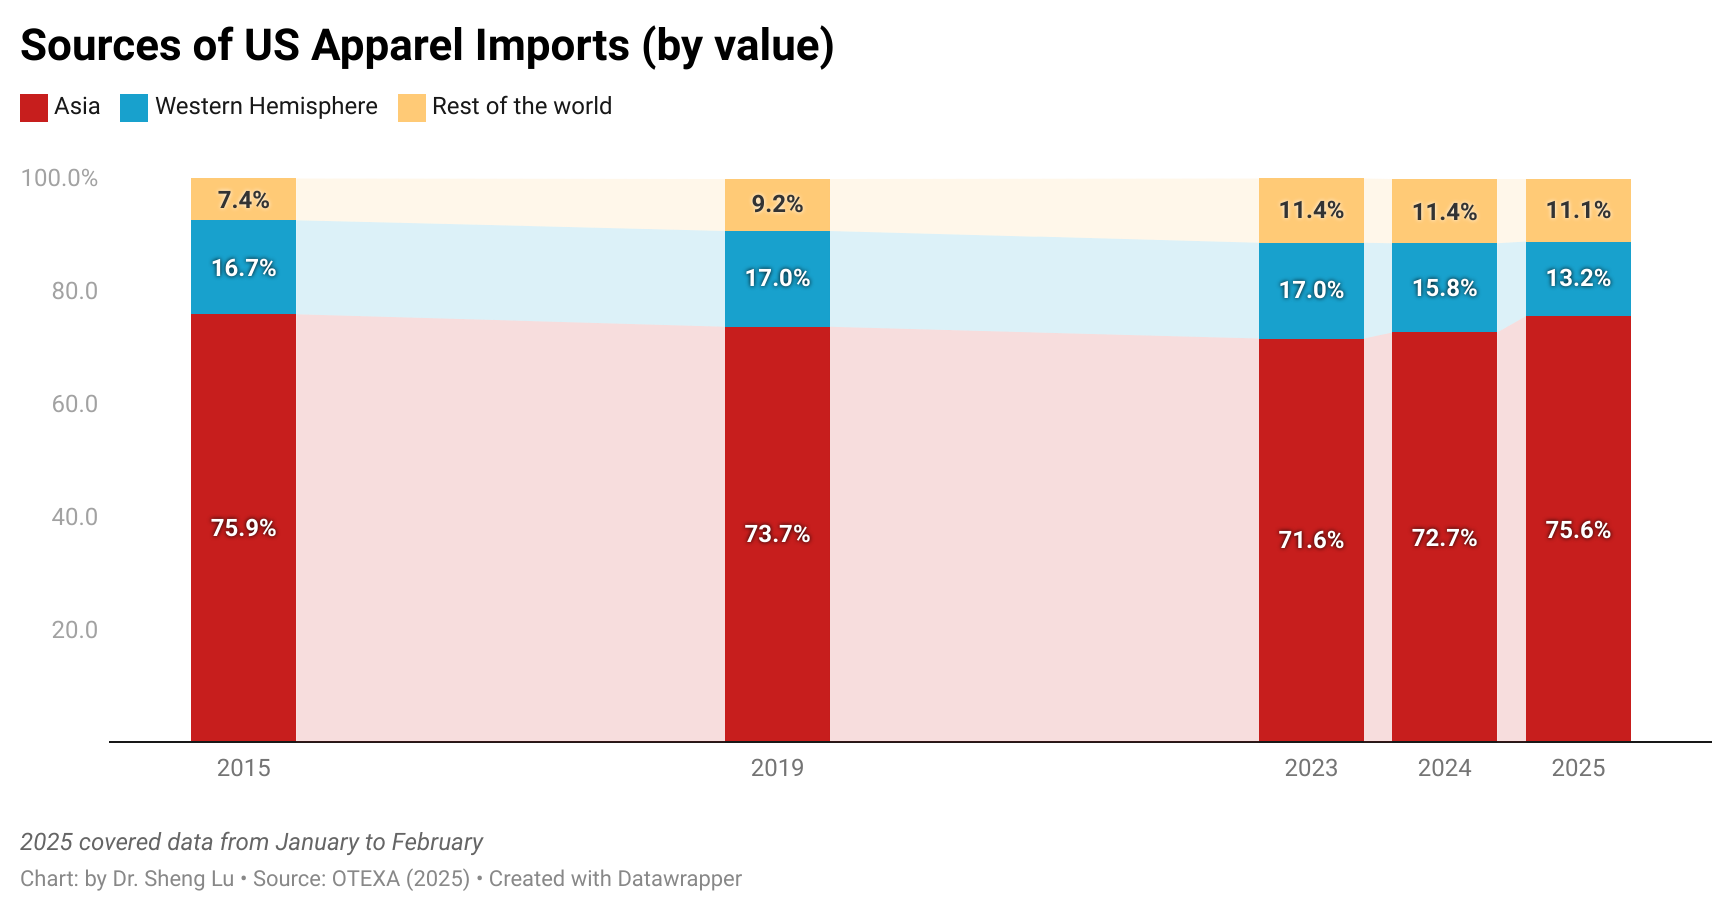
Fourth, while Asia as a whole still dominates, trade data suggests more notable trends of sourcing diversification. In July 2025, about 72.9% of U.S. apparel imports came from China, far exceeding the Western Hemisphere (14.8%) and the rest of the world (12.4%). However, Asia’s market share in July 2025 was slightly lower than 74.7% a year ago, suggesting that more imports came from other regions. For example, at the country level, US apparel imports from several emerging Asian suppliers and those in the Middle East and Africa enjoyed fast growth, including Vietnam (up 12.5%), Cambodia (up 25.2%), Pakistan (up 14.7%), Jordan (up 21.6%), and Egypt (up 30.3%).

Meanwhile, U.S. apparel imports from India in July 2025 also increased by over 15%, although the newly imposed higher tariffs on India could alter the trend in the next few months.

Additionally, there is still no evidence that Trump’s tariff policy has meaningfully boosted nearshoring from the Western Hemisphere. On the contrary, in July 2025, U.S. apparel imports from Mexico grew by just 0.5%, despite the significant tariff advantage offered to USMCA-qualifying products. Similarly, imports from CAFTA-DR members decreased by 2.7%. The results revealed the adverse effects of uncertainty in the Trump administration’s tariff policy on encouraging long-term sourcing and investment commitment to the region.

(note: this post is not open for discussion)

By Sheng Lu

FASH455 Exclusive Interview with Karin De León, Investment and Promotion Director, Apparel and Textiles Association of Guatemala (VESTEX)

About Karin De León

Karin De León has been working in the textile and apparel sector in Guatemala for more than 25 years, promoting the development of the industrial cluster, participating in the creation of strategies, supporting the strengthening of the supply chain, and attracting investment.

As part of her role at the Apparel and Textile Association of Guatemala (VESTEX), for 10 years she held the position of Executive Director of CECATEC-RD (Central American and Dominican Council of Clothing and Textiles), the entity that integrates textile & apparel industry associations of Central America and the Dominican Republic and which is responsible for coordinating the inter-institutional relationship with public and private entities of the United States of America, Mexico and Colombia mainly.

From 2020 to the beginning of 2022, she served as Chief of Staff of the Ministry of Economy of Guatemala and later became General Coordinator of the National Competitiveness Program (PRONACOM), a government entity responsible for promoting the country and attracting investment.

Karin is currently VESTEX’s investment and promotion director, and representative of Guatemala in CECATEC-RD. She coordinates the inter-institutional relationship with government entities of the United States (such as the United States Trade Representative and the Department of Commerce) as well as private institutions mainly related to the United States, Mexico, and Colombia.

Sheng: Can you provide a brief introduction to VESTEX and a general overview of your member companies?

Karin: VESTEX is the Apparel and Textile Association of Guatemala, a private association representing the Guatemalan textile and apparel export sector. It focuses on promoting the industry’s exports through strategic alliances with public and private institutions at the national and international levels.  Its strategic axes are Sectoral Resilience, which seeks to position the industry as a generator of investment and formal employment in the country; Sectoral Sustainability, through the promotion of sustainability as a long-term strategy for industry continuity and compliance, providing companies in the sector with tools that facilitate compliance with the obligations established in the laws and regulations.

VESTEX partners comprise companies that integrate the entire supply chain of the apparel and textile sector, encompassing yarn and fabric manufacturers, apparel producers, as well as firms providing specialized services and accessories to the industry.

Sheng: Studies show that there is consistent interest among U.S. fashion companies in expanding nearshoring from the Western Hemisphere, including Guatemala. What is your observation? What makes Guatemala an attractive destination for apparel sourcing today? What are the unique advantages of sourcing from the country?

Karin:Guatemala has become an increasingly attractive destination for apparel sourcing due to its unique combination of industrial integration, geographic advantages, and strong compliance standards. The country offers a highly integrated apparel cluster that encompasses every stage of the supply chain—from spinning yarn and weaving fabrics to apparel manufacturing, printing, finishing, and packaging. This full-package model not only streamlines operations and enhances traceability but also allows for greater flexibility and product diversity, raising the added value of garments and positioning Guatemala as a competitive supplier for niche and complex products requiring skilled labor and high-quality materials.

Another key differentiator is Guatemala’s strategic location. With access to ports on both the Atlantic and Pacific coasts—separated by only 249 miles—the country can efficiently serve both the East and West coasts of the United States. Guatemala manages the second-largest maritime cargo operation in Central America (after Panama), which is critical for companies seeking to balance and mitigate geopolitical and logistical risks. In addition, proximity to the U.S. substantially reduces environmental impact: sourcing from Guatemala lowers CO₂ emissions from maritime transport by approximately 84% compared to sourcing from Asia. Transit times are also highly competitive, with shipments reaching Miami in as little as three days, enabling U.S. buyers to manage inventories more effectively and respond to market demands with agility.

Equally important, Guatemalan apparel companies operate under a strong framework of labor and environmental compliance. Companies demonstrate a full-spectrum commitment to input traceability, adherence to strict rules of origin, and continuous process improvement to reduce resource consumption. Investments in monitoring and ESG systems underscore their transparency and alignment with global sustainability standards.

Taken together, this integration of cluster capabilities, geographic proximity, and compliance with international norms positions Guatemala as a reliable, sustainable, and strategically advantageous sourcing partner for U.S. fashion companies.

Sheng: How important is the Dominican Republic-Central America Free Trade Agreement (CAFTA-DR) in supporting Guatemala’s apparel exports to the U.S. market? What impact do CAFTA-DR’s apparel-specific rules of origin have on garment exporters’ supply chains and export strategies in Guatemala?

Karin:CAFTA-DR has provided certainty by encouraging long-term investments in textile infrastructure and capabilities. CAFTA-DR has been the basis for the development of Guatemala’s apparel industry.  The yarn-forward rule established under the agreement has not only fostered integration with the U.S. supply chain but also promoted stronger collaboration among Central American countries. By allowing the accumulation of inputs and processes within the region, CAFTA-DR has significantly strengthened intraregional trade.

This integration has facilitated the specialization of each Central American country. In Guatemala’s case, it has enabled the use of specific yarns and fabrics produced in other countries and manufactured locally, fostering a greater diversification of production.

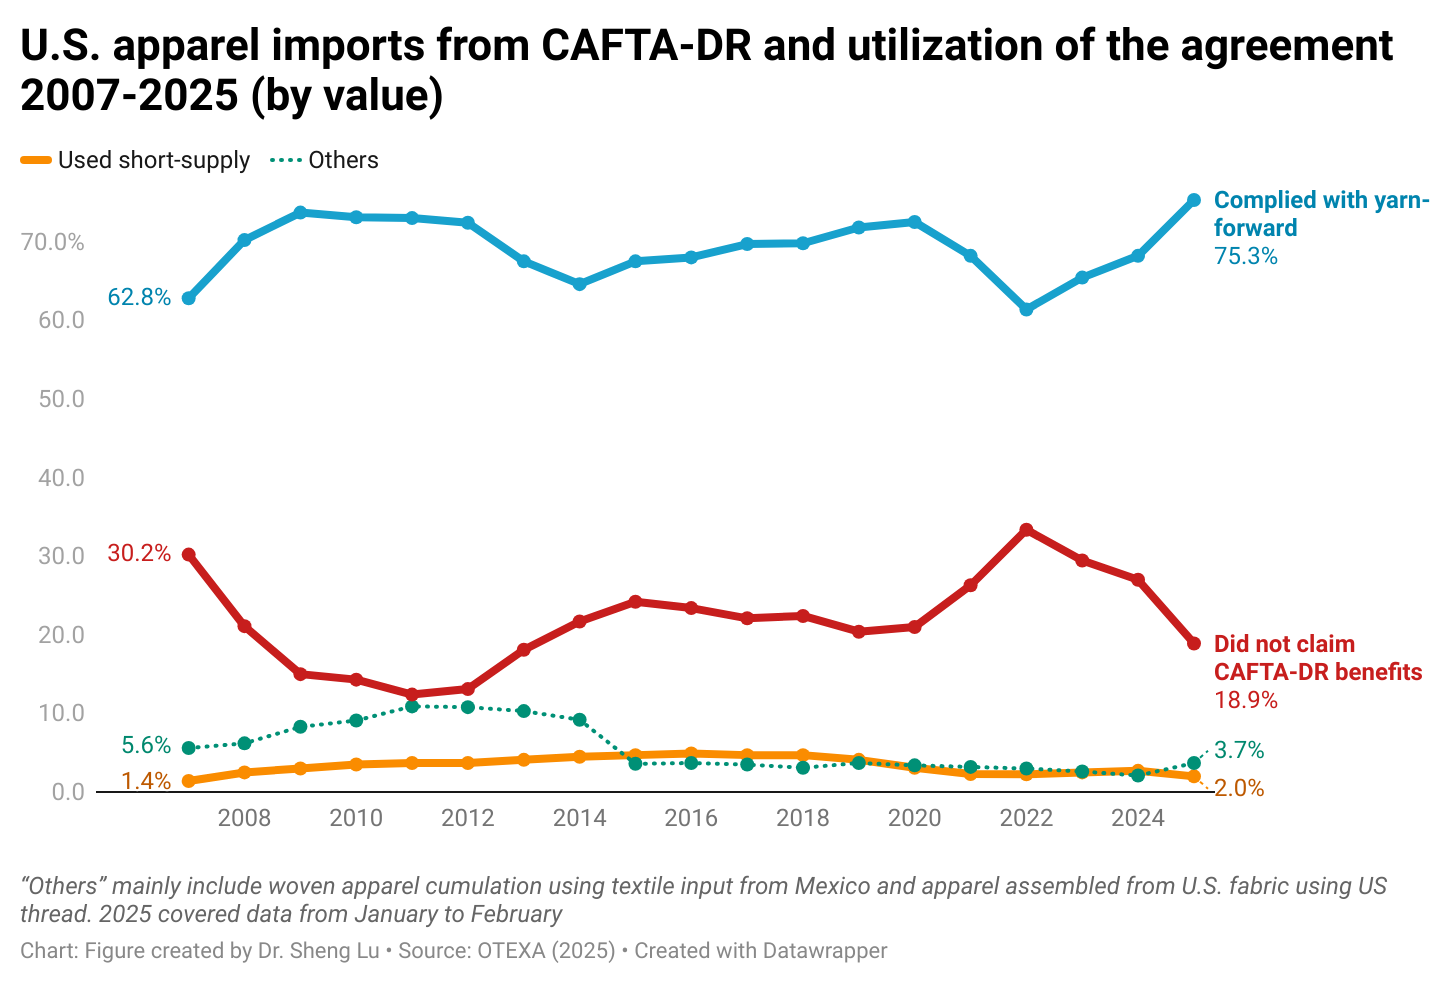
According to OTEXA figures, in the year ending June 2025, 89.17% of Guatemala’s total apparel exports to the U.S. entered under the Free Trade Agreement preferences. Of this total, 79.69% qualified under the yarn-forward rule—that is, garments made with yarn from the U.S. or yarn produced within one of the Central American countries. CAFTA-DR, and particularly its rules of origin, have been the basis of Guatemala’s strategy in recent years, not only to attract foreign direct investment but also to encourage significant reinvestments.

Sheng: Data shows that an increasing share of yarns and fabrics used by Guatemala garment factories are now locally made in Guatemala and other Central American countries. Could you discuss the recent trends in textile manufacturing capacity building in Guatemala, as well as the industry’s current priorities in building a more vertically integrated regional supply chain?

Karin:Guatemala offers a series of competitive advantages that are reinforcing its role as a regional hub for textile and apparel manufacturing. At the country level, it benefits from a stable macroeconomy, a solid exchange rate, competitive electricity prices within the region, and a reliable energy supply. At the industry level, Guatemala stands out for its robust apparel and textile cluster and highly skilled workforce.

Since the pandemic in 2020, when many global companies accelerated nearshoring strategies, Guatemala has successfully attracted new foreign investment and supported the expansion of companies already established in the country, particularly in the spinning industry. Installed capacity is primarily focused on cotton, although blends are also produced. By the end of 2024, apparel exported to the U.S. consisted of 62.8% cotton, 36.4% synthetics, and 0.8% wool, reflecting the central role of cotton in the country’s production while also showing diversification into other fibers.

Driven by shifting market demand, textile production in Guatemala has been expanding beyond knits, with a modest increase in woven fabrics as well. Investments in innovation and technology have enabled the industry to offer specialized processes, including antimicrobial treatments, absorption, UPF protection, enzymatic washing, softening, and plush finishing, among others. A particularly important advancement has been the investment in elastic knit fabrics, which has opened the door to the production of categories such as sportswear, intimate apparel (seamless), shapewear (technical lingerie and compression fabrics), and medical textiles.

We recognize, however, that there remain challenges and opportunities to broaden the regional textile offering—particularly in the production of yarns and fabrics made from fibers not yet manufactured locally. Expanding capacity in these areas would further strengthen vertical integration and supply chain resilience.

In this context, VESTEX has taken a leading role in supporting and guiding companies interested in exploring these opportunities. In coordination with Guatemala’s foreign direct investment promotion agency, efforts are underway to identify high-demand inputs that are currently unavailable in the region but represent strategic opportunities for local production.

Sheng: Since April 2025, U.S. apparel imports from CAFTA-DR countries, including Guatemala, are subject to a new 10% “reciprocal tariff.” How has this tariff increase and the Trump administration’s trade policy so far impacted Guatemala’s garment industry and exports? 

Karin:The main challenge for Guatemala’s apparel industry under the current U.S. trade policy has been the high degree of uncertainty. Markets and buyers demand stability, yet in recent months orders have slowed significantly as companies await clarity on the tariffs that will ultimately apply to each country. This hesitation has already resulted in lost opportunities: seasonal orders cannot be recovered once the selling window has passed.

Traditionally, Guatemala’s apparel sector grows between 3% and 5% annually; however, 2025 projections have been revised downward, and current expectations suggest growth closer to 1–2%. According to the Central Bank of Guatemala, as of June 2025, exports registered a modest 1.36% increase—well below what was anticipated under normal conditions.

Another major impact has been the need for companies to absorb additional costs to maintain contracts with international brands. This has reduced profit margins, limited reinvestment capacity, and increased pressure on already tight production cycles. Buyers face uncertainty as well: they do not know how much a garment ordered today will cost by the time it is delivered six to nine months later, since tariff rates are subject to abrupt changes. The volatility recalls past episodes in China, where tariffs under former President Trump rose as high as 145% before being reduced to 30%, creating unpredictable supply conditions.

That said, Guatemala continues to hold a relative tariff advantage compared with Asian competitors, where rates now reach 15%, 18%, 25%, or even higher. This gap may ultimately favor Guatemala if U.S. buyers reconfigure sourcing strategies to prioritize suppliers who are both geographically closer and more reliable. Indeed, global sourcing is shifting away from a purely low-cost model toward one that values resilience, speed to market, and compliance.

Sheng: The 2025 US Fashion Industry Association Benchmarking Study indicates that U.S. fashion companies are increasingly seeking sourcing destinations that can provide sustainable apparel products, including those made with preferred fibers such as organic, recycled, regenerative, and biodegradable materials. What strategies or recent initiatives has the Guatemalan textile and apparel industry undertaken to meet this demand for sustainability?

Karin: Guatemalan mills already source recycled polyester yarns, organic or regenerative cotton, and biodegradable materials. Brands are actively demanding these products. In fact, mills have obtained various certifications and adhere to practices focused on circular economy, science-based target initiatives, and other sustainability standards.

Traceability is key for the textile and apparel industry, and Guatemala has managed to implement measures such as data management and continuous improvement as a way to demonstrate this.

  • Adoption of Sustainable Certifications and Standards: Guatemalan manufacturers are obtaining certifications like GOTS (Global Organic Textile Standard), OEKO-TEX, Global Recycled Standard, Recycled Claim Standard, Blue Sign, Higg FEM, among others, ensuring their products meet international sustainability standards.
  • Investment in Technologies: Many mills are upgrading to water and energy-efficient machinery, as well as more sustainable dyeing and finishing processes.
  • Training and Capacity Building: Initiatives to train and certify workers and management on sustainable practices and standards are increasing, promoting a culture of sustainability throughout the industry.
  • Integration of Circular Economy Principles: Some mills are exploring design for recyclability techniques to align with circular economy goals.

These initiatives collectively position the Guatemalan textile and apparel sector as a viable sourcing destination for sustainable fashion, aligning with global market trends and buyer preferences for more sustainable products.

Sheng: In addition to the questions discussed earlier, what are the top business and policy issues facing Guatemala’s textile and apparel industry over the next 1–2 years?

Karin:Over the next 1–2 years, Guatemala’s textile and apparel industry will face several pressing business and policy issues that will shape its competitiveness.

1. Infrastructure and logistics.
A key issue remains the need to strengthen national infrastructure, particularly ports, customs processes, and internal transport routes.

2. Limited availability of regional inputs.
The industry continues to face constraints in the local production of certain yarns, fabrics, and specialized fibers. Inputs such as viscose, spandex, and rayon are not yet manufactured in the region at scale, which limits vertical integration and forces reliance on imports from outside the hemisphere. Expanding textile capacity in these areas is a central issue to ensure resilience and broaden the exportable supply.

3. Market visibility and buyer perception.
Despite its high level of integration, many international buyers remain unaware of Guatemala’s strengths in complex products, compliance, and sustainability. A persistent challenge is to raise global awareness of the country’s capabilities in order to capture greater sourcing opportunities.

4. Policy uncertainty and trade volatility.
The recent 10% reciprocal tariff applied to CAFTA-DR countries has introduced significant uncertainty. Buyers hesitate to place long-term orders when tariff levels are unclear, and this volatility affects sourcing decisions. Stability and predictability in trade policy remain critical issues for the sector.

5. Differentiation and specialization under nearshoring.
Another key challenge is sustaining competitiveness through higher-value products. Today, 54.11% of Guatemala’s apparel exports already include advanced finishing processes, and the industry is investing in spinning, woven fabrics, and technical textiles. However, scaling these capabilities requires reinvestment and foreign capital inflows—both of which are being constrained by global uncertainty. Given that Guatemala currently supplies only about 2% of U.S. apparel imports, a major issue ahead is how to convert this untapped potential into tangible growth.

In short, while the country is positioning itself strategically with competitive tariffs, geographic proximity, and an increasingly sophisticated textile base, the top issues over the next two years will be overcoming infrastructure and logistics bottlenecks, reducing dependence on imported inputs, strengthening promotion to buyers, and navigating trade policy volatility. Addressing these challenges will be crucial for Guatemala to capitalize on long-term opportunities in the ongoing global supply chain reconfiguration.

-The End-

2025 August Sourcing at MAGIC Recap

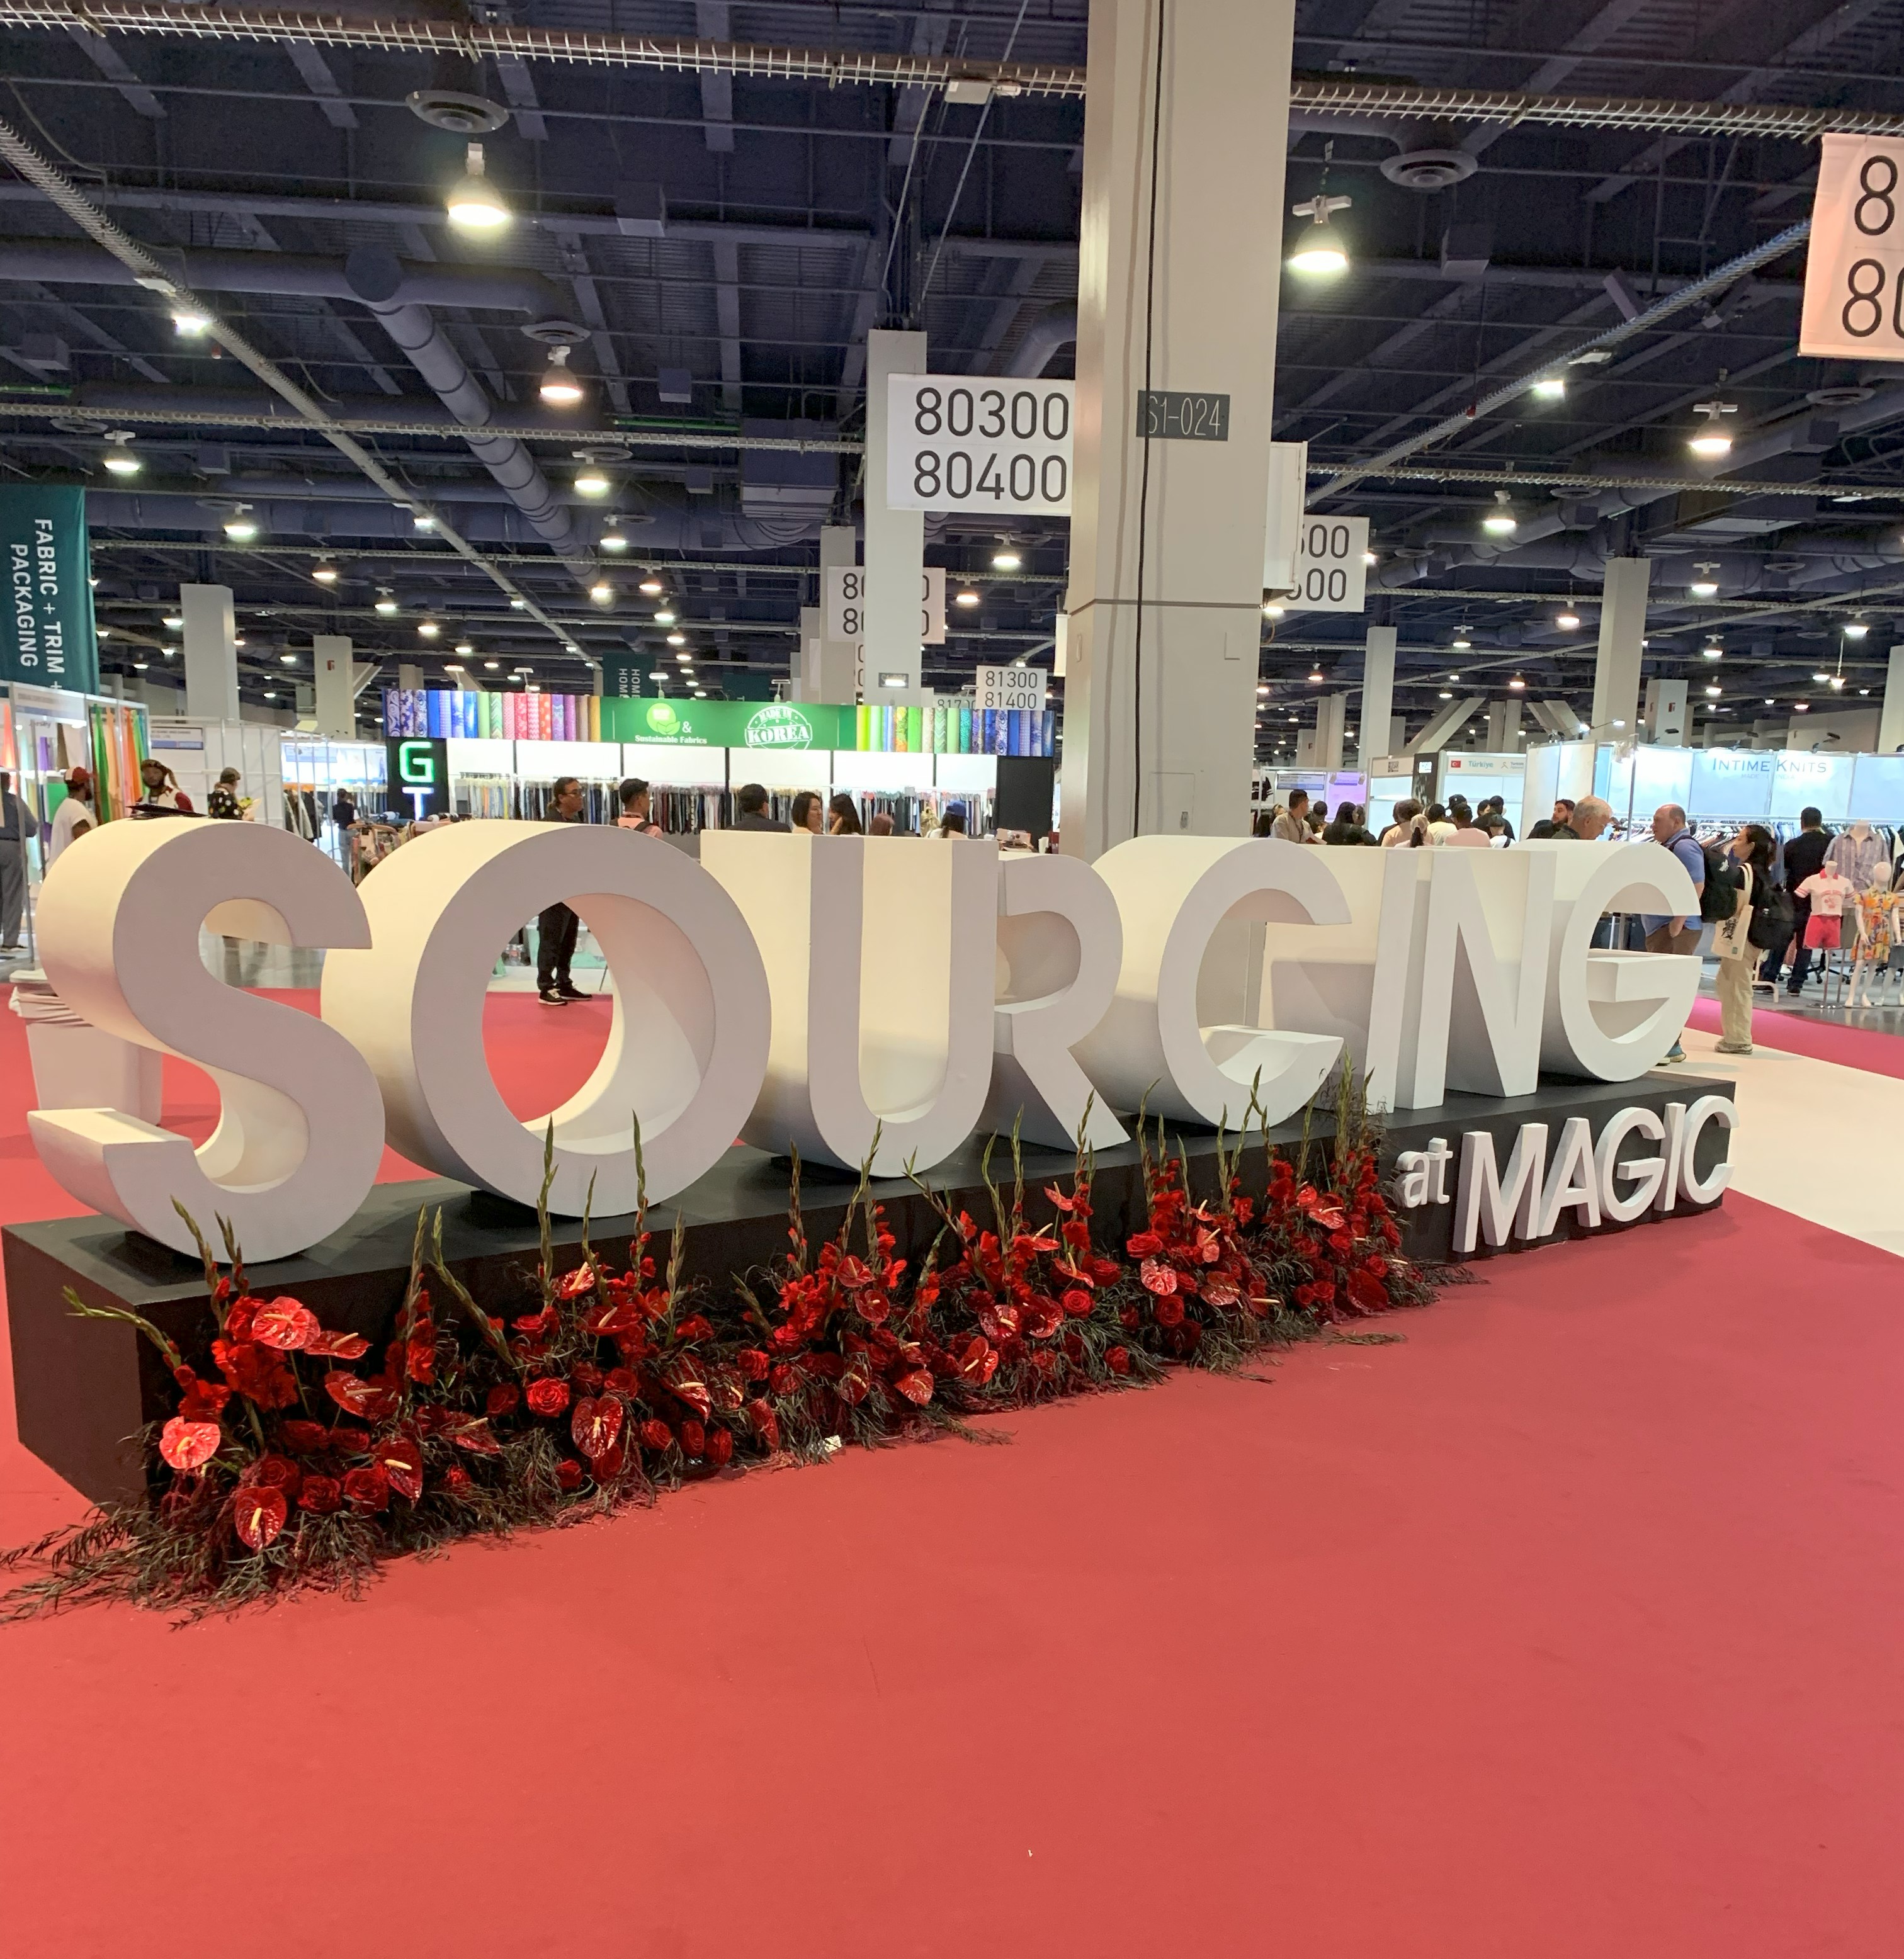
The latest Sourcing at MAGIC, one of the largest and most influential fashion apparel trade shows in North America, was held from August 18 to 20, 2025 in Las Vegas. Drawing thousands of apparel manufacturers, textile raw material suppliers, brands, and retail buyers from over 30 countries around the globe, the event provides a unique opportunity to observe the latest U.S. apparel sourcing trends and market sentiment.

Aligned with the results of the 2025 Fashion Industry Benchmarking Study released by the United States Fashion Industry Association (USFIA), the hiking tariffs imposed by the Trump administration and ongoing policy uncertainty were among the top concerns for MAGIC attendees. One major tariff impact often heard at the MAGIC show was the growing inflationary pressure. It was a prevailing view among vendors, brands, and retailers that a price increase had begun and would become even more noticeable to U.S. consumers in the upcoming months. Some also argue that “tariff is no longer a sourcing problem,” but how brands and retailers should handle their “profit margin, product assortment, and pricing.”

Meanwhile, apparel suppliers care significantly about the additional “reciprocal tariff” rates they face compared to their key competitors. For instance, a jeans supplier from Pakistan said they were relieved to see more order inquiries come in, as their Indian competitors faced significantly higher tariff rates threatened by the Trump administration.

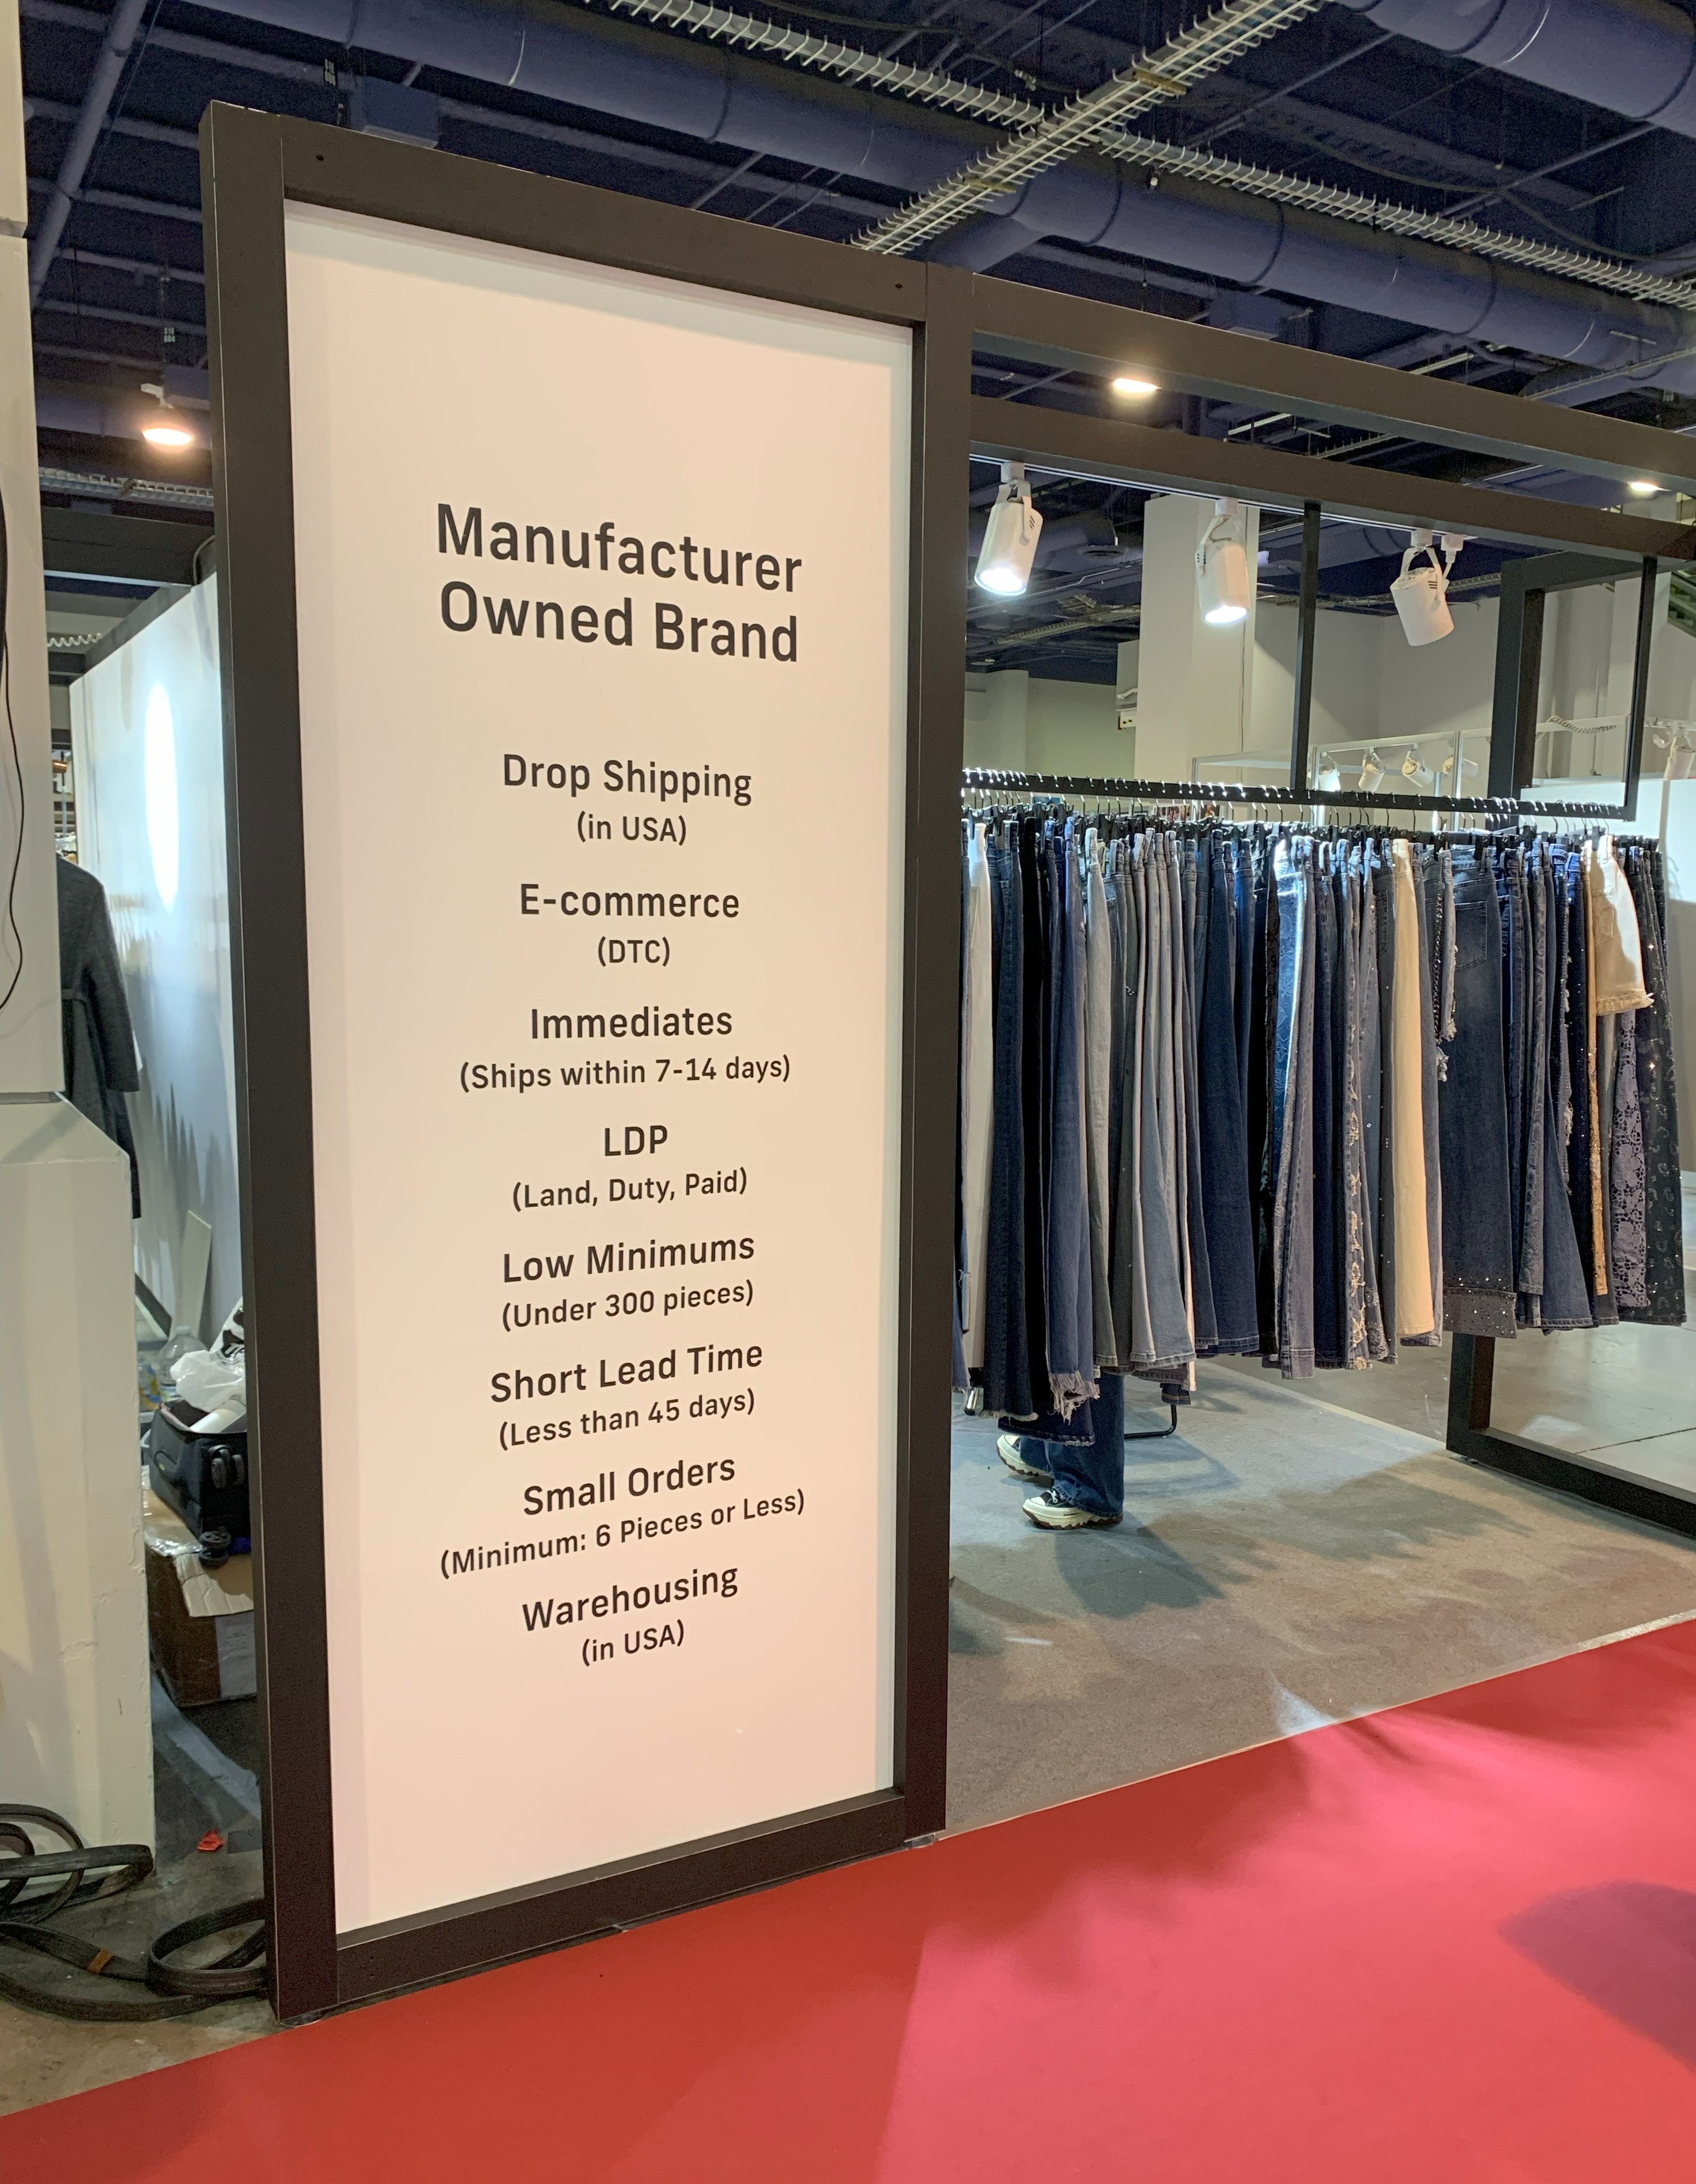
Still, nearly 600 exhibitors from China attended MAGIC, making it the largest delegation from any country. Two interesting phenomena revealed how Chinese suppliers try to stay competitive in today’s challenging business environment. One is to offer various value-added sourcing services beyond physical products.  For example, there was a dedicated session at this year’s MAGIC show that featured Chinese manufacturers that provide services such as drop shipping (i.e., when a customer places an order, the retail store never physically handles the product. Instead, the manufacturer is responsible for inventory, packing, and shipping), director to consumer (DTC) e-commerce and warehousing. Meanwhile, some Chinese vendors accept small orders (i.e., 6 pieces or less) or low minimum orders (i.e., 300 pieces) and promise a short lead time of 45 days. In comparison, the minimum order quantity (MOQ) required by suppliers in other Asian and Western Hemisphere countries typically exceeds thousands of pieces.

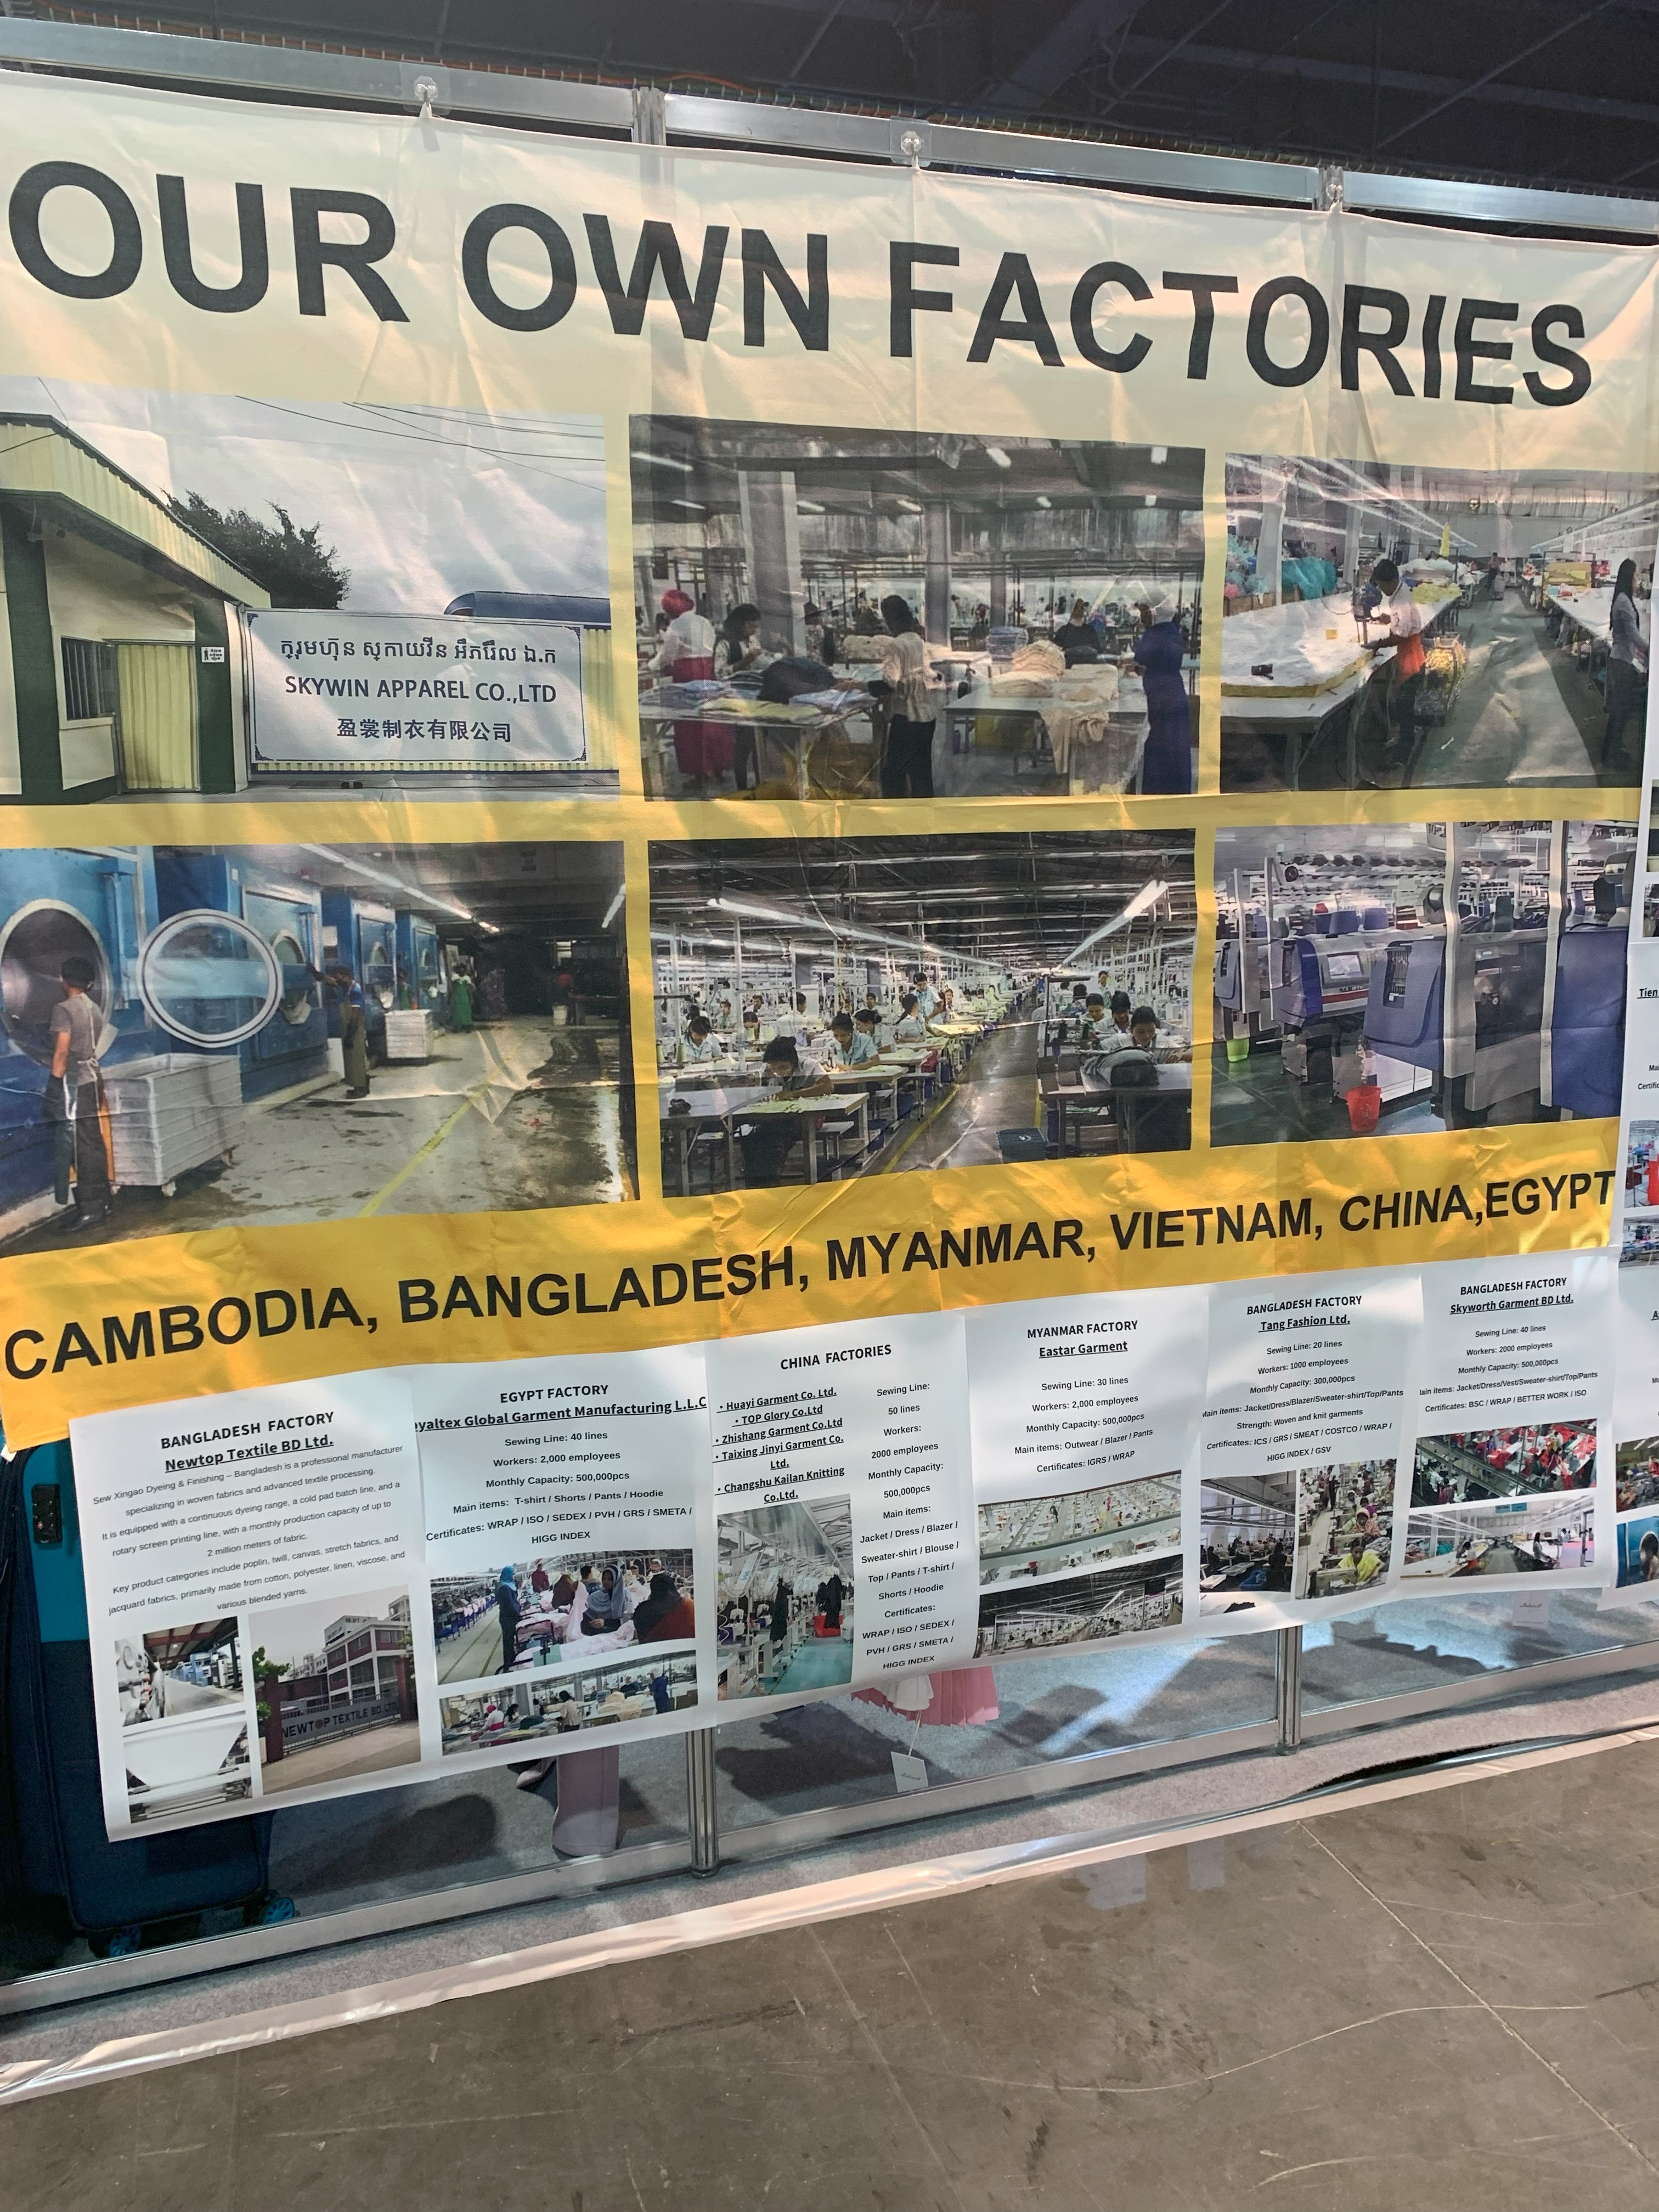
On the other hand, it is not uncommon to see that vendors from Bangladesh, Vietnam, Cambodia, or even Egypt and Ghana were actually owned by Chinese investors. Several Chinese factories purposefully highlight that they own factories across the world, from China and Southeast Asia to Africa. According to the USFIA benchmarking study, some U.S. fashion companies also prefer vendors with production capabilities in multiple countries to reduce sourcing risks.

As U.S. fashion companies continue to diversify their sourcing beyond the traditional top three—China, Vietnam, and Bangladesh—emerging destinations are increasingly optimistic about their U.S. export prospects. For instance, a supplier from Jordan noted that recent U.S. tariff hikes have boosted Jordan’s competitiveness, given the zero most-favored-nation (MFN) tariff under the U.S.-Jordan Free Trade Agreement and a 15% reciprocal tariff rate, which was lower than many Asian suppliers face.Jordanian suppliers speak highly of the capacity-building support from international organizations such as the International Trade Centre (ITC), particularly in areas like skills training and market intelligence.

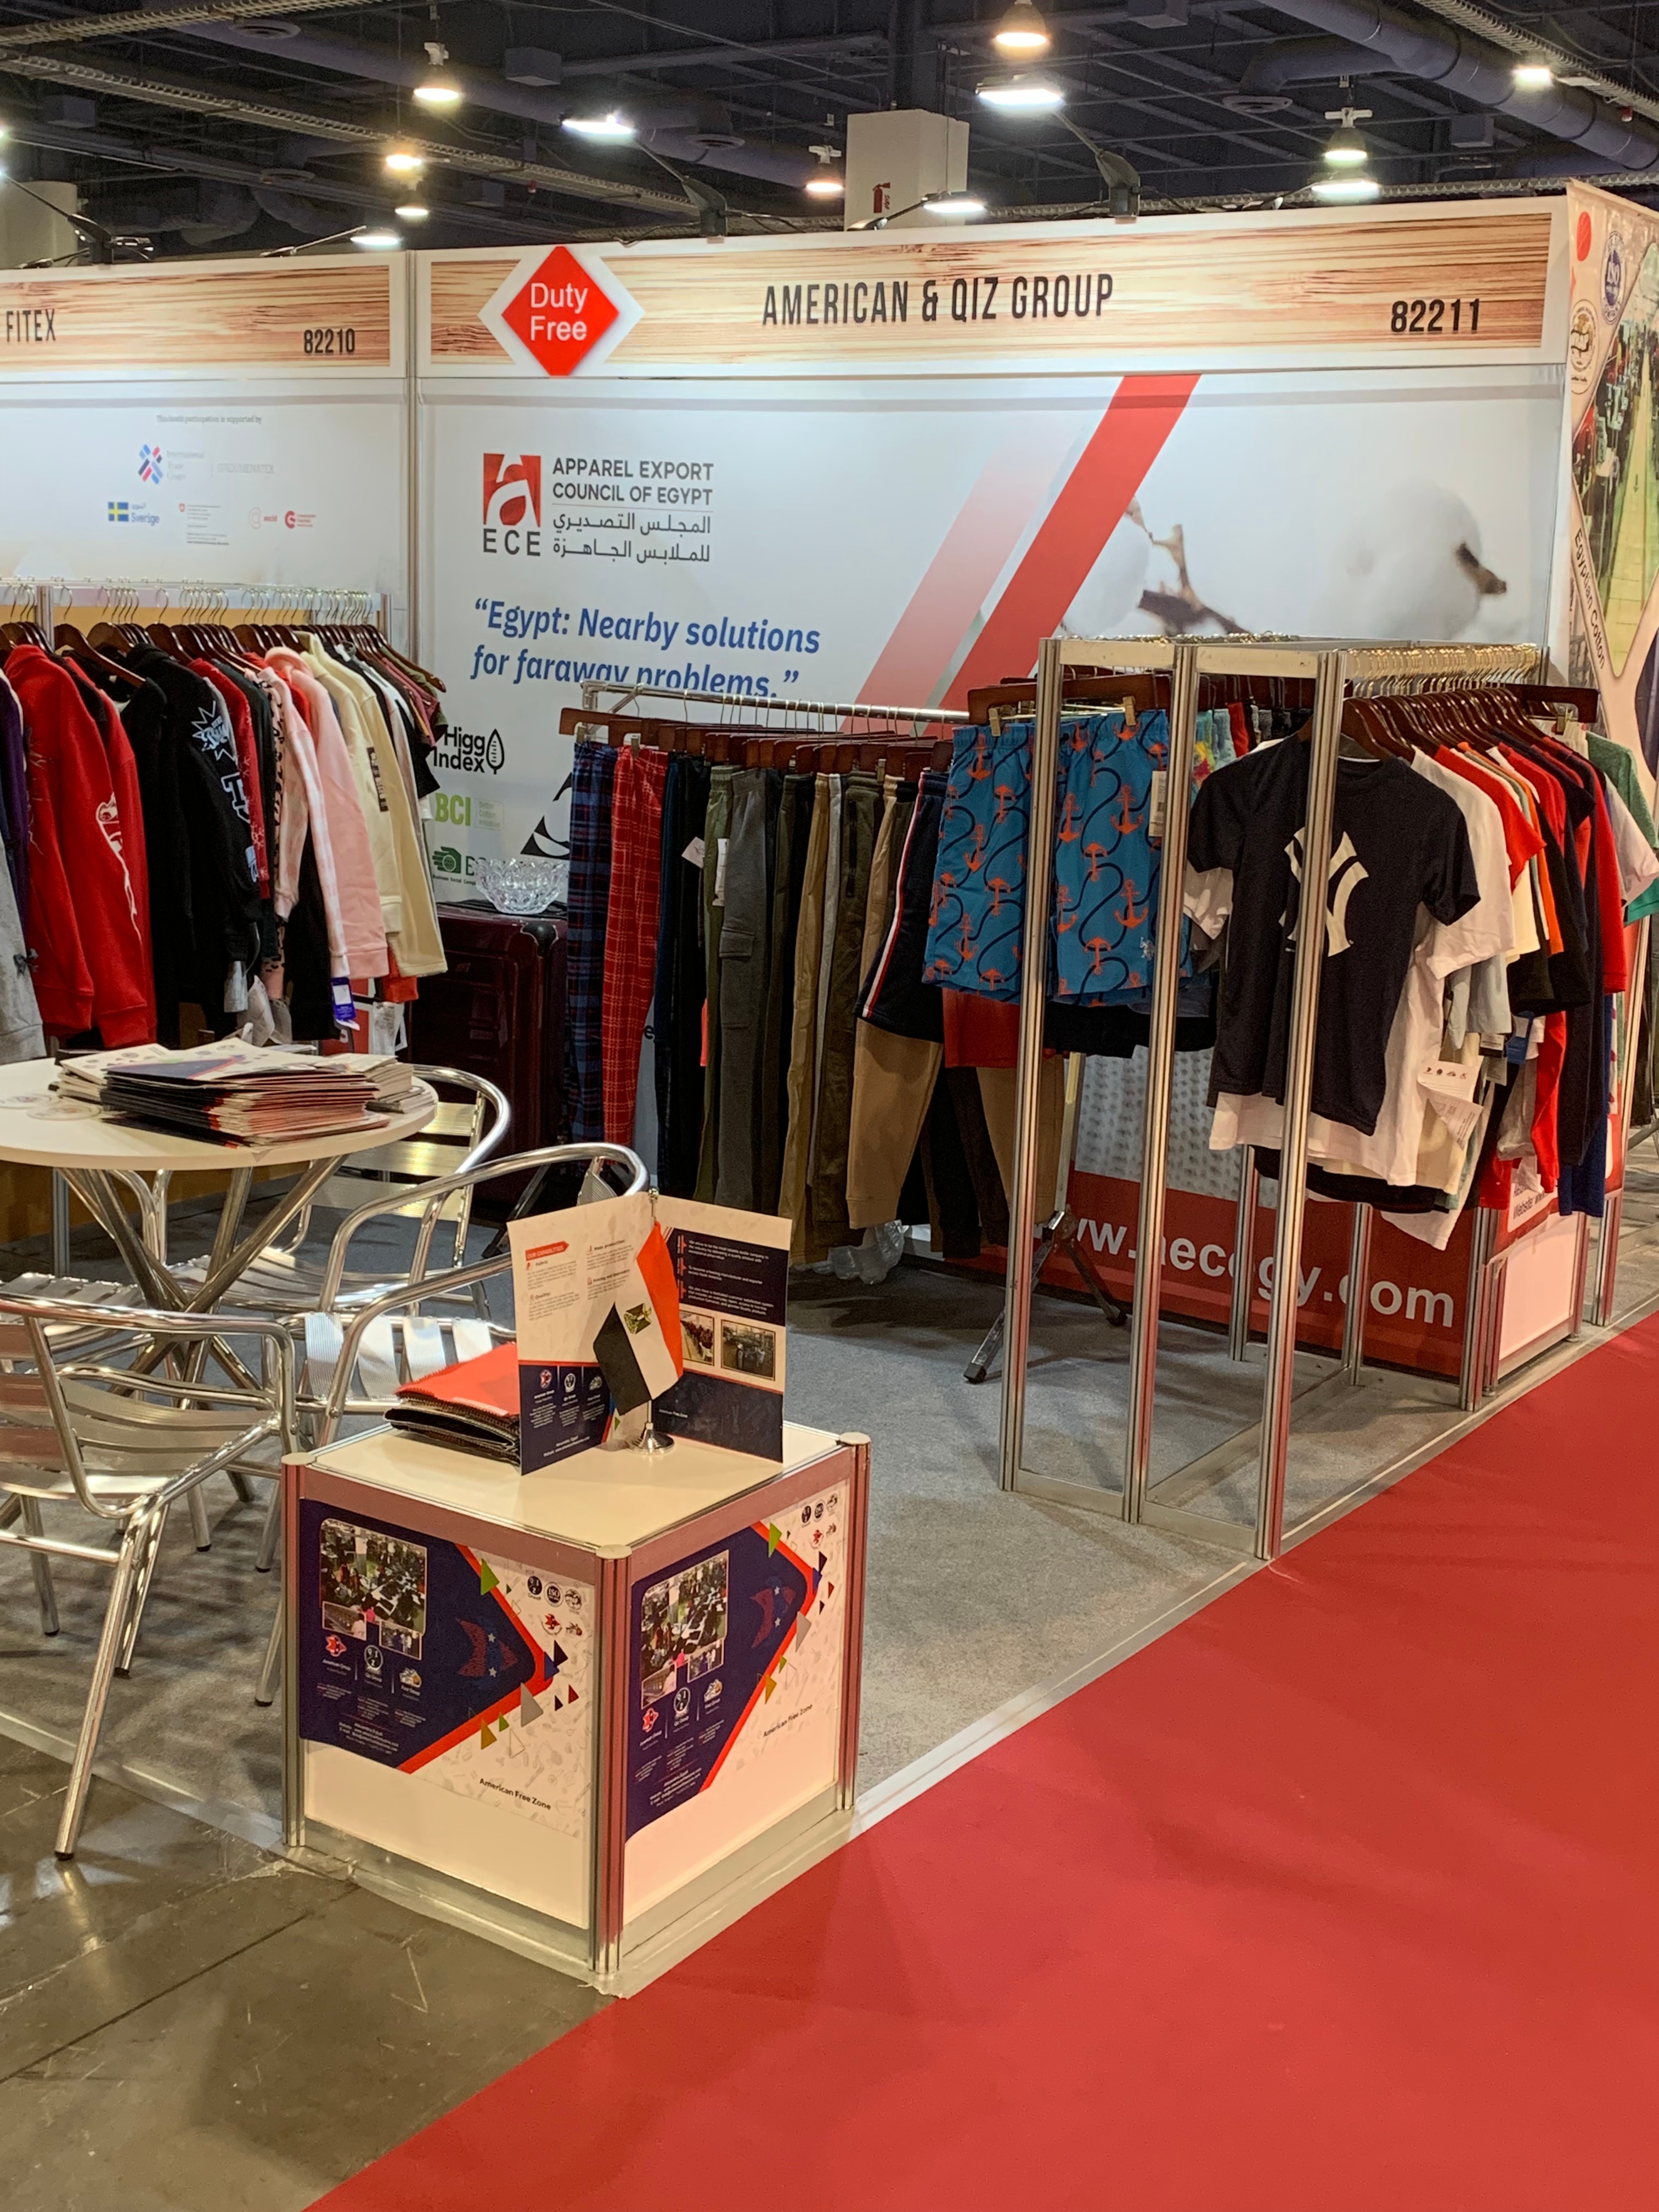
Similar to Jordan, Egypt’s apparel exports can benefit from a zero most-favored-nation (MFN) tariff, provided they meet the rules of origin under the Qualifying Industrial Zones (QIZ) initiative. However, unlike Jordan, suppliers from Egypt tend to specialize in cotton and other natural-fiber–intensive apparel, leveraging their advantages in producing locally made, high-quality natural textile fibers.

Clothing made from preferred sustainable fibers, particularly those incorporating recycled textiles, has grown increasingly popular. Nearly every country represented at MAGIC, including developing nations in Asia and Africa, showcased such products.

It should be noted, however, that producing clothing with sustainable textile fibers requires suppliers to obtain certifications such as GOTS (Global Organic Textile Standard), Global Recycled Standard (GRS), and Better Cotton Initiative (BCI). Although these certifications add costs, most vendors view sustainability as an opportunity to enhance export competitiveness rather than a threat in the long term. Some also mentioned that buyers were often willing to pay a premium for products made with sustainable materials, providing a significant financial incentive.

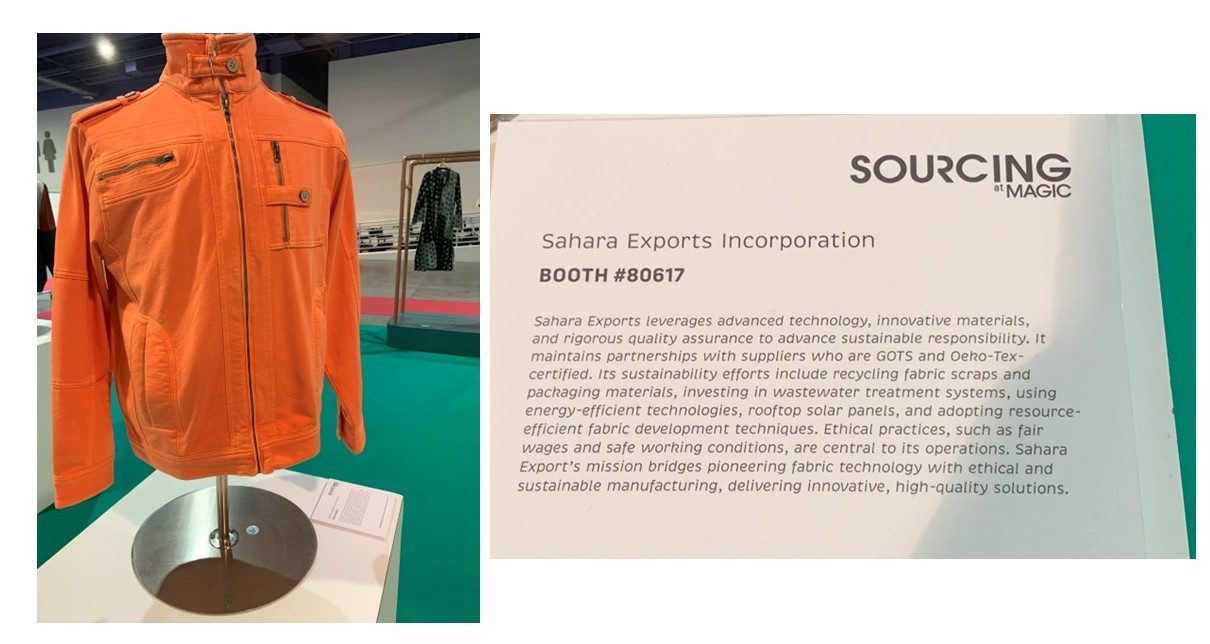
On the other hand, achieving sustainable sourcing and production is becoming increasingly comprehensive, requiring continuous innovation in both technology and business models. For example, at the show, some vendors showcased apparel products that integrated multiple sustainability concepts, ranging from material development and eco-design to social responsibility and post-consumption solutions.

by Sheng Lu

2025 USFIA Fashion Industry Benchmarking Study Released

The 2026 fashion industry benchmarking study is now available.

The full report is HERE.

Key findings of this year’s report:

#1 This year, the top business challenges facing U.S. fashion companies center on the Trump Administration’s escalating tariff policy and its wide-ranging impacts on companies’ sourcing and business operations.

  • 100 percent of respondents rated “Protectionist U.S. trade policies and related policy uncertainty, including the impact of the Trump tariffs” as one of their top business challenges in 2025. This included as much as 95 percent of respondents who ranked the issue among their top two concerns.
  • Respondents also expressed significant concerns about the wide-ranging effects of Trump’s tariff policy, including “Inflation and economic outlook in the U.S. economy” (80 percent), “Increasing production or sourcing cost” (nearly 50 percent), and “Protectionist trade policies and policy uncertainty in foreign countries, including retaliatory measures against the U.S.” (52 percent).
  • Over 70 percent of surveyed companies reported that the higher tariffs increased sourcing costs, squeezed profit margins, and led to higher consumer prices. Approximately half of the respondents reported a decline in sales, and 22 percent stated that they had to lay off employees due to increased tariffs.

#2 Maintaining a geographically diverse sourcing base has been one of the most popular strategies adopted by U.S. fashion companies to mitigate the impact of rising tariffs and policy uncertainty. 

  • This year, respondents reported sourcing apparel products from 46 countries, similar to the 48 countries reported in 2024 and an increase from 44 countries in 2023. At the firm level, approximately 60 percent of large companies with 1,000+ employees reported sourcing from ten or more countries in 2025, a notable increase from the 45–55 percent range reported in 2022 and 2023 surveys.
    • Amid escalating tariffs and rising policy uncertainty, Asia has become an ever more dominant apparel sourcing base for U.S. fashion companies in 2025. Respondents reported increased use of several Asia-based sourcing destinations other than China in 2025 compared to the previous year, including Vietnam (up from 90 percent to 100 percent), Cambodia (up from 75 percent to 94 percent), Bangladesh (up from 86 percent to 88 percent), Indonesia (up from 75 percent to 77 percent), and Sri Lanka (up from 39 percent to 53 percent).As part of their sourcing diversification strategy, U.S. fashion companies are also gradually increasing sourcing from emerging destinations in the Western Hemisphere and beyond, such as Jordan, Peru, and Colombia.
    • Most respondents intend to build a more geographically diverse sourcing base and broaden their vendor network over the next two years. Nearly 60 percent of respondents plan to source apparel from more countries, and another 40 percent plan to source from more suppliers or vendors. Reducing sourcing risk, especially to minimize the impact of rising tariffs and tariff uncertainty, is a key driver of companies’ sourcing diversification strategies

#3 U.S. fashion companies remain deeply concerned about the future of the U.S.-China relationship during Trump’s second term and intend to further “reduce China exposure” to mitigate sourcing risks.

  • While 100 percent of respondents reported sourcing from China this year, a record-high 60 percent of respondents reported sourcing fewer than 10% of their apparel products from China, up from 40 percent in 2024. Approximately 70 percent of respondents no longer used China as their top apparel supplier in 2025, representing a further increase from 60 percent in 2024 and significantly higher than the 25-30 percent range prior to the pandemic.
  • Despite the announcement of the reaching of a U.S.-China “trade deal” in May 2025, more than 80 percent of respondents plan to further reduce their apparel sourcing from China over the next two years through 2027, hitting a new record high. Many large-scale U.S. fashion companies are already limiting or plan to limit their apparel sourcing from China to a “low single-digit” percentage by 2026 or earlier, mainly due to concerns about the increasing geopolitical and trade policy risks associated with sourcing from the country.
  • Still, respondents rated China as highly economically competitive as an apparel sourcing base compared to many of its Asian competitors regarding vertical manufacturing capability, low minimum order quantity (MOQ) requirements, flexibility and agility, sourcing costs, and speed to market. However, non-economic factors, particularly the perceived extremely high risks of facing U.S. import restrictions, geopolitical tensions with the U.S., and concerns about forced labor, are driving U.S. fashion companies to continue their de-risking efforts.

#4 No evidence indicates that the Trump Administration’s tariff policy has successfully encouraged U.S. fashion companies to increase domestic sourcing of “Made in the USA” textile and apparel products or to expand sourcing from the Western Hemisphere.

  • Only about 44 percent of respondents explicitly say that they would expand sourcing from the Western Hemisphere, and even fewer respondents (17 percent) plan to source more textiles and apparel “Made in the USA” amid the tariff increase.
  • This year, fewer respondents reported sourcing apparel from Mexico and Canada (down from 60 percent in 2024 to 50 percent in 2025) and members of the Dominican Republic-Central America Free Trade Agreement, CAFTA-DR (down from 75 percent in 2024 to 64 percent in 2025).
  • About half of the respondents plan to expand apparel sourcing from Mexico and CAFTA-DR members over the next two years. Notably, nearly all of these companies also intend to increase sourcing from Asia, indicating that U.S. fashion companies view near-shoring from the Western Hemisphere as a complement, not a replacement, to their broader sourcing diversification strategy.
  • Respondents consider the most urgent capacity-building needs within CAFTA-DR lie in the production of textile raw materials (e.g., spandex) and accessories (e.g., zippers, threads, and buttons). Meanwhile, USMCA members are considered to have relatively stronger capacities in yarn and fabric production but face more pressing shortages in accessories.

#5 Respondents overall remain highly committed to sustainability, social responsibility, and compliance issues in the sourcing process.

  • This year, the top sustainability and compliance areas where respondents plan to allocate more resources include “Investing in technology to enhance supply chain traceability or isotopic testing” (53 percent), “Providing sustainability and social compliance training for internal employees” (50 percent) and “Providing sustainability and social compliance training for suppliers” (50 percent). 
  • As part of U.S. fashion companies’ sustainability efforts, all respondents (100 percent) report sourcing clothing made with “sustainable textile fibers” in 2025. Having 11–50% of apparel products containing various “sustainable textile fibers” is the most common (40 percent of respondents), followed by having 1–10% of the total sourcing value or volume(30 percent of respondents).
  • Moreover, most respondents (over 70 percent) plan to increase their use of various “sustainable fibers” in clothing over the next three years. This trend is especially strong for recycled materials, with 80 percent of respondents indicating they intend to increase their use.
  • The top three positions with the highest demand among respondents from 2025 through 2030 are “Environmental sustainability-related specialists or managers,” “Trade compliance specialists,” and “Data scientists”—more than 40 percent of respondents plan to increase hiring. There is also strong demand for “Textile raw material specialists” and “Sourcing specialists.”

#6 With the upcoming expiration of the trade preference program this September, respondents again underscore the importance of immediate renewal of the African Growth and Opportunity Act (AGOA) and extending the agreement for at least another ten years.

  • Due to the upcoming expiration of AGOA and uncertainty about its future, this year, respondents sourced from only six SSA and AGOA members (i.e., Kenya, Ethiopia, Ghana, Madagascar, Mauritius, and Tanzania), fewer than the seven countries in 2024.  And none of these countries were used by more than 20 percent of respondents.
  • Nearly 80 percent of respondents support “renewing AGOA for at least another ten years,” and no one opposes. This shows a consistent and wide base of support for AGOA among U.S. fashion companies.
  • More than 70 percent of respondents say that securing a long-term renewal of AGOA for at least ten years is essential for expanding apparel sourcing from the region. Similarly, another 60 percent of respondents believe that a long-term renewal of AGOA is necessary for U.S. fashion companies and their supply chain partners to commit to new investments in the region. 
  • Respondents warned that AGOA’s pending renewal has already begun to harm the region’s prospects as an apparel sourcing base. Approximately 30 percent of respondents explicitly stated that they had already reduced sourcing from AGOA members due to the uncertainty surrounding the agreement’s renewal.

About the study

Authored by Dr. Sheng Lu in collaboration with the United States Fashion Industry Association (USFIA), this year’s benchmarking study was based on a survey of executives from 25 leading U.S. fashion companies from April to June 2025. The study incorporated a balanced mix of respondents representing various businesses in the U.S. fashion industry. Approximately 85 percent of respondents were self-identified retailers, 60 percent were self-identified brands, and about 50 percent were importers/wholesalers.

The survey respondents included large U.S. fashion corporations and medium-sized companies. Around 90 percent of respondents reported having over 1,000 employees; the rest (10 percent) represented medium-sized companies with 100-999 employees.

Average Tariff Rates for U.S. Apparel Imports under Trump’s “Reciprocal Tariff” Policy (Updated July 2025)

The latest data from the U.S. International Trade Commission (USITC) indicates that Trump’s “Reciprocal Tariff” has led to higher import duties on U.S. apparel imports, although the impact on sourcing appears to be more nuanced than expected. Specifically:

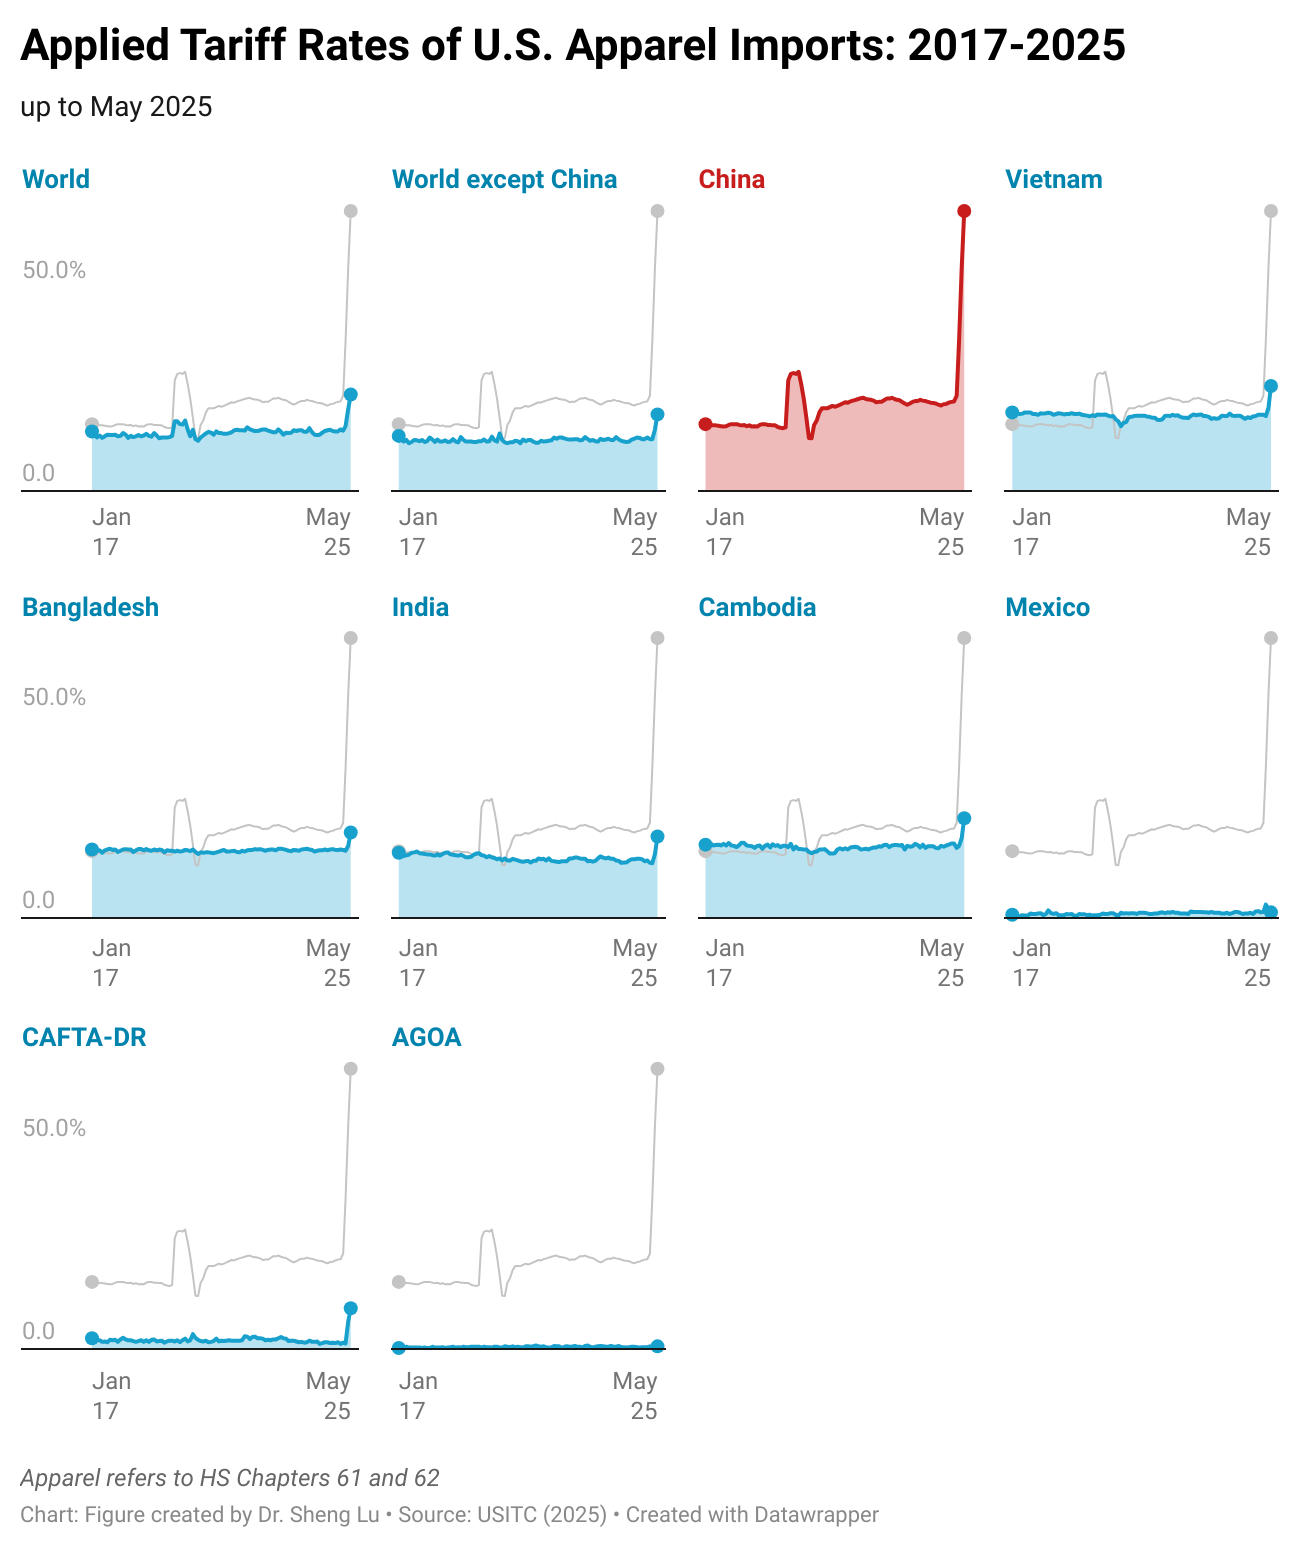
As a result of the reciprocal tariff, the average tariff rate for U.S. apparel imports (HS Chapters 61 and 62) reached 23.8% in May 2025, increased further from 20.8% in April 2025 and much higher than 13.9% in May 2024 and 14.7% in January 2025, prior to Trump’s second term. This tariff rate also hit its highest level in decades. Similarly, while the value of U.S. apparel imports in May 2025 decreased by 7% from May 2024, the import duties skyrocketed by nearly 60% over the same period. [View detailed data HERE]

Due to numerous punitive tariffs beginning in February 2025, the average tariff rate for U.S. apparel imports from China reached an unprecedented 69.1% in May 2025, a further increase from 55.0% in April 2025, 37.0% in March 2025 and 22.1% in January 2025. In theory, U.S. apparel imports from China in May should be subject to a tariff rate of over 145%, as mandated by a series of executive orders. However, as “goods loaded onto a vessel at the port of loading and in transit on the final mode of transit before 12:01 a.m. eastern daylight time on April 5, 2025,“ were excluded from Trump’s reciprocal tariffs, it explains why the actual tariff rate in April and May 2025 appeared lower than the theoretical one.

Nonetheless, affected by the high tariffs, the value of US apparel imports from China in May 2025 was cut by more than half from a year ago (down 52%). China’s market share in US apparel imports in May 2025 also dropped to 9.9%, a new low in decades (note: was 19.9% in May 2024). [View detailed data HERE]

Additionally, the average tariff rate for U.S. apparel imports from countries other than China reached 18.9% in May 2025, up from 15.2% in April 2025. Although this rate was higher than approximately 12-13% before Trump’s second term in early 2025, the increase was still much more modest than the theoretical 10% universal reciprocal tariff rate announced by the Trump administration. The average tariff rates for U.S. apparel imports from leading Asian suppliers such as Vietnam, Bangladesh, and Cambodia followed similar patterns (i.e., higher tariff rates but well below a 10% increase). Similar to China’s case, it appears that U.S. apparel imports from other countries in April 2025 included a significant proportion of products that were exempt from reciprocal tariffs because they were “loaded onto a vessel” early enough. [View detailed data HERE]

It is interesting to note that the reciprocal tariff resulted in the most significant increase in tariff rates on U.S. apparel imports from CAFTA-DR members. While imports from these countries were supposed to be duty-free under the trade agreement, the average tariff rate reached 10% in May 2025, up from 6.7% in April 2025. In other words, the short shipping distance unintentionally “disadvantaged” near-shoring imports from being exempted from the reciprocal tariffs, as they could be mostly loaded after the deadline.

Overall, it remains uncertain how the U.S. apparel tariff rates will continue to evolve in response to Trump’s shifting tariff policy. It appears that the trade volume and timing of shipment will be highly sensitive to short-term tariff rate changes, whereas adjusting sourcing bases and product structures will be a consideration for U.S. fashion companies in the medium to long term.

By Sheng Lu

Additional reading: Apparel Tariffs Climbed to Historic Highs in April (Sourcing Journal, June 13, 2025)

[This blog post is no longer open for discussion and comment]

Impacts of Trump’s Escalating Tariffs on Apparel Sourcing: U.S. Fashion Companies’ Perspective

Updated study available: Updated Impact of Increasing Tariffs on U.S. Fashion Companies’ Sourcing and Businesses (October 2025)

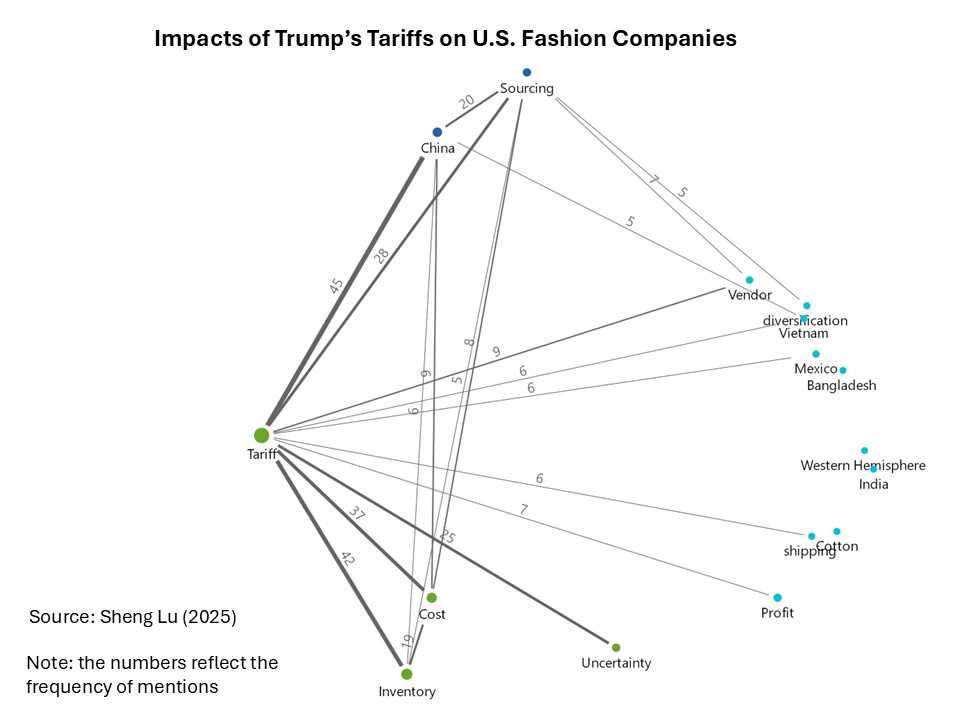
(Note: The figure above shows how frequently the term “tariff” was mentioned alongside other key issues in the earnings calls. A higher frequency indicates a more significant impact and a closer connection between tariffs and a specific theme.)

This study aims to examine the impacts of the Trump administration’s escalating tariffs on U.S. fashion companies’ apparel sourcing practices. Based on data availability, transcripts of the latest earnings calls from approximately 25 leading publicly traded U.S. fashion companies were collected. These earnings calls, held between mid-May and June 2025, covered company performance in the first quarter of 2025. A thematic analysis of the transcripts was conducted using MAXQDA.

Overall, the results indicate that the Trump administration’s escalating tariffs and policy uncertainties have financially hurt U.S. fashion companies and disrupted their apparel sourcing practices. To mitigate these impacts, most companies plan to further reduce their “China exposure,” maintain a geographically diversified sourcing base, and prioritize flexibility in sourcing and shipping. However, there is no clear evidence that the current policy environment has successfully incentivized U.S. companies to expand apparel sourcing from the Western Hemisphere, let alone commit to new long-term investments. Meanwhile, U.S. fashion companies have adopted a strategic pricing approach by not passing the entire cost increase to consumers through widespread retail price hikes.

A few key findings:

First, far from surprising, many leading U.S. fashion companies expressed concerns that the Trump administration’s escalating tariffs have resulted in higher sourcing costs and cut companies’ profit margins. For example:

  • Company G (specialty store): if current tariffs of 30% on most imports from China and 10% on most imports from other countries remain for the balance of the year, we estimate a gross incremental cost of approximately $250 million to $300 million.
  • Company O (a parent company of several leading apparel brands): We expect that gross margin will contract approximately 200 basis points for the year. This contraction includes $40 million in additional tariff costs.
  • Company V1 (underwear brand): gross tariff impact of approximately $120 million, which assumes 30% China tariffs and 10% non-China, with tariff mitigation of approximately $70 million for a net impact to fiscal year 2025 of approximately $50 million.

Second, with the hiking tariff rate on U.S. apparel imports from China and increasing strategic competition between the two countries, many leading U.S. fashion companies plan to reduce their apparel sourcing from China to a single-digit, if not move out of the country entirely. For example:

  • Company A1 (apparel brand): We’re on track to reduce our sourcing exposure to China to under 10% this year with fall and holiday season down to low single digits.
  • Company A2 (specialty store): For China specifically, we have worked for some time now to relocate the supply resources, and this year’s sourcing volume from China will be in the low single digits.
  • Company L (apparel brand): Less than 8% of our purchase order dollars last fiscal year were utilized on buys of China.
  • Company O (a parent company of several leading apparel brands): By the second half of 2026, we currently plan to be substantially out of China.
  • Company V2 (a parent company of several leading apparel brands): over the past several years we’ve strategically diversified our supply chain and proactively reduced our US finished goods sourced from China to less than 2%.
  • Company K2 (a parent company of several leading apparel brands): China for us is de minimis.

Third, maintaining a geographically diverse sourcing base remains a popular strategy for U.S. fashion companies to mitigate the impacts of increasing tariffs and ongoing policy uncertainties. Companies particularly intend to avoid “putting too many eggs in one basket” and limiting the reliance on any single supplying country. For example:

  • Company K1 (retailer): our talented and experienced global sourcing team has done an incredible job diversifying our countries of production to ensure that we are not overly reliant on any one country. Although tariffs remain a fluid and uncertain situation, the teams continue to work to reduce our exposure to high tariff countries by leveraging our diverse factory network to move production, adjusting orders based on pricing elasticity analysis.
  • Company G (specialty store): Most other countries represent less than 10%, Vietnam and Indonesia represented 27%, and 19% of our sourcing last year, respectively, and our goal is for no country to account for more than 25% by the end of 2026.
  • Company R (apparel brand): While tariffs will primarily impact our gross margins… we have a proven toolkit to manage cost inflation headwinds. This includes first, significant supply chain diversification…No single country accounts for more than 20% of our production volumes, with most countries representing a single-digit percentage.
  • Company U (retailer): The remaining third is strategically diversified across a number of other countries, each representing a low to mid-single-digit percentage. This deliberate diversification creates a well-balanced portfolio, reducing reliance on any single market and enhancing our ability to navigate geopolitical, costs and supply chain complexities from a position of strength.

Notably, while a limited few companies specifically mentioned the possibility of expanding sourcing from the Western Hemisphere amid the current business environment, most did not. For example:

  • Company L (apparel brand): We intentionally drove significant change in our supply chain as we accelerated production in the Western Hemisphere, giving us both speed and additional avenues to mitigate tariffs and provide resiliency.
  • Company G (specialty store): Diversification also means near-shoring as well as domestic investment.

Fourth, U.S. fashion companies have leveraged shipping timing, piled up inventory, and delayed or cancelled existing orders to mitigate the tariff impacts as much as possible. For example:

  • Company C (sportswear): For products that are impacted by the reciprocal tariffs, we are accelerating shipments to the extent possible in order to receive products during the 90-day tariff.
  • Company K1 (retailer): Inventory was up 1.7% compared to last year, driven by inventory strategies implemented to navigate the tariff pressure, including the pull forward of receipts and pack in holding seasonal inventory to be sold in the back half of the year.
  • Company B (off-price retailer): Our reserve inventory was 48% of our total inventory versus 40% of our inventory last year. In dollar terms, our reserve inventory was up 31% compared to last year, reflecting the great deals we were able to make to get ahead of tariffs.
  • Company M (retailer): With the recent announcement of these tariffs, we’ve renegotiated orders with suppliers, and we’ve canceled or delayed orders where the value proposition is just not where it needs to be.

It should be noted, however, that adjusting shipping and inventory could incur additional costs. For example:

  • Company V1 (underwear brand): More than half of the gross margin rate pressure in the quarter was due to a combination of elevated and expected airfreight rates, some tariff-related order adjustments…

Fifth, despite higher sourcing costs and increasing financial pressures, many U.S. fashion companies have avoided widespread price hikes but have implemented selective increases in less price-sensitive apparel categories. For example:

  • Company V1 (underwear brand): [price increase driven by higher tariffs] And so we are going to sort of play in the middle where we see value. So and it won’t be across all categories. As we think about our business, it’s really that strategic case by case, category by category look that we’re taking.
  • Company U (retailer): gently and sparingly raising some prices. Please note that any price increases will be very strategic, protecting opening price points and only targeting areas where we believe we could raise prices without affecting the overall customer experience.
  • Company A2 (specialty store): we are not planning broad-based ticket increases. As we’ve done season after season, our goal is to deliver high-quality product and align inventory and promotions with our customers’ value perception.
  • Company P (a parent company of several leading apparel brands): We will evaluate strategic discounts to mitigate the potential tariff impact. While we are focused on delivering price value for the consumer, we are also ready to take calibrated targeted pricing actions where we have pricing power.

by Sheng Lu

Additional reading: Tariffs Upend Fashion Sourcing and Disrupt Cash Flow Amid Widening Trade Gap (Sourcing Journal, June 27, 2025)

FASH455 Exclusive Interview with Matthias Knappe, Head of Fibres, Textiles and Clothing Unit, International Trade Centre

About the interview

Textile and apparel trade matters. Even today in the 21st century, apparel could still account for 80—90% of a developing country’s total merchandise export and play a critical role in promoting economic growth, poverty reduction, and gender equality. The interview explored several key topics:

  • Why textile & apparel trade matters for development in the 21st century
  • How ITC provides capacity building support and enhances the export competitiveness of garment exporters in developing countries
  • Sustainability movement’s impact on apparel sourcing and export competitiveness of developing countries
  • The promise and complexity of circularity in tackling used clothing challenges
  • Empowering women entrepreneurs through SheTrades
  • Skills and education needed to thrive in the global fashion apparel trade

About Matthias Knappe (speaker)

Matthias Knappe is the Head of Fibres, Textiles and Clothing Unit at the International Trade Centre (ITC), which is co-run by the World Trade Organization (WTO) and the United Nations (UN). Matthias has over 30 years of diversified professional experience in international trade and development. He has worked at the enterprise, institutional, and governmental levels. Matthias is leading ITC’s textile and apparel and light manufacturing unit. Over the last 20 years, he has been working with the T&C sector around the world to increase its export competitiveness. He designed and currently manages ITC’s Global Textiles and Clothing (GTEX) programme and various other fibre, apparel and light manufacturing projects. The Unit’s present portfolio includes projects in 15 countries.

About Emilie Delaye (moderator)

Emilie Delaye is a master’s student in Fashion and Apparel Studies at the University of Delaware, with a specific interest in supply chain, global sourcing, and sustainability. With a background in Entrepreneurship and Fashion Management, Emilie’s passion lies in improving the fashion industry through innovative problem-solving and collaboration. She has worked on projects exploring sourcing destinations and emerging sourcing trends, as well as collaborated with Macy’s on an initiative centered around Extended Producer Responsibility (EPR) regulations. Emilie’s work is driven by a commitment to fostering innovation and ethical practices in fashion, positioning her as a future leader in driving the industry toward greater sustainability and responsibility.

Impacts of Tariffs: Gen Z’s Perspective

In a new Just-Style mini series, students from FASH455 and the FASH department at the University of Delaware shared their valuable Gen Z perspectives on the impact of the recent tariff increases.

Students’ responses reveal that the impacts of the tariff increase on ordinary U.S. consumers are real, direct, and significant. Like other consumer groups, our Gen Z students express deep concern about the adverse effects of tariffs on the U.S. economy, market uncertainties, and the fashion industry’s growth prospects this year. While shopping for clothing, many students have noticed price increases and reduced product availability due to tariff hikes and related disruptions.

On the other hand, as Gen Z consumers, students send a strong message to fashion brands and retailers—sustainability still matters. In fact, in this environment, students have become ever more conscious of sustainability, asking critical questions such as: Do I really need to buy more clothing? Where was the clothing made? Was the clothing produced ethically? In other words, we may see a growing shift toward “slow fashion” among Gen Z consumers, who expect apparel brands and retailers to make even stronger commitments toward sustainability and social responsibility, instead of compromising these values for “cost mitigation.”

Likewise, students expect higher-quality products or items that can last longer to justify the higher price they pay. Regularly shopping for secondhand clothing, driven by its affordability, environmental benefits, and unique styles, could also become increasingly popular. This leaves an interesting question about the future of cheap but low-quality fast fashion and its attractiveness among Gen Z consumers.

The mini series is available through Just-style. Below are selected comments from students:

Gen Z consumers care about tariffs in the news

Rachel Zemel (Fashion Merchandising and Management major): As a Fashion Merchandising and Management major, I’ve definitely been paying closer attention to how tariffs impact what we see on the sales floor. Learning about global sourcing and trade agreements in class has made me more curious about where products are coming from and how political or economic shifts can directly affect the retail industry. I’ve caught myself checking clothing labels more often to see where things are made and understand why certain brands are shifting their production away from countries like China. I think what used to feel like a distant conversation now feels very connected to the way I shop and think about product availability.

Annabelle Gensler (Fashion Merchandising & Management and Fashion Design & Product Innovation double majors): The tariff discussion has been far more impactful on my shopping habits than I would have imagined…I’d like to consider myself a thoughtful consumer in that I rarely make impulse purchases, and I do what I can to avoid feeling any sense of buyer’s remorse. This has become exceptionally true in today’s evolving state of trade policy and manifests itself in a few ways…As a fashion student, I have a good understanding of what constitutes a fair price for fashion and apparel goods. I try to use these strengths of mine by paying close attention to fiber content, care instructions, origin of materials, and manufacturing location. Overall, I’d say the tariff discussion makes me think twice, three times, ten times before making a purchase.

Alexandra Untu (Fashion Merchandising and Management and Philosophy double majors): As a fashion student and fashion lover, I closely follow tariff updates and actively try to educate myself to gain a more objective and informed perspective on the changes introduced by the current administration. Although I started shopping more consciously a while ago, I’m now more intentional than ever with my purchases…I pay attention to where clothes are made and take the time to research their country of origin and production practices. I’ve also been focusing on buying pieces made from high-quality materials, with timeless styles that are versatile enough to be worn in different outfits and settings.

Lola Kulis (Fashion merchandising and management major and 4+1 graduate student): As a Fashion Merchandising student, I’ve been especially invested in the ongoing discussion around tariffs and their impact on retail pricing. From an industry perspective, it’s scary; as someone preparing to enter the field, I feel uncertain about what the future holds. And as a consumer, I feel frustrated. We’re facing the direct impact of global trade decisions influencing the pricing and accessibility of apparel. The worst part is the uncertainty. The constant policy changes and back and forth are only putting more stress on business owners, consumers, the working class, etc.. The media coverage surrounding these trade policies has made me realize how interconnected global sourcing and retail pricing really are. I’ve started paying closer attention to where garments are manufactured and how those origins might impact cost, availability, and even quality. I’ve shifted my perspective, not only as a student but also as a consumer. 

Madison Toth (Fashion Merchandising and Management major): The tariff discussion in the media has definitely increased my interest in where exactly my clothing is being made. As I shop, I have started to check labels on where these apparel items are being manufactured. It is fascinating to me that the most popular and successful U.S retailers are globally sourcing apparel, yet the increase in tariffs is being thrown into policy. Admittedly, I struggle to keep up with the news, but I’m very intrigued by the current tariff discussion. I follow closely because it will affect my job in the future as I enter my career in the fashion industry, but also as a consumer.

Price hikes and reduced product availability due to tariffs concern Gen Z consumers

Rachel Zemel (Fashion Merchandising and Management major): Since April, I’ve definitely noticed price increases…I’ve also noticed a shift in product availability, especially when I shop online. Certain sizes and styles are gone faster than usual and don’t seem to get restocked. In stores, the selection feels limited too. It seems like brands are being more careful with how much they’re producing, maybe to avoid excess inventory or reduce risk. As someone who shops a lot and also studies this industry, it’s interesting to see how these challenges are playing out in real-time. It makes me think differently about what goes into every piece I buy.

Annabelle Gensler (Fashion Merchandising & Management and Fashion Design & Product Innovation double majors): The majority of the shopping I’ve done since April has occurred online, and the biggest difference I’ve noticed since the tariff discourse has started, is the stock of goods available. It’s rare that I stumble upon a product offering that has all sizes and colors in-stock. Now, when I filter my search for a graduation dress in the size and color I prefer, fewer and fewer items populate. In the past, retailers might have been able to bulk order goods to maintain stock domestically, or ship from international locations directly to the consumer; tariffs have halted these practices. Items I’m considering purchasing no longer feel safe in my cart because of how quickly stockouts are occurring. This, paired with an expectation of drastic increases in price, has created an internal sense of urgency when I have items in my cart. I know it’s unlikely that the item will be available at a certain price point, or at all, and so the conscious consumerism I try to practice is really being put to the test.

Alexandra Untu (Fashion Merchandising and Management and Philosophy double majors): Based on my own and my friends’ experience, the changes have been subtle so far, but noticeable. Prices have been going up gradually across all types of products, including clothing, but the availability of products hasn’t yet turned into a cause for concern. While the current situation is not dramatic as of now, there is undoubtedly a change that is happening, and we are expecting more striking changes in the near future that could affect our shopping behavior quite significantly.

Madeline Osbourn (Fashion Merchandising and Management major): The tariff increase has affected merchandise orders for my sorority. The tariffs have made the prices rise on orders that we planned on making. This creates an issue with prepaid and future orders, keeping in mind the members’ willingness to transition and conform to the higher-priced merchandise that is designed.

Lola Kulis (Fashion merchandising and management major and 4+1 graduate student): Because inflation has been on the rise for some time now, it’s hard to differentiate the cause of these price changes. Prices for basics, like denim, cotton tops, and even activewear, are outrageously high. Over the past year, I’ve observed a significant decline in promotional activity. Retailers are offering fewer discounts, and even Black Friday, once known for major deals, felt noticeably underwhelming. Considering the current global trade and policy changes, I only see this worsening. On the availability side, popular sizes and color options tend to sell out much more quickly, leading to a more competitive shopping experience.

Madison Toth (Fashion Merchandising and Management major): To be honest, I have been reluctant to shop with popular fashion retailers because of the current tariff discussions. I have strayed away from shopping online and in-store due to the uncertainty of the economic climate. While apparel prices are increasing, as well as other products, it is vital for me to take all of that into consideration. Tariffs affect more than apparel, and as a college student, some purchases take priority over clothing. Because of this, I am unable to comment on price and product availability since the tariff discussion began. I have simply decided that, for me personally, in the current economic climate, apparel shopping should be placed on the back burner.

Sustainability matters even more

Rachel Zemel (Fashion Merchandising and Management major): Sustainability matters even more to me now. When prices go up, it forces me to think about the long-term value of what I’m buying. I want to spend my money on items that are made with quality materials and with people and the planet in mind. It’s hard to justify spending more on something that was cheaply made or won’t last beyond a few wears. I think price increases actually help push the conversation toward more conscious consumption. Even with a student budget, I try to prioritize brands that are transparent about their production or at least make some effort toward ethical practices. It’s not always possible to buy 100% sustainably, but I try to balance things. thrifting, supporting small designers, and not overconsuming are just a couple of changes that can have a big impact. Sustainability isn’t just about buying the “right” thing, it’s about shifting the way we shop. That mindset doesn’t go away just because prices are rising.

Alexandra Untu (Fashion Merchandising and Management and Philosophy double majors): Sustainability has always been a core value for me, and that won’t change, even if prices rise. Sustainability isn’t just a trend; it goes far beyond money – it’s a life-or-death issue. It’s a moral responsibility we have to future generations, and we shouldn’t treat it lightly or abandon it. Shopping with sustainability in mind isn’t always the easiest or the cheapest route, but it’s the right one. Now, more than ever, we should be doing -or learning to do – the right thing. Every purchase sends a message about the change we want to see. Every purchase is a small step toward a better, more responsible future for us and for our children.

Lola Kulis (Fashion merchandising and management major and 4+1 graduate student): Sustainability matters even more to me in the face of rising prices. As clothing becomes more expensive, we become more hesitant in purchasing. I think more about what I’m investing in, starting with being intentional about supporting brands that are transparent, responsible, and committed to reducing their environmental impact. I’d rather buy less and choose more wisely than spend more on items that contribute to overproduction and waste. I’ve realized more than ever that sustainability is not a trend, it’s our future. As I prepare to enter the fashion industry, it’s important that I practice what I preach and support the long-term goals.

Madison Toth (Fashion Merchandising and Management major): Sustainability is something that I do genuinely care about. When shopping, I tend to lean more towards brands that practice ethical sourcing and are more transparent about where their items come from. From my time as a student, I have learned many of the horrible outcomes of the fashion industry related to sustainability. From seeing videos of workers begging for higher wages, seeing dyes dumped into bodies of water, and looking at the incredibly tall piles of textile waste, it sticks with me both as a student and a consumer…If a price increase meant that apparel manufacturers were getting paid fair wages, I would purchase those items. However, now, due to tariffs, I am more likely to dodge popular retailers. Sustainability is very important to my generation, and I value the efforts that brands have made to become more sustainable. But it raises the question, when is a price so high that sustainability no longer matters? To that, it’s hard to say. I think it depends on the economic status of each consumer. From sustainable companies with higher prices, there are purchases that I just cannot justify paying. I do care about sustainability, but there does come a point where it becomes financially unattainable.

Katie Yasik (Fashion Design and Product Innovation major): Yes, sustainability still matters to me, even with rising prices. It’s not always easy to prioritize, especially on a student budget, but I try to make more conscious choices like buying fewer, longer-lasting pieces or shopping secondhand. I think it’s important to consider the environmental and social impact of fast fashion, and if prices are going up anyway, I’d rather invest in something that aligns with my values.

Isabella DiGiulio (Fashion merchandising and management major and 4+1 graduate student): I think that the tariffs may bring a new wave of interest in sustainability, specifically for donation-based, second-hand clothing stores. These stores will likely be able to maintain their low pricing because they do not need to account for operational expenses in apparel production. Even if there is to be a price increase, their prices may still remain relatively lower and more affordable compared to first-hand clothing brands…Furthermore, sustainable shopping doesn’t solely refer to purchasing second-hand goods or buying from brands with biodegradable fabrics or ethical labor practices. Sustainable shopping can also refer to the abstinence from shopping. With influences such as social media and fast fashion, overconsumption has become an extremely normalized practice through which many people, especially Gen Z, feel compelled to consistently refresh their wardrobes to follow trends and keep up with the ever-changing standards of style and identity.

Explore more:

FASH455 Current Event Discussion: Ongoing Tariff War and Apparel Sourcing and Trade (Updated April 2025)

Video 1: Is U.S. Clothing Manufacturing at Risk? Tariffs and Competition Threaten Jobs (RT≠ Endorsement)
Video 2: Northern Virginia T-shirt brand faces challenges (RT≠ Endorsement)
Video 3: Tariffs could raise wedding dress prices for American brides (RT≠ Endorsement)
Video 4: Bangladeshi garment industry sweating on Trump tariffs (RT≠ Endorsement)
Video 5: Trump’s Tariff Twist: Can Pakistan’s Textiles Fill China’s Shoes? (RT≠ Endorsement)
Video 6: Tariffs: Europe’s textile sector holds its breath

For FASH455 class: When writing your blog comment, consider addressing the following aspects:

#1 Based on the videos, how do you expect the apparel sourcing strategy of US fashion companies to evolve in response to the tariff increase? For example, will companies continue to diversify sourcing, wait and see, or focus on expanding sourcing to countries or regions regarded as “safe havens”?

#2 Do you expect the higher tariffs on U.S. imports, including textiles and apparel, to benefit domestic “Made in the USA” production? Why or why not?

#3 As consumers, how do you perceive the impact of the tariffs on your shopping behavior and experiences? Have you noticed any changes, such as in price and product availability, while shopping for clothing recently? Feel free to share your observations.

#4 Are there any other notable impacts of the tariff increase on the global fashion apparel industry that we should be aware of? What additional questions do you have in mind about the tariff impacts?  

Patterns of U.S. Apparel Sourcing and Imports (updated April 2025)

The following analysis was based on the latest trade statistics from the Office of Textiles and Apparel (OTEXA) under the U.S. Department of Commerce.

First, the growth of U.S. apparel imports significantly slowed as fashion companies shifted from eagerly piling up stock to the wait-and-see mode. Specifically, in February 2025, U.S. apparel imports moderately went up 3.2% in value and 1.5% in quantity, much lower than the 18-19% increase seen in late 2024 and January 2025. The much-slowed growth confirmed that the earlier U.S. apparel import surge was largely driven by fashion companies’ worries about the upcoming tariff hikes rather than an actual increase in consumer demand.

Adding to the concern, U.S. consumer confidence fell sharply, which could lead to a steep drop in U.S. apparel imports ahead. For example, the Consumer Confidence Index dropped to a two-year low of 92.9 in March 2025, down from 100.1 the previous month (1985=100). Similarly, the Expectations Index—which measures consumers’ short-term outlook for income, business, and labor market conditions—plunged to 65.2, marking its lowest level in 12 years. With the announcement of reciprocal tariffs and the growing likelihood of an economic recession, U.S. consumer demand for clothing may decline significantly, potentially leading to the cancellation of many sourcing orders.

Second, apparel imports have become more expensive. Measured in dollars per square meters equivalent (SME), the unit price of U.S. apparel imports averaged $3.06/SME in the first two months of 2025, up from $3.03/SME a year ago (or a 1.3% increase). The unit price of U.S. apparel imports from many leading Asian countries rose at a notably higher rate, including China (up 2.9%), Vietnam (up 3.6%), and Bangladesh (up 2.6%), as well as those from Mexico (up 4.7%) and CAFTA-DR (up 0.6%). This result reflected the growing pressure of sourcing and production costs facing U.S. fashion companies and their suppliers, driven by rising labor costs and raw material prices among other factors. Indeed, if Trump’s reciprocal tariffs ultimately take effect, import prices could increase even more significantly.

Third, U.S. fashion companies’ sourcing diversification efforts appeared to slow amid rising uncertainty. In February 2025, Asian countries collectively accounted for 71.5% of the total value of U.S. apparel imports—unchanged from a year earlier. Similarly, in the first two months of 2025, the top five suppliers (China, Vietnam, Bangladesh, Cambodia, and India) made up 63.7% of total apparel imports by value, up from 59.7% during the same period in 2024. Even China’s market share remained largely stable at 18.4% in value and 32% in quantity, compared to a year ago.

These figures suggest that U.S. fashion companies somehow have become more hesitant to adjust their sourcing base in response to the universal tariffs imposed by the Trump administration, which target nearly all U.S. trading partners. As a result, U.S. fashion companies may find the sourcing diversification strategies no longer as effective as in the past in effectively mitigating their sourcing risks.

Meanwhile, data from the United Nations (UN Comtrade) show that Asian countries’ dependence on the U.S. market for apparel exports varied. In 2024, Vietnam, Sri Lanka, and ASEAN members exported about 40% of their apparel to the U.S., whereas the U.S. accounted for only about 20% of China’s and Bangladesh’s total apparel exports to the world. At the same time, the U.S. remained the single largest export market for Mexico and CAFTA-DR members, due to the integrated Western Hemisphere textile and apparel supply chain.

Fourth, no evidence shows that the current trading environment has benefited from near-shoring from the Western Hemisphere. On the contrary, measured in quantity, in February 2025, only 7.6% of U.S. apparel imports came from CAFTA-DR members, a notable drop from 9.6% a year ago. Similarly, Mexico accounted for 2.3% of U.S. apparel imports in February 2025, also lower than 2.4% a year earlier.

As a silver lining, the utilization rate of CAFTA-DR reached 81.1% in 2025 (January to February), much higher than 73.8% over the same period in 2024. About 75.3% of U.S. apparel imports from CAFTA-DR in 2025 (January to February) complied with the yarn-forward rules of origin compared to 67.4% a year ago. However, the use of “short-supply” remained low–only about 2.0% in 2025 so far.

by Dr. Sheng Lu

Related analysis: Lu, S. (2025). Patterns of U.S. Apparel Imports in 2024. Global Textile Academy, International Trade Centre, Geneva, Switzerland.

State of U.S. Textile and Apparel Manufacturing, Employment and Trade (updated April 2025)

Textile and apparel manufacturing in the U.S. has significantly decreased over the past decades due to factors such as automation, import competition, and the changing U.S. comparative advantages for related products. However, thanks to companies’ ongoing restructuring strategies and their strategic use of globalization, the U.S. textile and apparel manufacturing sector has stayed relatively stable in recent years. For example, the value of U.S. yarns and fabrics manufacturing (NAICS 313) totaled $24 billion in 2023 (the latest data available), up from $23.3 billion in 2018 (or up 2.8%). Over the same period, U.S. made-up textiles (NAICS 314) and apparel production (NAICS 315) moderately declined by only 1.8% and 1.6%.

More importantly, the U.S. textile and apparel manufacturing sector is evolving. Several important trends are worth watching:

First, “Made in the USA” increasingly focuses on textile products, particularly high-tech industrial textiles that are not intended for apparel manufacturing purposes.  Specifically, textile products (NAICS 313+314) accounted for over 83% of the total output of the U.S. textile and apparel industry as of 2023, much higher than only 56% in 1998 (U.S. Census, 2025). Textiles and apparel “Made in the USA” are growing particularly fast in some product categories that are high-tech driven, such as medical textiles, protective clothing, specialty and industrial fabrics, and non-woven. These products are also becoming the new growth engine of U.S. textile exports. Notably, between 2019 and 2022, the value of U.S. “nonwoven fabric” (NAICS 31323) production increased by 12.32%, much higher than the 1.15% average growth of the textile industry (NAICS 313). Similarly, while U.S. textile exports decreased by 13.75% between 2019 and 2024, “nonwoven fabric” exports surged by 10.48%--including nearly 40% that went to market outside the Western Hemisphere (U.S. International Trade Commission, 2025).

Second, U.S. apparel manufacturers today are primarily micro-factories, and they supplement but are not in a position to replace imports. As of 2021 (the latest data available), over 76% of U.S.-based apparel mills (NAICS 315) had fewer than 10 employees, while only 0.7% had more than 500 employees. In comparison, contracted garment factories of U.S. fashion companies in Asia, particularly in developing countries like Bangladesh, typically employ over 1,000 or even 5,000 workers.

Instead of making garments in large volumes, most U.S.-based apparel factories are used to produce samples or prototypes for brands and retailers.  In other words, replacing global sourcing with domestic production is not a realistic option for U.S. fashion brands and retailers in the 21st-century global economy. Nor are U.S. fashion companies showing interest in shifting their business strategies from focusing on “designing + managing supply chain+ marketing” back to manufacturing.

Meanwhile, due to mergers and acquisitions (M&A) and to leverage economies of scale, approximately 5% of U.S. textile mills (NAICS313) had more than 500 employees as of 2021–this is a significant number, considering that textile manufacturing is a highly capital-intensive process.

Third, employment in the U.S. textile and apparel manufacturing sector continued to decline, with improved productivity and technology being critical drivers.  As of 2024, employment in the U.S. textile and apparel manufacturing sector (NAICS 313, 314, and 315) totaled 270,700, a decrease of 18.4% from 33,190 in 2019. Notably, U.S. textile and apparel workers had become more productive overall—the labor productivity index of U.S. textile mills (NAICS 313) increased from 89.7 in 2019 to 94.4 in 2023, and the index of U.S. apparel mills (NAICS 315) increased from 105.8 to 110.78 over the same period.

On the other hand, clothing retailers (NAICS 4481) accounted for over 75.7% of employment in the U.S. textile and apparel sector in 2024.

Fourth, international trade, BOTH import and export, supports textiles and apparel “Made in the USA.” On the one hand, U.S. textile and apparel exports exceeded $12.5 billion in 2024, accounting for more than 30% of domestic production as of 2023 (NAICS 313, 314 and 315). Thanks to regional free trade agreements, particularly the U.S.-Mexico-Canada Agreement (USMCA) and the Dominican Republic-Central America Free Trade Agreement (CAFTA-DR), the Western Hemisphere stably accounted for over 70% of U.S. textile and apparel exports over the past decades. However, for specific products such as industrial textiles, markets in the rest of the world, especially Asia and Europe, also become increasingly important. Thus, lowering trade barriers for U.S. products in strategically significant export markets serves the interest of the U.S. textile and apparel industry.

On the other hand, imports support textiles and apparel “Made in the USA” as well. A 2023 study found that among the manufacturers in the “Made in the USA” database managed by the U.S. Department of Commerce Office of Textile and Apparel, nearly 20% of apparel and fabric mills explicitly say they utilized imported components. Partially, smaller U.S. textile and apparel manufacturers appear to be more likely to use imported components–whereas 20% of manufacturers with less than 50 employees used imported input, only 10.2% of those with 50-499 employees and 7.7% with 500 or more employees did so. The results indicate the necessity of supporting small and medium-sized (SME) U.S. textile and apparel manufacturers to more easily access their needed textile materials by lowering trade barriers like tariffs.

By Sheng Lu

FASH455 Exclusive Interview with Ally Botwinick, Textile Assistant at The Kasper Group, about Textile Raw material Sourcing and Management

About Ally Botwinick

Hi! My name is Ally Botwinick, and I am a University of Delaware alum who studied Fashion Merchandising and completed the 4+1 master’s program in Fashion and Apparel Studies. I am currently working as a Textile Assistant at The Kasper Group in NYC. The Kasper Group is a portfolio of global fashion brands such as Nine West, Anne Klein, Kasper, Le Suit, and Jones New York. I work on fabric sourcing and production for the Jones New York brand as well as denim fabrics for all brands within the Kasper Group.

Note: During her studies in the FASH 4+1 program, Ally participated in several research and experiential learning projects. She co-authored Explore PVH Corporation’s Evolving Apparel Sourcing Strategies, published in Just-style, a leading industry publication focusing on apparel trade and sourcing. Her master’s thesis, which examined US retailers’ merchandising strategies for clothing made from recycled textile materials, was published in the International Journal of Fashion Design, Technology, and Education. Ally was also a UD summer scholar and a key member of the FASH students team that helped Macy’s develop a vision of its sustainable apparel sourcing strategy (see featured UDaily story and Yahoo).  Additionally,  Ally was a policy intern for the American Apparel and Footwear Association (AAFA) in Washington, D.C. in the summer of 2022.

Disclaimer: The views expressed in this interview are those of Ally Botwinick and do not reflect the views or positions of her employer or any affiliated organizations.

Sheng: What are your main responsibilities as a textile assistant? What does a typical day look like? What aspects of the job do you find particularly interesting or unexpected before taking on the role?

Ally: My main responsibility as a Textile Assistant is to help buy and keep track of all fabric orders for Jones New York as well as denim for multiple brands within the Kasper Group. Jones New York has both a mainline division, which is sold at retailers such as Macy’s and Dillard’s, as well as an off-price division called Jones New York Signature which is sold at off-price retailers such as TJ Maxx, Marshall’s, Burlington, Ross, etc..

During a typical day, I communicate with textile mills/factories overseas about fabric approvals or rejections based on fabric color, quality, and hand feel. For each fabric order that we place, we have the mills submit fabric references to our New York office for review. Each morning, I process these submissions and work with my team to release comments to the mills. The color must match the color standard we send them at the beginning of production. The fabric quality must match the fabric standard that we approved upon booking the fabric.

We keep track of all these approvals and rejections in what is called a fabric WIP (work in progress) chart, where we keep track of each order for each season and division. This WIP chart includes key fabric information, price, production timelines, and fabric submit status, among other order details. Creating and updating these fabric WIPs is something I do continuously throughout the day as I receive updates from mills and factories.

I frequently work with cross-functional partners, like members of the design, production, costing, and color teams, and touch base about any changes to design boards, production schedules, costing, or color issues that may arise.

One of the most interesting aspects of the job is the number of teams that collaborate on a daily basis, especially when there are updates made to the fashion collection, such as changes to color names, production units, production schedules, fabric details, and costs.

Sheng: In general, what factors should be considered when selecting textile raw materials, such as fabrics, in product development and sourcing?

Ally:Some important factors to consider when selecting fabrics are hand feel (whether the fabric feels soft, dry, smooth, rough, etc…) and price.  We want to ensure the fabric provides comfort to the consumer and that it will drape well according to the garment design. We work very closely with the design and costing teams when sourcing fabrics as we must ensure fabrics are functional, stylish, on-brand, and meet margin goals.

We highly consider the fiber content as well. Fiber costs can be influenced by a multitude of factors, even including the weather or occurrence of natural disasters which can affect supply and demand. We also closely monitor cotton traceability as there are forced labor concerns with cotton grown in parts of China. We require each mill supplying fabrics made with cotton to submit a cotton traceability certificate for us to track the cotton’s origins. This way, we can ensure no cotton is being produced in association with forced labor.

Sheng: What are the main processes involved in selecting and sourcing textile raw materials like fabrics?

Ally:At my company, the Fabric Research & Development team is more involved in finding new fabrics, whereas my team is more involved in fabric buying and production. The design and R&D team usually hand off the desired fabrics to us after sourcing, and we go ahead and buy the fabric. We buy fabric yardage according to the number of units (garments) in the collection, accounting for the different sizes and colorways.

However, we do occasionally get involved in the sourcing aspect as well. When we source fabrics, we consider the factors I mentioned such as cost, quality, and fiber content. We also think about how we may want to elevate and bring newness to the brand.

When adding certain washes or finishes to fabrics, the appearance can change, so this is something we consider as well. When purchasing a new novelty fabric such as a new jacquard, velour, or cross-dye, we expect the mill to tell us if there is a certain inherent characteristic we should know about prior to booking. For example, a mill might tell us the fabric is known to flare a bit, and this is hard to control, or it tends to shrink a little when washing. This way, we can decide whether the fabric is acceptable based on our needs. If we decide to purchase, we then collaborate with internal cross-functional partners about creating a level of tolerance accounting for these inherent characteristics.

Upon booking any fabric, we always require mills to fill out a fabric detail sheet with information such as cuttable width, weight, price, MOQ (minimum order quantity), lead time, etc… and we have them send us a fabric header which becomes our fabric standard. The design team will also request a sample garment to ensure the fabric is suitable for the garment. All these processes are essential for booking fabric.

Sheng: Where do textile raw materials typically come from, or which countries or regions mostly supply textile raw materials for US fashion companies today?

Ally:Some of the top countries supplying fabric for U.S. fashion companies include China, Vietnam, South Korea, and India. Also, from my observation, Asia plays a significant role as a leading textile raw material supplier for many leading U.S. apparel brands and retailers.

Sheng: From your observation, how has sustainability influenced the selection and sourcing of textile materials for fashion companies? What emerging trends are worth watching?

Ally:From my observation, sustainability is becoming more and more important to brands and consumers alike. Recycled polyester is on the rise as more consumers are paying attention to the materials in their clothing and trying to lessen their environmental impact. Recycled polyester seems easier to incorporate rather than, say, recycled cotton, which is harder to trace back to the source and has quality concerns. I see recycled materials on the rise in my company, and as someone who wrote my master’s thesis on this topic, it is very exciting and encouraging to see.

Sheng: Based on your experience, can you offer any advice to our students regarding preparing for a career in the fashion apparel industry? What could they do at UD?

Ally:Some advice I would give to students preparing for a career in the fashion industry is to think about what classes at UD most intrigued and inspired them. There are so many different career paths within the fashion industry, whether it be design, product development, sales, merchandise planning, costing, garment sourcing, fabric sourcing, merchandise buying, etc… Whatever you are most passionate about, go after it. Also, keep an open mind. You may find a great opportunity that you hadn’t previously considered, and you may end up loving it. There is so much to be learned in any given role, especially when starting out. Throughout my role, I have learned not only the ins and outs of the fabric production cycle, but also the entire garment life cycle. I can see how all the teams within my organization work together to achieve a common goal.

UD has so many amazing resources to utilize for planning your future career. First, take advantage of the career center by meeting with a career counselor and updating your resume and LinkedIn. Next, consider doing a research project with a professor on a topic you are passionate about. There are so many professors in the fashion department who would be happy to chat about research opportunities, and having this experience can really help you stand out during the job search and interview process. Internships and retail experience are also great ways to gain work experience while in school. Lastly, lean on your network. If an alum you know has a career that sounds interesting to you, reach out to them and ask them for a quick phone call to learn more about it. It is great to build your network and learn more about different potential career paths. Overall, my greatest advice is to truly enjoy your college years- they go by so fast. Make the most of your time at UD, pursue your passions, and remember that exciting opportunities lie ahead!
–The End–

Gap Inc.’s Evolving Apparel Sourcing Base: 2021-2024

Gap CEO talks tariff impacts (Feb 2025)

Established in 1969, Gap Inc. is a leading American clothing retailer that operates several prominent brands, including Old Navy, Gap, Banana Republic, and Athleta, catering to diverse consumer segments.

The following analysis is based on Gap Inc.’s publicly released factory list. Only factories identified as producing “apparel” products were included in the analysis.

First, like several other leading U.S. fashion companies, Gap Inc. maintained a geographically diverse global sourcing base but reduced the number of factories it sourced from between 2021 and 2024. Specifically, as of October 2024 (the latest data available), Gap Inc. sourced apparel from 24 countries, an increase from 21 countries as of March 2021. Gap Inc.’s apparel sourcing reached almost all continents, including Asia, the Americas, Europe, and Africa.

However, between March 2021 and October 2024, Gap Inc. decreased the number of apparel factories it contracts with from 548 to 502, a reduction of 46. Most of the cuts occurred in China (down 40 factories), Vietnam (down 32 factories), and Cambodia (down 8 factories).  This pattern aligned with the findings of other industry studies, which indicate that many U.S. fashion companies, particularly larger ones, are consolidating their vendor base to prioritize operational efficiency and strengthen the relationships with key vendors.

Second, Gap Inc. has significantly reduced its reliance on China and actively explored emerging sourcing destinations in the rest of Asia, Central America and beyond. According to Gap Inc.’s 2023 annual report (the latest available at the time of writing), its two largest vendors represented approximately 9 percent and 7 percent of the total dollar amount of the company’s purchases. In value terms, in 2023, approximately 29 percent of Gap Inc.’s products were sourced from Vietnam, followed by Indonesia (18 percent).

While China remained the largest source of U.S. apparel imports according to official trade statistics, China now plays a relatively minor role in supplying finished garments for Gap Inc. As of October 2024, the company sourced apparel from 36 factories in China, representing just 7.2 percent of its total apparel sourcing base, making China only the sixth-largest supplier after Vietnam, India, Indonesia, Bangladesh, and Sri Lanka. In an interview conducted in early 2025 (the video above), Gap Inc.’s CEO disclosed that less than 10 percent of the company’s products are sourced from China.

On the other hand, between March 2021 and October 2024, Gap Inc. expanded its sourcing network beyond the traditional top three (China, Vietnam, and Bangladesh), with significant growth in other parts of Asia and Central America, led by India (added 8 more factories) and Guatemala (added 9 more factories).  In 2022, Gap Inc. pledged to source around $150 million in apparel products each year from Central America by 2025.

Third, Gap Inc.’s apparel sourcing base varies by product category. For example, approximately 45% of the company’s contract factories producing denim and woven bottoms were located in Vietnam and Bangladesh, likely due to the availability of cotton and a relatively abundant low-cost labor force. In contrast, factories in Sri Lanka primarily manufactured intimates, performance wear, and swimwear (IPSS) for Gap Inc. Meanwhile, half of the company’s sweater factories were located in China, largely due to the complex manufacturing process and raw material requirements for these products. Additionally, India played a critical role as a sourcing base for Gap Inc.’s woven apparel.

Furthermore, Gap Inc.’s contract garment factories worldwide vary in size, reflecting the company’s diverse sourcing needs. Specifically, in Asia, garment factories in China are typically small or medium-sized, with fewer than 1,000 workers (94.3%). In contrast, nearly 80% of Gap Inc.’s contract garment factories in Bangladesh have more than 1,000 workers, with similar patterns observed in Vietnam (48.7%), India (50%), Indonesia (63.2%), and Pakistan (57.1%). This pattern aligns with other industry studies suggesting that U.S. fashion companies source apparel products from China primarily for orders with relatively small minimum order quantities (MOQs) and those requiring a great variety.

Meanwhile, most garment factories in Central American countries producing products for Gap Inc. have fewer than 1,000 workers, such as Guatemala (100%), Nicaragua (71%), Haiti (67%), and El Salvador (100%). A similar pattern is observed in other regions, such as Egypt (67%) and Turkey (82%). This result suggests that Gap Inc. may still need to rely on Asia to fulfill orders for large-volume items, as it takes time to expand production capacity in other regions.

by Sheng Lu

VF Corporation’s Evolving Apparel Sourcing Base: 2023-2024

VF Corporation (VF) is one of the largest apparel companies in the US, with an estimated global sales revenue to exceed $10 billion in 2024. VF owns several well-known apparel and outdoor performance brands, including The North Face, Timberland, and Icebreaker. VF also has a global presence. According to its latest annual report, in Fiscal 2024, “VF derived 52% of its revenues from the Americas, 33% from Europe, and 15% from Asia-Pacific.”

The following analysis is based on VF’s publicly released supplier list. Only factories identified as producing “apparel” products and related textile raw materials are included in the analysis.

First, while VF maintained a geographically diverse global sourcing base, it reduced the number of factories it sourced from between 2023 and 2024. Specifically, as of Q3 2024 (the latest data available), VF sourced apparel from 36 countries, the same number as in Q1 2023. These countries spanned almost all continents, including Asia, the Americas, Europe, and Africa. Similarly, over the same period, VF sourced textile raw materials for apparel production—including factories producing polymers—from approximately 30 countries.

However, between Q1 2023 and Q3 2024, VF reduced the number of apparel factories it contracts with from 463 to 426. The number of textile mills VF contracts also declined, from 665 to 546. This pattern aligned with the findings of other industry studies, which indicate that many U.S. fashion companies, particularly larger ones, are consolidating their vendor base to reduce sourcing risks and enhance operational efficiency.

Additionally, VF’s annual reports indicate that no single supplier accounted for more than 6% of its total cost of goods sold during Fiscal Year 2024, the same as in 2023, but lower than 7% in Fiscal Year 2021.

Second, in line with macro trade data, Asia served as VF’s largest apparel sourcing base in Q3 2024, led by China (23.1 percent) and Vietnam (11.5 percent). Specifically, as of Q3 2024, approximately 55.3 percent of VF’s garment factories were located in Asia, an increase from 48.8 percent in Q1 2023. Meanwhile, VF is also adjusting its apparel sourcing strategy within the Asia region. For example, between 2023 and 2024, VF decreased the number of garment factories it worked with in China (down 5), Bangladesh (down 12), and India (down 17), while adding more contract factories in Vietnam (up 36), Cambodia (up 7), and Indonesia (up 4).  The pattern indicates that while VF may attempt to reduce its “China exposure,” it also actively seeks new sourcing opportunities within Asia. 

Conversely, in Q3 2024, around 21.2 percent of VF’s garment factories were based in the Western Hemisphere, a decrease from 27.0 percent in Q1 2023. In most situations, VF worked with about 10-20 garment factories in each Western Hemisphere country. Furthermore, from 2023 to 2024, VF cut the number of garment factories in Mexico (down 16) and the United States (down 10), indicating that expanding near-shoring and on-shoring was not the company’s preferred strategy in the current environment. 

Third, compared to garments, VF’s supply of textile raw materials relies even more heavily on Asia, especially China. Specifically, as of Q3 2024, approximately 83.5 percent of VF’s textile raw material suppliers were located in Asia, the same as in Q1 2023. Notably, China represented nearly half of VF’s textile material suppliers in Q3 2024, including 41.2 percent of textile yarn and fabric mills and 50.9 percent of trim mills. Although VF reduced the number of textile mills in China from Q1 2023 to Q3 2024, China’s share of VF’s total textile raw material supplier base remained the same. Overall, the pattern aligns with previous research suggesting that finding alternative sourcing bases for textile raw materials outside of China and Asia will be more difficult and time-consuming for US fashion companies, considering the capital-intensive nature of making textile products.

Fourth, VF’s contract garment factories worldwide varied in size, reflecting the company’s diverse sourcing needs. Specifically, in Asia, garment factories in China typically were small and medium-sized, with 11-100 workers (43.9 percent) or 101-500 workers (33.7 percent). In contrast, nearly 90 percent of VF’s contract garment factories in Bangladesh had more than 1,000 workers, with similar patterns observed in Vietnam (52.2 percent), Cambodia (50.0 percent), Indonesia (63.2 percent), and Pakistan (100 percent). These findings suggest that VF may use China as a sourcing base for relatively small, diverse orders while relying on other Asian countries with lower labor costs for high-volume production.

Meanwhile, in the Americas and Africa, VF’s contract garment factories in Haiti, Honduras, El Salvador, Kenya, and Jordan included more large-scale operations with over 1,000 workers. These locations could serve as emerging alternatives to sourcing from Asia, especially for specific categories. In contrast, VF’s contract garment factories in Mexico, the US, and Guatemala featured many medium and small operations, which are more likely to fulfill replenishment orders or produce specialized products.

by Sheng Lu

FASH455 Exclusive Interview with Hannah Laurits, Fabric Lab Textile Coordinator at Swim USA, about Fabrics and Apparel Sourcing

About Hannah Laurits

Hello! My name is Hannah Laurits, and I am currently working as a Textile Lab Fabric Coordinator at Swim USA. I graduated from the Master of Science program in Fashion and Apparel Studies at the University of Delaware in 2024. Through the program, I had the opportunity to work on various research projects, ranging from adaptive apparel to sustainable textiles. During my time at UD, I also had the privilege of teaching Fash133 Foundations for Fashion Innovation, which was an incredibly rewarding experience.

In addition to my master’s degree, I hold a Bachelor of Science in Apparel Design and Fashion Merchandising from the University of Delaware. Throughout my academic journey, I completed internships related to textiles and sourcing, which played a significant role in shaping my career and led me to my current position at Swim USA. I am passionate about the intersection of textile innovation, sustainability, and sourcing, and I’m excited to share insights from my experiences in the industry.

Disclaimer: The views expressed in this interview are those of Hannah Laurits and do not reflect the views or positions of her employer or any affiliated organizations.

Sheng: What are your main responsibilities as a fabric lab textile coordinator? What does a typical day look like? Which aspects of the job do you find particularly interesting or unexpected before taking on the role?

Hannah: As a Fabric Lab Textile Coordinator, I work to ensure that the fabrics that go into our products meet both our internal quality standards as well as the standards of our customers and the global textile industry. In the lab, we mainly focus on quality control, which includes ensuring that the fabrics we use in production meet specific quality standards.

In my role, a typical day may include visually and/or digitally reviewing colors to ensure that they align with our established standards. Additionally, each day consists of a variety of testing and analysis of results to ensure that they meet brand requirements. I also assist with raw materials development, particularly in the areas of color and fabric testing for various brands. One key aspect of my work is analyzing testing data to identify risks, areas for improvement, and potential delays in production. The best part of my role is the variety of tasks I’m involved in, the opportunity to work on multiple brands, and the extensive cross-functional collaboration I get to participate in. From color matching and testing to analyzing data and working directly with various teams, no two days are ever the same. The level of collaboration across departments has been extremely helpful, allowing me to learn from different areas of the business and broaden my skill set.

Sheng: In general, what factors should be considered when selecting fabrics in product development and apparel sourcing?

Hannah: When selecting fabrics for product development and sourcing, there are many factors to consider, including but not limited to cost, quality, durability, color and dyeing process, fiber content, intended use, sustainability, lead times, availability, and compliance with regulations. In my role, understanding the fabric composition, color, and dyeing process, as well as the intended final use is essential. Different fibers and dyestuffs have inherent properties that can affect the fabric’s appearance and colorfastness, so it’s crucial to understand how they will perform in the final product. This knowledge helps determine whether achieving a specific color while maintaining the desired quality is feasible. By carefully considering these factors, we ensure that the product meets both aesthetic and performance standards.

Sheng: Part of your job involves testing fabrics. What needs to be tested, and what are the main issues involved in the quality control of fabrics?

Hannah:A large part of my role involves testing fabrics to ensure they meet the required standards. There are a variety of tests that need to be completed, and they generally fall into two main categories: color fastness and physical properties. Color fastness testing is conducted to ensure that the fabric retains its color and/or does not run when exposed to various factors, such as washing, sunlight, or exposure to chlorine. Physical property testing helps ensure that the fabric will meet the required performance standards. This includes testing for qualities like weight, stretch, and dimensional stability. These tests are essential to make sure the final product fits well and performs as expected for the consumer.

Sheng: From your observation, how has sustainability impacted the selection and sourcing of textile materials for fashion companies? How is “sustainability” assessed for fabrics? What emerging trends are worth watching?

Hannah: Sustainability is a major focus in the textile and apparel industry, continuously evolving and shaping how fashion companies approach textile research, development, and sourcing. There is a noticeable shift towards prioritizing eco-friendly materials and minimizing environmental footprint. Sustainability can be assessed in many ways in fabrics throughout a fabric’s entire lifecycle – from raw material sourcing to end-of-life disposal. It is important to consider not only the environmental impact but also the social and ethical aspects of fiber cultivation and fabric production, ensuring that workers’ rights are also prioritized. From what I have observed in the market, the most accessible and widely adopted sustainable fabrics tend to be recycled, organic, or plant-based materials. However, there are many other emerging trends worth watching. These include waterless or low-water dyeing technologies, eco-friendly finishes and treatments, regenerative agriculture, and innovative fiber development. 

Sheng: Following up on the previous question, is it true or a myth that sustainable fabrics are typically more expensive and increase production costs? If so, how can companies balance sustainability with cost-effectiveness?

Hannah:While sustainable fabrics can sometimes be more expensive, it’s not always the case. Factors such as higher initial investments in sustainable technologies, costs of production, the smaller scale of production, and the costs associated with certifications can make sustainable fabrics more costly. However, it is still possible for companies to balance sustainability with cost-effectiveness. Sustainable practices often bring long-term benefits, such as risk reduction, improved durability, and increased brand value. Further, as more brands shift towards and invest in sustainable material innovation, we can expect these fabrics to become more affordable and available over time.

Sheng: Based on your experience, can you offer any advice to our students regarding preparing for a career in the fashion apparel industry? What could they do at UD? What is the benefit of getting a master’s degree in fashion and apparel?

Hannah: My advice to students is to get involved as much as possible. Internships are a great way to gain hands-on experience. If internships aren’t available, networking and learning from professionals in the industry are invaluable. At UD, there are numerous opportunities to take advantage of, like research projects, clubs, and career fairs to build connections and expand your knowledge. I have found that a master’s degree in Fashion and Apparel has provided me with a strong foundation which has helped me secure a career and be successful in the industry. I often find myself referring to course topics and key skills I learned in graduate school such as data analysis.

Additionally, if any students soon graduating are interested in Swim USA, below is information from our HR department on how they search for talent. “For entry-level roles, we typically use Handshake as a great way to reach upcoming graduates or recent alumni. I would advise them to register and look at opportunities there. If they haven’t already, they should also ensure their LinkedIn profile is up to date and has a nice professional picture. Start following companies that you might be interested in, like SWIM USA, to see new or open roles first. They are also welcome to follow our Swim USA careers page for more information.”

–The End–

Recording: Due Diligence Education for Gen Z: Preparing Future Fashion Leaders for Sustainable and Socially Responsible Apparel Sourcing (2025 OECD Forum Side Session)

About the Event

As the fashion industry grapples with increasing demands for sustainability, transparency, and social responsibility, the next generation of industry professionals—Generation Z—will play a crucial role in shaping the future of apparel sourcing and social responsibility practices in the industry.

This session explores how US college fashion programs equip Gen Z with critical knowledge in due diligence, sustainable sourcing, and supply chain transparency. Including voices from educators, Gen Z students (future professionals), and industry partners, the session will share best education practices, identify educational gaps, and present valuable Gen Z’s vision for improving due diligence and social responsibility in the garment industry. Additionally, the session will emphasize the increasing importance of industry-academic partnerships in curriculum development and talent preparation, illustrating the long-term benefits of such collaboration.

This session is highly relevant to industry professionals, educators, students, international organizations, and policymakers interested in supporting the next generation of fashion leaders and fostering a more socially responsible and sustainable fashion industry.

Panelists (Bios here)

  • Matthias Knappe, Head of Fibres, Textiles and Clothing Unit, International Trade Center
  • Laurie Rando, Senior Director of Sustainable Product and Human Rights, Macy’s
  • Julia Hughes, President, United States Fashion Industry Association
  • Megan Dawson-Elli, Manager of Product Sustainability, Tapestry
  • Sheng Lu, Professor & Graduate Director, Fashion and Apparel Studies, University of Delaware
  • Emilie Delaye, Master’s Student, Fashion and Apparel Studies, University of Delaware

This event is an official side session of the 2025 OECD Forum on Due Diligence in the Garment and Footwear Sector.

FASH455 Video Discussion: The Global Journey of a Sneaker

Discussion questions [Please address at least two questions in your comment]

#1: Based on the video and our class discussion, what would be the advantages and disadvantages for Nike to make Converse shoes leveraging a global supply chain?

#2: Assume you are an experienced U.S. shoe worker. What arguments would you present to Nike’s sourcing executives to produce Converse in the United States?

#3: In your opinion, are protective tariffs worth the economic and foreign policy consequences? Why or why not?

#4: The “hidden costs” of global trade (e.g., emissions, labor conditions) are often obscured from consumers. How can brands like Converse address these “hidden costs” while maintaining market competitiveness? What specific policies or regulatory measures should governments implement to promote responsible sourcing and enhance supply chain transparency?

[Discussion is closed]

FASH455 Video Discussion: This ‘Loophole’ Lets $54B of Products Into the U.S. Tariff-Free (WSJ)

Discussion questions:

  1. What makes the de minimis rule controversial?
  2. Who might be the winners and losers of the suspension of the de minimis provision for U.S. imports from China? Why?
  3. Imagine you are part of the sourcing department of a U.S.-based fashion company that currently sources from China. How would you respond to the situation in the video, and what recommendations would you make regarding your company’s sourcing strategies?
  4. Do you have any other thoughts or reflections on the video?

Additional reading:

FASH455 Video Discussion: The State of Textiles and Apparel “Made in Asia” (Updated February 2025)

Video 1: Threads of Resilience: China’s textile manufacturing goes automated
Video 2: Asian factories struggling to keep young workers
Video 3: How Millions Of Jeans Get Recycled Into New Pairs in Pakistan
Video 4: Vietnam becomes second biggest garment exporter globally

Discussion questions:

#1 How are textiles and apparel “Made in Asia” changing their faces? What are the driving forces of these changes?

#2 How would you assess Asia’s competitiveness as a hub for textile and apparel production and sourcing in the next five years? Why? What relevant factors could come into play?

#3  Is there anything else in the videos that you find interesting, intriguing, thought-provoking, or debatable? Why?

(FASH455: this post is for in-class discussion only; please do not leave your comment)

Outlook 2025–Key Issues to Shape Apparel Sourcing and Trade

In December 2024, Just-Style consulted a panel of industry experts and scholars in its Shape of apparel sourcing in 2025 briefing. Below is my contribution to the report. Welcome any comments and suggestions!

What’s next for apparel sourcing

Although the world economy is predicted to grow at a similar pace in 2025 from 2024, the slowing US and Chinese economies could impose new challenges to apparel sourcing, from weakened demand to intensified price competition.

Regarding the macroeconomic environment in 2025, which “sets the tone” for apparel sourcing, the International Monetary Fund (IMF) and the World Bank estimated that the world economy would grow by approximately 2.7-3.2 percent in 2025, with almost no change from the previous year. Similarly, the World Trade Organization (WTO) projected that world merchandise trade would increase by 3.3 percent in 2025, slightly higher than 2.6 percent in 2024.

Despite this incremental improvement, the world’s two largest economies–the US (with 2.2 percent GDP growth in 2025, down from 2.8 in 2024 and 2.9 in 2023) and China (with 4.5 percent GDP growth in 2025, down from 4.8 in 2024 and 5.2 in 2023) are expected to experience slower economic growth in the new year ahead. This slowdown means that apparel producers around the world, particularly those developing countries making large-volume basic items, will likely continue to struggle with a shortage of souring orders in 2025 due to overall weak import demand.

Even more concerning, as China grapples with declining domestic sales, the world clothing market could see an additional influx of low-cost Chinese products, especially through new e-commerce channels. Notably, less than half of China’s clothing production is exported, indicating its significant untapped export capacity. Furthermore, while China’s wage levels are higher than those in many other Asian apparel-producing countries, the unit price of U.S. apparel imports from China measured in dollar per square meter equivalent ($/SME) dropped by more than 21% between 2018 and 2024 (up to October). In contrast, U.S. apparel import prices from the rest of the world increased by 7.8% over the same period. Related to this, what is often overlooked is that even Shein, the “ultra-fast fashion” retailer known for its exceptionally competitive pricing, deliberately opted out of the vast Chinese market due to concerns about the intense price competition there. In other words, disregarding the new Trump tariff, 2025 could see an escalation of trade tensions targeting Chinese products in the US market and beyond.

Meanwhile, due to concerns about rising geopolitical tensions worldwide and trade policy uncertainty during Trump’s second term, fashion companies will likely continue to leverage sourcing diversification to mitigate risks. However, the “reducing China exposure” and sourcing diversification movement has yet to substantially benefit near-shoring or emerging sourcing destinations such as the Western Hemisphere and Sub-Saharan Africa (SSA). This result was mainly because fashion companies utilized China to source a wide range of various products, whereas Western Hemisphere and SSA suppliers can only produce a few basic categories.

For example, my latest studies show that in the first nine months of 2024, even excluding major platforms like Shein, Amazon, and Temu, US fashion companies sourced more than 60K Stock Keeping Units (SKUs) of clothing items from China. In comparison, India and Vietnam each supplied approximately 15K SKUs, Cambodia and Bangladesh each contributed 3,000 SKUs, Mexico provided only 2K SKUs, and CAFTA-DR and AGOA member countries supplied around 200 SKUs each. Therefore, even if fashion companies report sourcing from more countries, they are likely to stay sourcing from more Asian countries with closer export capacity and structure to China. Meanwhile, the total value or volume of trade may not fully capture the whole picture of sourcing diversification. This trend may persist in 2025, even with new tariff escalations.

Apparel industry challenges and opportunities

Today’s fashion business is highly global and relies heavily on the frequent movement of goods and services across borders. Thus, the uncertain and protectionist nature of U.S. trade policy during Trump’s second term could present significant challenges to the fashion industry in 2025. Of particular concern is that Trump’s new tariff actions would raise fashion companies’ sourcing costs, create additional inflationary pressure, reduce US consumers’ purchasing power on clothing, and trigger retaliatory trade measures from U.S. trading partners, ultimately hurting the U.S. economy. Notably, when the 7.5% Section 301 tariff was imposed on selected Chinese clothing products in 2018, the U.S. Consumer Price Index (CPI) growth was relatively low at 1.9%. However, imposing a 20% global tariff, a 60% tariff on Chinese products, and the existing 15%-30% regular tariff on clothing when the CPI is historically high is like “adding fuel to the fire.”

Besides tariffs, in 2025, if not sooner, U.S. fashion companies and many e-commerce suppliers worldwide will closely watch how Congress and the new Trump administration reform the de minimis rule, which currently exempts small-value shipments under $800 from tariffs and most customs procedures.  With Trump’s new tariffs looming, some argue that closing the de minimis “loophole” has become even more urgent, as it creates more financial incentives to use the rule to bypass the tariff increase. Meanwhile, proposals under consideration suggest removing textile and apparel products entirely from de minimis, a move that could be an “earthquake” for those fashion companies utilizing the rule heavily.

Trump’s approach and philosophy toward conventional trade agreements and trade preference programs in 2025 also deserve attention. During his first term, Trump launched a few bilateral trade negotiations, from the one with the United Kingdom and Japan to Kenya. Back then, Trump saw a bilateral agreement would give the U.S. more leverage for a better “deal.” Specifically related to apparel sourcing and trade, two flagship U.S. trade preference programs–the African Growth and Opportunity Act (AGOA) and the Haiti HOPE/HELP Act, will expire in September 2025. It remains uncertain whether the new Trump administration will support the early renewal of these two trade preference programs with minimal changes or prefer to renegotiate them and add new bilateral elements.

Additionally, even though the new Trump administration may not prioritize addressing climate change, it is an irreversible trend for fashion companies to allocate more resources to comply with upcoming or newly implemented sustainability and environmental-related legislation, whether from the EU or the US state level. Unlike in the past, when being more sustainable only meant adding operational costs or paying a “one-time fee,” today’s new generation of sustainability-focused regulations—such as Extended Producer Responsibility (EPR)—requires companies to shift their mindset and demonstrate continuous improvement. Interestingly, my recent study tracking apparel products’ sustainability claims shows that vague terms like “sustainable” and “eco-friendly” are gradually being replaced by more neutral, fact-based keywords such as “regenerative,” “textile waste,” and “low impact.”

Meanwhile, offering “sustainable” apparel products and those using “preferred sustainable fibers” could provide fashion companies new opportunities to diversify their sourcing base and expand their vendor networks. For example, studies show that in the U.S. market, China and many other Asian countries are not necessarily the top suppliers of clothing made with recycled materials. Instead, Europe and countries in the Western Hemisphere or even Africa present unique sourcing advantages and capacities due to the unique nature of such products. Therefore, in 2025, we can expect an ever-closer collaboration between design, product development, merchandising, sourcing, and legal teams within fashion companies, working together to meet the growing demand for sustainable apparel and ensure compliance with evolving regulations.

by Sheng Lu

New Study: Exploring India as an Apparel Sourcing Base for U.S. Fashion Companies

The full article is published in Just-Style and below is the summary:

India’s Textiles and Apparel Production

Data from the United Nations Industrial Development Organization (UNIDO) shows that India produced around $76.5 billion in textiles and $26.64 billion in wearing apparel in 2022. Although still smaller than China’s, this production scale has already surpassed that of most other Asian countries, including Vietnam. Behind these numbers were India’s over 4,000 ginning factories, 3,500 textile mills, and around 45 million workers directly employed by the textile and apparel sector.

India is one of the world’s largest textile fiber producers, including regular cotton, organic cotton, silk, polyester, and viscose. India also has more advanced local textile manufacturing capabilities than most other developing apparel-exporting Asian countries, allowing it to benefit from a vertically integrated local textile and apparel supply chain. A recent U.S. International Trade Commission (USITC) study noted that more than 90 percent of India’s textile raw materials needed for its apparel production can be sourced domestically. In comparison, as the World Trade Organization (WTO) global value chain analysis estimated, more than 64 percent of Vietnam’s apparel exports in 2022 contained foreign-made content (i.e., imported yarns and fabrics), 57 percent for Cambodia, 49 percent for Indonesia, and 33 percent for Bangladesh.

India’s Apparel Export

India remained a much smaller apparel exporter than China, Vietnam, and Bangladesh. According to the World Trade Organization (WTO), India exported about $15 billion in apparel in 2023, ranked the world’s sixth largestor 2.8 percent of the global total.  Similarly, in 2023, India accounted for 5.5 percent of U.S. apparel imports and 3.5 percent of the EU, showing its position as a significant supplier but not among the largest. However, unlike most other developing Asian countries, India exports less than half of its apparel output due to its massive domestic market with a population of 1.43 billion. This implies that India’s substantial untapped apparel export potential should not be ignored.

Why Sourcing from India?

Firstly, aligned with trade statistics, many U.S. fashion companies already source from India, although in a relatively small volume.  For example, the USFIA benchmarking survey respondents consistently ranked India as the 3rd or 4th most utilized apparel sourcing base from 2021 to 2024, after China and Vietnam. However, U.S. fashion companies typically place less than 10 percent of their total sourcing value or volume in India. The recent USITC study also raised concerns that India’s apparel factories were primarily small and medium-sized, which could limit their ability to fulfill large-volume sourcing orders.

Secondly, “Made in India” clothing is not necessarily cheap but could be perceived as “worth the value.” Notably, from January to October 2024, clothing labeled “Made in India” sold in the U.S. retail market was, on average, priced much higher than imports from Bangladesh and Vietnam, particularly in the mass market segment. Meanwhile, in the premium market segment, clothing “Made in India” was, on average, priced relatively lower than “Made in China,” such as dresses, tops, and bottoms. These results suggest that U.S. fashion companies do not typically consider India a preferred sourcing base for basic and price-sensitive items. Instead, India may be seen as a more cost-effective alternative to China for high-quality, value-added clothing.

Thirdly, India has been strengthening its competitiveness in export flexibility and agility, enabling its vendors to quickly adjust the delivery, volume, and product of the sourcing order upon customers’ requests. In the latest 2024 USFIA survey, respondents rated India’s sourcing flexibility and agility second only to China, surpassing Bangladesh, Cambodia, and Central American countries. Likewise, India was regarded as one of the few Asian countries that could fulfill apparel sourcing orders with relatively low “minimum order quantity (MOQ)” requirements.

One major factor contributing to India’s perceived advantages in sourcing flexibility and agility is its ability to produce a wide range of apparel products. For example, the Herfindahl-Hirschman Index (HHI) calculated using trade data at the 6-digit HS code level indicates that U.S. apparel imports from India cover more diverse product categories than most Asian countries.

Moreover, due to India’s position as one of the world’s leading cotton producers, in the first ten months of 2024, nearly 60 percent of U.S. apparel imports from India contained cotton fibers, including 13 percent using organic cotton. This percentage was much higher than imports from other Asian suppliers such as China and Vietnam. In comparison, over the same period, U.S. apparel imports from India appear less likely to contain man-made fibers like polyester, nylon, spandex, and recycled polyester. This fiber composition explains why India has yet to become a leading supplier of certain apparel product categories, like outerwear, which more commonly uses man-made fiber than cotton.

Additionally, in the first ten months of 2024, over 45 percent of India’s apparel newly introduced to the U.S. market targeted the luxury and premium segment, closely matching China’s nearly 50 percent and exceeding other Asian suppliers such as Vietnam (20 percent), Bangladesh (13 percent), Cambodia (5 percent), and Indonesia (18 percent). This result explains why U.S. fashion companies increasingly consider India a strategic alternative to sourcing from China, given the similarities in their product offerings.

Reflections

India’s large country size and population, the presence of an already highly integrated and sophisticated textile and apparel supply chain, and its ability to make a great variety of high-quality products suitable for various market segments position it well in the export competition. U.S. fashion companies’ eagerness to reduce sourcing from China due to rising geopolitical concerns and the limited sourcing capacity elsewhere created historical opportunities for India to expand its apparel exports to the U.S. market further.

Nevertheless, it remains a question mark whether India is fully committed to expanding labor-intensive apparel production and exports, given the country’s economy is moving toward more capital and technology-intensive sectors. Notably, in value, apparel only accounted for about 5.6 percent of India’s total merchandise exports in 2023, similar to China’s 5.3 percent but much lower than other lesser-developed Asian countries, including Vietnam (10 percent), Bangladesh (88 percent), and Cambodia (44 percent).

Moreover, while India is not a primary focus for compliance issues like forced labor, sourcing from the country still carries general social and environmental compliance risks similar to those in most developing countries (note: see the 2024 USITC report). It remains to be seen whether India’s textile and apparel mills are technically and financially prepared to meet more stringent social and environmental standards being adopted in the U.S. and can effectively compete in the growing market for “sustainable apparel.”

by Gabriella Giolli (Honors Marketing major & Fashion management minor, University of Delaware) and Sheng Lu

New Study: Exploring the US as a Sourcing Base for Clothing Using Recycled Cotton

The full article is published in Just-Style and below is the summary:

Market Size

Reflecting fashion companies’ interest in carrying more sustainable apparel products to meet consumers’ demand, there has been a notable increase in clothing using recycled cotton in the U.S. retail market since 2022. For example, based on information collected from US apparel retailers’ websites, only about 100 Stock Keeping Units (SKUs) of “Made in the USA” clothing explicitly indicated that they contained recycled cotton in 2022 and 2023, respectively. However, in the first nine months of 2024, this number had already doubled to around 200.

Despite the impressive growth, clothing containing recycled cotton remains a “niche” in the U.S. retail market. As of 2024, the total SKUs of “Made in the USA” clothing containing recycled cotton accounted for only about 0.1% of those made with regular virgin cotton.

Meanwhile, measured by SKU count, 70% of “Made in the USA” clothing containing recycled cotton was sold in the mass and value segments in the U.S. retail market from 2022 to 2024.  In comparison, over the same period, “Made in the USA” clothing made with regular cotton catered to a more diverse consumer base, with a relatively balanced distribution across the mass and value segment (57%) and the luxury and premium segment (43%).

Product Features

There appears to be a notable distinction between the product categories of “Made in the USA” clothing using recycled cotton and those made with regular cotton. Specifically, from 2022 to 2024, by SKU count, “Made in the USA” clothing containing recycled cotton mainly focused on basics such as T-shirts (35.6%), jeans (20.1%), other bottoms (20.7%) and other tops (18.4%). Particularly, jeans appear more likely to contain recycled cotton than any other apparel category.

Using recycled cotton also appears to affect clothing’s design patterns. For example, from 2022 to 2024, nearly 85% of “Made in the USA” clothing containing recycled cotton chose plain design patterns compared to only 65% of those exclusively using regular cotton. These results echo findings from previous studies, suggesting that the shorter fiber length and lower quality of recycled cotton may limit the use of more intricate and complex design details.

Fiber Content

Reflecting the significant limitations of the quality and properties of the fiber, clothing labeled as using “100% recycled cotton” was rarely available in the U.S. retail market from 2022 to 2024, regardless of where the item was made. In most cases, recycled cotton accounted for no more than 30% of the total fiber content in a garment, with typical labels read like “49% cotton, 21% recycled cotton, 17% recycled polyester” (jeans), “Made from 70% cotton and 30% recycled cotton” (T-shirt), and “Made from 70% cotton, 29% recycled cotton, and 1% elastane” (skirt).

Results show that over 95% of “Made in the USA” clothing containing recycled cotton was blended with regular virgin cotton, and 92% of imported clothing did the same. According to textile scientists, this blend helps overcome the physical limitations of recycled cotton and enhances the fabric’s durability and softness. Approximately 14% of “Made in the USA clothing” containing recycled cotton was blended with polyester. This blend was commonly used for jeans and T-shirts to improve durability and flexibility and may also reduce production costs. However, compared with “Made in the USA” clothing made from regular cotton, it was uncommon to see recycled cotton blended with specific fiber types such as nylon, spandex, rayon, and linen. This result again revealed the physical limitations of recycled cotton and explained the narrow range of apparel products currently suited for its use.

Sustainability Claims

In practice, the sustainability claims of “Made in the USA” clothing containing recycled cotton in the U.S. retail market appear to be a “mixed bag.” On the one hand, as anticipated, “Made in the USA” clothing containing recycled cotton seems to be more likely to highlight its sustainability attributes than those using regular cotton only. From 2022 to 2024, by SKU count, more than 23.1% of “Made in the USA” items containing recycled cotton mentioned the word “sustainable” in the product description or label, and another 16.2% mentioned “eco-friendly.” In comparison, less than 2% of “Made in the USA” clothing made from regular cotton included these two terms.  Similarly, a higher percentage of “Made in the USA” clothing using recycled cotton also featured other sustainability-related terms such as “impacts,” “waste,” and “certified,” compared to those made from regular cotton.

On the other hand, however, the sustainability claims of “Made in the USA” clothing containing recycled cotton are not without concerns. For example, in many cases, the product descriptions or labels provide no detailed and verifiable information about the actual “sustainability benefits” of producing and consuming clothing made from recycled cotton aside from vaguely saying the product was “sustainable,” “eco-friendly,” or “certified.”

To complicate the issue further, as clothing made from regular cotton increasingly emphasizes its sustainability benefits as a natural fiber, it somehow diminishes the exclusivity of recycled cotton as a sustainable option. For example, there is no clear evidence indicating that consumers generally perceive clothing using “recycled cotton” as more or less sustainable than those using “organic cotton” or cotton certified by reputable programs such as the “Better Cotton Initiative, BCI” and the “U.S. Cotton Trust Protocol.” In other words, “recycled cotton” faces intense competition as the preferred sustainable fiber among many choices available to fashion companies, including regular cotton. 

Pricing Practices

Results show that “Made in the USA” clothing containing recycled cotton is not always “cheap” for U.S. consumers. For instance, for those targeting the mass market segment, between 2022 and 2024, adding recycled cotton increased the selling price of “Made in the USA” clothing by more than 10% compared to items made with virgin cotton, with jeans being the only exception (i.e., 12% lower).

Price data also show that “Made in the USA” recycled cotton items generally have higher price tags than comparable non-U.S.-made items across both mass and premium markets, particularly in popular categories like T-shirts and bottoms. This trend suggests that higher U.S. domestic production costs, particularly the higher wage level than Asian countries, could contribute to these elevated prices.

Reflections

As the findings highlighted, while visibility is increasing, promoting recycled cotton in clothing still encounters significant challenges. For instance, technical advancements in the quality of recycled cotton fiber are critical to enhancing its competitiveness among other “preferred sustainable fibers,” raising its perceived market value and enabling its use across a broader range of clothing categories beyond T-shirts and jeans.

Notably, due to slow progress in improving the physical properties of recycled cotton, some have seemingly “given up” on using it for clothing and suggest focusing more on repurposing recycled cotton for other categories, such as non-wovens, carpets, packaging, and home textiles. However, as sustainability legislation, such as the Extended Producer Responsibility (EPR) law, increasingly mandates fashion companies to recycle textile waste, not promoting recycled cotton could lead to greater reliance on recycled polyester or other man-made fibers in clothing, which may not serve the long-term business interests of the cotton industry.

by Katherine Yasik (Fashion Design and Product Innovation major & Sustainable apparel minor, Fashion and Apparel Studies, University of Delaware) and Sheng Lu

New Study: How Has the Uyghur Forced Labor Prevention Act (UFLPA) Affected U.S. Apparel Import?

Implemented in June 2022, the Uyghur Forced Labor Prevention Act (UFLPA) prohibits U.S. companies from importing apparel wholly or in part produced in China’s Xinjiang region. UFLPA could significantly alter U.S. apparel import patterns as fashion companies have begun or anticipate adjusting their sourcing base to comply with the law and mitigate the forced labor risks in the supply chain.

This study quantitatively evaluated the impacts of the UFLPA on U.S. apparel imports nearly two years after the law’s implementation. Unlike existing studies primarily focusing on UFLPA’s political or legal aspects, this study’s findings would enhance our understanding of the economic and trade implications of the new law.

A panel regression model was adopted to evaluate the quantitative impact of UFLPA on U.S. apparel imports based on data collected from OTEXA (2024) and USITC (2024), the most authentic government data source. Four countries in three categories were included in the study: 1) China; 2) Vietnam and Bangladesh representing top Asian apparel exporting countries other than China; 3) member countries of the Central America Free Trade Agreement (CAFTA-DR) representing near-shoring sourcing destinations. The annual trade activities of these four countries from 2010 to 2023 (the latest available) were used for the analysis.

The panel regression model suggests several interesting findings*:

Firstly, the results showed that holding other factors constant, U.S. cotton apparel imports from China decreased significantly by approximately 350 million square meter equivalent (SME) annually following UFLPA’s implementation. In other words, the result confirmed that UFLPA had negatively affected U.S. cotton apparel imports from China. This result is far from surprising as Xinjiang accounted for nearly 90% of China’s cotton production, causing significant forced labor risks associated with importing cotton apparel from China.

Secondly, holding other factors constant, U.S. cotton apparel imports from Vietnam and Bangladesh and CAFTA-DR also respectively decreased by approximately 81 million SME, 51 million SME, and 20 million SME annually after UFLPA’s implementation in 2022. The results revealed U.S. fashion companies’ concerns about UFLPA compliance risks associated with sourcing from countries other than China, particularly Asia, due to their heavy reliance on cotton yarns and fabrics from China through a highly integrated regional supply chain.

Thirdly, the results revealed a more significant positive relationship between U.S. cotton exports to China, Vietnam, Bangladesh, and CAFTA-DR countries and U.S. cotton apparel imports from these countries after UFLPA’s implementation. Related, trade data also showed a declining ratio of U.S. cotton apparel imports from China, Vietnam, Bangladesh, and CAFTA-DR countries relative to these countries’ cotton imports from the U.S. This pattern implies a closer alignment in the trade flow of raw cotton from the U.S. to these countries and the return of finished cotton apparel to the U.S. It could be the case that leading apparel exporting countries increasingly used US cotton after UFLPA to mitigate the forced labor risks.

Additionally, there was a negative relationship between U.S. cotton apparel imports from China, Vietnam, Bangladesh, and CAFTA-DR members and U.S. MMF apparel imports from these countries. In other words, cotton apparel and MMF apparel appear to compete within the total U.S. apparel import market. However, UFLPA’s implementation has not significantly impacted the relationship. Nonetheless, MMF apparel has accounted for a growing share of China’s total apparel exports to the United States after UFLPA’s implementation (down from 46% in 2010 to only 19% in 2023).

The study’s findings revealed a broad trade impact of UFLPA’s implementation that goes far beyond China. Notably, cotton apparel exporters from other Asian countries and those in the Western Hemisphere also appeared to be negatively affected by the new law. Also, unlike theoretical prediction, no clear evidence shows that UFLPA has significantly expanded the near-shoring of U.S. cotton apparel imports from the Western Hemisphere, such as CAFTA-DR members.

Meanwhile, the results call for further investigation of the net impact of UFLPA on U.S. cotton exports. While UFLPA may help U.S. cotton gain more shares in the global marketplace, the reduced U.S. import demand for cotton apparel due to forced labor risk concerns may also unexpectedly “shrink the pie size.”

*:The fixed effects (FE) model was selected for the study based on the likelihood ratio test results (p<.01). The result of the F-test suggests the FE model is statistically significant at the 99% confidence level (p<.01). The value of R2 exceeds 0.90, indicating an overall high goodness-of-fit of the panel regression. All the independent variables were statistically significant at the 99% confidence level (p<.01).

By Sheng Lu and Emilie Delaye

Note: The study will be presented at the 2024 International Textile and Apparel Association (ITAA) annual conference in November 2024.

[This blog post is not open for comment]

Costume Buying and Sourcing: FASH455 Exclusive Interview with Kara Hamalainen, Associate Costume Buyer at Disney Live Entertainment

About Kara Hamalainen

My name is Kara Hamalainen, and I am a May 2023 graduate of the University of Delaware. I earned my Bachelor of Science double majoring in Fashion Design and Product Innovation & Fashion Merchandising and Management. While studying at UD, I was very involved with the Impact Dance Company and Synergy Fashion Group. I have a strong passion for the costume industry because I grew up as a dancer, and it is the perfect way to link my two most prominent interests of fashion and the entertainment world together.

After graduating from UD, I was accepted into the Disney Professional Internship program and began my role as a Disney Live Entertainment Costuming Buyer Intern. I had the most incredible experience as a Professional Intern for the Walt Disney Company, and luckily, my time with my dream company did not end after my internship. I was offered a full-time Associate Costume Buyer role, and I get to continue making magic for thousands of people every single day! I currently live in Orlando, Florida and have been in my full-time ACB role for about six months.

Sheng: As a costume buyer for Disney, what are your primary job responsibilities? What does a typical day or week look like for you? Which part of the job do you find most exciting? Were there any aspects of the position that surprised you after you started?

Kara: The primary responsibility of a costume buyer under Disney Live Entertainment is to have the right costumes at the right place, in the right quantity, and at the right time. Buyers are responsible for placing orders for costume pieces, garments, and accessories and ensuring that delivery dates for products ordered are closely monitored. By achieving this, we can create and enrich the experiences of our guests and cast members worldwide. Our work can be seen at the Disney theme parks, resort hotels, cruise ships, and numerous other locations around the globe, which is truly a special and unique opportunity.

I am an Associate Costume Buyer under our Character Programs & Development (CP&D) replenishment team. In this role, I mainly replenish existing products but may assist with new developments as needed. My main responsibility is facilitating the purchase of various hard and soft goods for our character costumes. I assist a few buyers on my team with their orders while managing my own orders and vendor relationships. I also facilitate conversations with domestic vendors across the U.S. to get high-quality products on time and within budget. Additionally, I issue fabric and notions requests from our warehouse to get materials stored in-house and sent to our outside vendors for production.

The most exciting part of my job is witnessing how my work behind the scenes impacts people every single day. Whenever I go to the Walt Disney World theme parks, I watch guests interact with their favorite Disney characters through meet & greets and parades. It is heartwarming to know that I get to contribute to something so special to somebody and allow them to have that memory for the rest of their life.

An aspect of my role that surprised me the most was how complex and detail-oriented every single element of a character’s costume is. It may be as small as an earring or a buckle on a belt, but each costume component is treated equally. Attention to detail is an extremely crucial element to Disney Live Entertainment Costuming to ensure the power of storytelling comes across to all guests.

Sheng: What does the buying and sourcing process look like for costumes? What factors do you typically consider in your buying and sourcing decisions? What are the unique issues or challenges involved in costume buying and sourcing?

Kara: The buying process for character costumes begins with our CP&D inventory planning team, which monitors the inventory of our costumes in terms of sizing, assortment, and quantity. The inventory planning team determines optimal inventory levels and all costume issue locations in the warehouse. They are also the team that will receive specific requests from costuming leaders and sites regarding inventory status and demand for a certain character costume. Once the inventory planning team has decided what character costume piece will need to be ordered and the ideal quantity, they will notify the buyer to place an order.

Once the buyer has been notified of the new purchase request, they will email their vendors to notify them of the new order. It is essential to inform the vendor of the item, quantity, and due date to confirm that the order can fit into their current production schedule. The buyer will also confirm pricing with the vendor. As soon as the vendor confirms that the new order will fit into their production schedule, the buyer writes the official purchase order. For all soft goods, this is the point in time where the buyer will notify our patternmaking team to send the tech pack and samples to the vendor for production. If necessary, the buyer will also ensure that fabric and notions requests are made for the order. Once the buyer takes these steps, the outside vendor will successfully produce the order.

When production is completed, and the order is delivered to our warehouse, a detailed quality check process will be performed. Every item goes through inspection, is counted for quantity accuracy, and is measured to ensure that sizing is to spec based on the tech pack. If there are any discrepancies, there are multiple ways in which the issue can be resolved so the items can ultimately pass the quality inspection. Most importantly, the buyer will be notified and communicate the issue to the vendor so it can be prevented for future orders. If there are no noted issues with the order, then the order will be received in the system and marked for completion.

A challenge frequently arises involves orders with a “hard due date,” meaning the costume piece is needed for a specific project, show, or cruise ship. These hard due date orders do not have flexibility with their due dates as a regular replenishment order would, so it is crucial to make the vendor aware of shifting order priority if necessary. Sometimes, these hard-due-date order requests come in with very little notice, so the buyer will confirm with the vendor that they can turn in the items quickly and successfully meet the due date. If a hard due date order becomes impossible to meet, the buyer will communicate with the inventory planning team, which will work on finding a viable solution.

Sheng: As a costume buyer, how do you collaborate with other departments and teams at Disney, such as designers, product development, and sourcing? How about external stakeholders, such as your vendors?

Kara: For the CP&D Procurement Buying team, one of our main focuses is our communication and relationships with outside vendors. It is extremely vital that we build and maintain strong relationships with our outside vendors so our business can continue to run successfully. The buyers are in constant contact with their assigned vendors, communicating daily via email and phone about both current and new costume orders. It is also important that we get our work onto their production schedule in a timely manner to avoid scheduling conflicts with other customers they may have.

Regarding other teams at Disney, my buying team often collaborates with the project development buying team. This team is responsible for buying and sourcing materials for new character costumes that the designers are currently developing. Once the development process has been completed, we hold transition meetings where the development team goes over everything the replenishment buying team will need to know about the new character costume for future orders. This includes elements such as raw materials, fiber content, vendor information, and price per costume piece.

Sheng: Do you see any innovations changing the future of costume buying or production, particularly due to factors like technology, AI, and sustainability?

Kara: The Walt Disney Company commits to environmental sustainability, implementing several goals to achieve by 2030 related to emissions, water, waste, materials, and sustainable design. Specifically for Disney Live Entertainment Costuming, we focus on sustainable materials, manufacturing, and zero waste management. Fabrics and raw materials will be resourced to contain at least 25% certified sustainable content or lower-impact alternatives. Plastics will also need to contain at least 30% recycled content or a lower-impact alternative material. Manufacturers of raw materials and garments must provide one or more approved sustainable certifications and confirm participation in the Higg Index.

As a buyer, it will be our responsibility to work with our outside vendors and ensure they are closely following our company’s sustainability efforts. As some vendors source their own materials rather than use Disney-supplied materials, they must shift toward using recycled, sustainably sourced, or lower-impact alternative textiles and raw materials. Additionally, any vendors specializing in plastics and other hard goods will have to figure out ways to make their materials more sustainable without affecting the quality of the costume piece. Our current outside vendors must also maintain a sustainable manufacturing certification and provide proof of their sustainability practices. Suppose this is not possible for some of our current vendors. In that case, I imagine we would have to identify new vendors who can maintain production on a sustainable level that is ideal for our business model.

Sheng: What advice would you give to students interested in pursuing a career in costume buying and sourcing? What skill sets are most valued in this role? Are there any specific experiences or opportunities at UD and in the FASH program that you would highly recommend for our students exploring their career paths?

Kara: I would highly recommend taking advantage of internship opportunities during your time at UD. Internships are a great way to gain hands-on experience in the day-to-day responsibilities of a particular role while allowing you to strengthen your understanding of the textile and apparel industry from a real-world perspective. It is also an extremely effective way to network and make valuable connections in the industry. Don’t be afraid to start conversations with your FASH professors about your goals and interests, as they are always willing to help and will likely have strong connections to the industry as well.

Additionally, having an open mind is extremely important going into the industry. Your first job out of college may not be your dream role, but know that you are gaining valuable industry skills that can be applied to a number of different positions. For example, I know that I eventually want to work my way into a more creative and design-driven role. While my current position as a costume buyer may not be focused on design and creativity, the communication and organization skills I am gaining can still translate to various positions in the industry.

Lastly, follow your dreams! It might sound cliché, but you never know what will happen if you put yourself out there and give something a shot. I faced multiple rejections from Disney before getting accepted into the internship program. If I had not decided to persevere and keep trying, I would not be where I am today. I also owe so much of my successes to the UD FASH program, as I am so grateful for the opportunities it provided. Good luck to all of you!

–The End–

Event Recording: Regulating and Reforming De Minimis (October 2024)

The event was hosted by the Washington International Trade Association on October 9, 2024

Panelists

  • Ralph Carter, Staff Vice President, Regulatory Affairs, FedEx
  • Kim Glas, President & CEO, National Council of Textile Organizations; Commissioner, U.S.-China Economic and Security Review Commission
  • Melissa Irmen, Director of Advocacy, NAFTZ-National Association of Foreign-Trade Zones
  • John Pickel, Senior Director, International Supply Chain Policy, National Foreign Trade Council
  • Felicia Pullam, Executive Director, Office of Trade Relations, U.S. Customs and Border Protection
  • Ana Swanson, Trade and International Economics Reporter, The New York Times (Moderator)

Event summary: Competing views about de minims and its reform

Arguments supporting De Minimis: Proponents like Ralph from FedEx argue that de minimis reduces trade friction, drives international supply chain efficiency, and allows U.S. companies to offer competitive pricing through free returns and streamlined customs processes. Meanwhile, they argue that the de minimis supports low-income U.S. consumers and enables small U.S. businesses to remain competitive.

Criticism of De Minimis: Critics, including Kim Glas from the National Council of Textile Organizations (NCTO), argue that it undercuts U.S. manufacturers, especially in industries like textiles, by allowing cheap imports from countries like China, often bypassing tariffs and safety regulations. They also say that de minimis was unfair to U.S. retailers that pay millions of dollars of tariff duties. Additionally, there are significant concerns about the safety risks posed by counterfeit goods and dangerous products (e.g., fentanyl) entering under de minimis exemptions.

Challenges of dealing with de Minimis: Felicia from the U.S. Customs and Border Protection (CBP) emphasizes the strain on the agency’s resources due to the sheer volume of de minimis shipments—it surged from about 2.8 million shipments per day in fiscal year 2023 to close to 4 million shipments per day in fiscal year 2024. She highlighted challenges such as the often unreliable information the de minimis imports submitted and the outdated authorities that hinder CBP’s enforcement.

Equal treatment for U.S. Foreign Trade Zones: U.S. Foreign Trade Zones (FTZs) are designated areas within the United States that are considered outside U.S. customs territory for import duties. They allow businesses to import, store, assemble, manufacture, or process goods with deferred or reduced customs duties, which are only paid when goods leave the FTZ and enter U.S. commerce. Currently, U.S. FTZs do not benefit from the de minimis exemption, meaning goods imported directly into the U.S. from overseas warehouses can qualify for de minimis, but goods entering through U.S. FTZs do not.

Melissa Irmen from NAFTZ-National Association of Foreign-Trade Zones advocates for U.S. foreign trade zones to be given the same de minimis privileges as foreign warehouses, arguing that this would ensure better oversight and security while maintaining trade efficiency. Critics, however, say that expanding de minimis in this way would exacerbate the problem rather than fix it.

Reforming the De minimis: There is a push for comprehensive reform of the De minimis system, with proposals ranging from raising duties on certain products to eliminating the exemption altogether for specific categories of goods (e.g., textiles, products subject to Section 301 tariffs).

Particularly, in a face sheet released in September 2024, the Biden Administration announced it would address “the significant increased abuse of the de minimis exemption, in particular China-founded e-commerce platforms.” The announcement said the Biden Administration would issue a Notice of Proposed Rulemaking that would exclude from the de minimis exemption all shipments containing products covered by tariffs imposed under Sections 201 or 301 of the Trade Act of 1974, or Section 232 of the Trade Expansion Act of 1962. The announcement also called for Congress to pass new legislation to reform the de minimis rule comprehensively. 

Related readings: