Throughout her career, Tricia believes in ‘progress over perfection’. As an advocate for innovation and circularity in the textile and apparel industry, she recently joined Renewcell to accelerate the commercial development of CIRCULOSE®, making fashion circular. With a vast global network, as well as experience in brand building, storytelling, and business development, she is an invaluable partner to close the loop and optimize the benefits of CIRCULOSE®.
For more than twenty years, Tricia held various commercial management positions at Lenzing Fibers to establish the TENCEL™ brand, build mill partners, and set retailer specifications. Her roles comprised marketing, Americas business development, and global denim segment expansion, including the creation of the Carved in Blue platform and numerous collaborative collections with mills and brands.
Tricia holds a bachelor’s degree in Fashion Merchandising from The Fashion Institute of Technology, as well as certificates in Digital Marketing and Strategy from Cornell University and MIT.
Tricia serves on the board of Accelerating Circularity, as well as the Transformers Foundation and the Fashion Impact Fund. She was Vice Chair at Textile Exchange from 2014-2018. In 2020 she was nominated as B2B Content Marketer of the Year by Content Marketing Institute, as well as top 100 Denim Legends by WeAr Magazine. In 2019 Tricia was awarded the RIVET 50 for influential denim industry leaders. She has been a speaker at various industry events, including the Conscious Fashion and Lifestyle Network at the United Nations, Transformers, Kingpins Show, Southern Textile Association, Texworld, Premiere Vision, Wear Conference, and more.
Tracia lives in New York City and can be seen dashing on the Peloton leaderboard. The best way to connect with Tricia is through LinkedIn.
The interview was moderated by Emilie Delaye, UD’s entrepreneurship major and fashion management minor. Emilie has been involved in several research projects on the textile and apparel trade, sourcing, and sustainability issues, including authoring a paper on US fashion companies’ evolving sourcing strateiges published in Just-Style. Emilie is also the recipient of the 2024 Warner and Taylor Awards for Outstanding Seniors, the highest recognition for UD’s graduating seniors.
The latest US apparel import data raises several puzzles that deserve to be investigated further.
Question 1: Why did imports suddenly surge, and is this surge sustainable?
Unexpectedly, US apparel imports experienced a significant surge in February 2024. This surge was marked by a 12.9% increase in quantity and a 2.9% increase in value compared to the previous year. Seasonally adjusted US apparel imports in February 2024 were also nearly 10% higher than in January 2024. The import surge was particularly surprising given that the value of US clothing sales in February 2024 was only 1.3% higher than a year ago and even 0.5% lower than in January 2024 (seasonally adjusted).
Therefore, it will be important to watch whether the US apparel trade has indeed reached a turning point and will continue growing in the coming months and throughout the year.
Question 2: Could the volume of US apparel imports in 2023 have been underreported?
With over 98% of clothing sold in the US retail market being imported today, there exists a strong correlation between US apparel retail sales (NAICS code 4481) and the volume of apparel imports. Between 2015 and 2022, the US clothing sales to clothing import ratio remained consistently around 3.0-3.2 (seasonally adjusted). In other words, the value of retail sales was approximately three times the value of apparel imports. However, in 2023, this ratio increased to 4.0-4.5.
One suspicion is that as more apparel imports came into the US through the de minimis, the official US apparel import data in 2023 was somewhat underreported. Notably, according to Euromonitor, about 40% of US apparel retail sales were achieved through e-commerce in 2023, a substantial increase from 9.4% in 2010. Likewise, with US customs tightening controls on “small package shipments” and enhancing UFLPA enforcement, more imports likely began entering through the standard procedure in recent months, which explains why the US apparel sales to import rato fell back to 3.8 in February 2024.
On the other hand, some say the lowered US apparel import volume in 2023 was due to retailers’ efforts to control inventory levels. Data shows that US clothing stores’ stock-to-sales ratio in the last quarter of 2023 averaged 2.34, slightly lower than 2.43 from 2015 to 2019, but was higher than 2.19 back in 2021. In other words, while there was some effort by retailers to control inventory (as seen by the ratio being lower than pre-pandemic levels), it wasn’t a significant enough change to have a large impact on import demand. Also, considering that apparel is a seasonal product, it doesn’t seem too likely that retailers would risk losing sales opportunities during the most critical selling season of the year (i.e., 4th quarter) by promoting outdated items instead of stocking new ones on the shelf.
Question 3: Why did Asian countries export more apparel to Mexico?
As a developing country, Mexico is not traditionally a leading apparel import market due to consumers’ limited purchasing power and the sufficient local apparel supply. Take China, Vietnam, Bangladesh, and Cambodia, the four top Asian apparel exporting countries (Asia4), for instance. Between 2018 and 2020, Mexico typically accounted for 0.4%-0.7% of Asia4’s total apparel exports. However, since 2022, Asia4 has almost doubled its apparel exports to Mexico (i.e., increased to 1.5%-2.0%). Moreover, during the same period, the percentage of Asia4’s apparel exports to the United States declined from 27% to below 20%, especially in the last quarter of 2023.
What’s behind the increase in Asian countries’ apparel exports to Mexico needs to be investigated further. As noted earlier, Mexico itself is a leading apparel-producing country. Also, according to Euromonitor, the clothing market in Mexico stayed relatively stable at around 7.6%-7.9% of the size of the US from 2017 to 2023 (in quantity). In other words, Mexico’s increased import demand for Asian clothing doesn’t make much sense.
Others suspect some Asian apparel exports to Mexico eventually entered the US market either by taking advantage of the de minimis rule or the US-Mexico-Canda (USMCA) trade agreement. However, the exact size of this particular trade flow calls for further investigation.
#1: On April 5, 2024, the US Department of Homeland Security (DHS) released its new enhanced strategy to combat illicit trade and level the playing field for the American textile industry and the estimated over 500,000 US textile jobs*. *note: according to the Bureau of Labor Statistics, as of December 2023, the US textile and apparel manufacturing sector employed about 272,400 workers (seasonally adjusted), including 89.3K in NACIS313 textile mills, 95.6K in NAICS314 textile product mills and 87.5K in NAICS315 apparel manufacturing. As of December 2023, NAICS 4482 apparel retail stores employed about 850,000 workers (seasonally adjusted).
According to DHS, the new enforcement plan will focus on the following areas:
Cracking down on small package shipments to prohibit illicit goods from U.S. markets by improving screening of packages claiming the Section 321 de minimis exemption for textile, Uyghur Forced Labor Prevention Act (UFLPA), and other violations, including expanded targeting, laboratory and isotopic testing, and focused enforcement operations.
Conducting joint Customs and Border Protection (CBP)-Homeland Security Investigation (HIS)HSI trade special operations to ensure cargo compliance. This includes physical inspections; country-of-origin, isotopic, and composition testing; and in-depth reviews of documentation. CBP will issue civil penalties for violations of U.S. laws and coordinate with HSI to develop and conduct criminal investigations when warranted.
Better assessing risk by expanding customs audits and increasing foreign verifications. DHS personnel will conduct comprehensive audits and textile production verification team visits to high-risk foreign facilities to ensure that textiles qualify under the U.S.-Mexico-Canada Agreement (USMCA) or the Central America-Dominican Republic Free Trade Agreement (CAFTA-DR). (note: As CBP noted, most US free trade agreements and trade preference programs have complex textiles and apparel-specific rules of origin requirements. CBP is “responsible for ensuring that the trade community complies with all statutory, regulatory, policy, and procedural requirements that pertain to importations under free trade agreements and other trade preference programs.”)
Building stakeholder awareness by engaging in an education campaign to ensure that importers and suppliers in the CAFTA-DR and USMCA region understand compliance requirements and are aware of CBP’s enforcement efforts.
Leveraging U.S. and Central American industry partnerships to improve facilitation for legitimate trade. (note: The Biden Administration aims to leverage textile and apparel trade as part of the solution to address “root causes of migration in Central America. According to the White House Fact Sheet released in March 2024, the Office of the U.S. Trade Representative and Central American Trade Agencies and textiles and apparel industry stakeholders will work together to build a directory with detailed profiles of manufacturing and sourcing companies in the region, including information on business practices and production capabilities, to facilitate transparent sourcing, and bolster the region’s supply chain.)
Expanding the Uyghur Forced Labor Prevention Act (UFLPA) Entity List to identify malign suppliers for the trade community through review of additional entities in the high-priority textile sector for inclusion in the UFLPA Entity List. (note: Once an entity is on this list, in general, it is prohibited from exporting its goods to the United States. Importers are required to ensure the supply chains of their imported products are free from entities on the Entity List).
#2: Several US textile and apparel industry stakeholders have publicly responded to DHS’s new strategy.:
“We strongly commend DHS for the release of a robust textile and apparel enforcement plan today. We also greatly appreciate Secretary Mayorkas’ personal engagement in this urgent effort and believe it’s a strong step forward to addressing pervasive customs fraud that is harming the U.S. textile industry.”
“The essential and vital domestic textile supply chain has lost 14 plants in recent months. The industry is facing severe economic harm due to a combination of factors, exacerbated by customs fraud and predatory trade practices by China and other countries, which has resulted in these devastating layoffs and plant closures. DHS immediately understood the economic harms facing the industry and deployed the development of a critical action plan.”
“The industry requests include
Ramped up textile and apparel enforcement with regard to Western Hemisphere trade partner countries, including onsite visits and other targeted verification measures to enforce rules of origin as well as to address any backdoor Uyghur Forced Labor Prevention Act (UFLPA) violations.
Increased UFLPA enforcement to prevent textile and apparel goods made with forced labor from entering our market, including in the de minimis environment.
Immediate expansion of the UFLPA Entity List, isotopic testing, and other targeting tools. Intensified scrutiny of Section 321 de minimis imports and a review of all existing Executive Branch authorities under current law to institute basic reforms to this outdated tariff waiver mechanism. “
“We appreciate the Department of Homeland Security (DHS)’s announcement today outlining enhanced enforcement activities to prevent illicit trade in textiles. Our members support 55 million (more than one in four) American jobs and invest considerable time and resources in their customs compliance programs. Many of our members are Tier 3 participants in Customs-Trade Partnership Against Terrorism (C-TPAT). They are trusted traders and meet the high standards required to receive that designation by U.S. Customs and Border Protection and DHS. Our members are on the front lines for ensuring that they have safe and secure supply chains.
“While DHS launches this enforcement plan, we urge it to partner with our associations and our associations’ members. A successful enforcement plan must include input from all stakeholders, clear communication with the trade, and coordinated activities with importers, especially if DHS finds illicit activity happening in the supply chain. The results of any illicit activities must be shared so that our members and other importers can act quickly to address the issue. As our members look to diversify their supply chains, especially back to the Western Hemisphere, we must make sure efforts are included to incentivize and not deter new investments.”
#3 Comments: Overall, the new DHS textile enforcement plan suggests several key US textile and apparel trade policy directions: 1) revisit the current de minimis rules that are used by many e-commerce businesses; 2) further strengthen the UFLPA and forced labor enforcement; 3) expand the Western hemisphere textile and apparel supply chain and encourage more US apparel sourcing from CAFTA-DR members; 4) scrutinize US apparel imports from China and imports from other Asian countries that heavily use textile raw material from China.
Discussion questions for FASH455 (please answer them all):
How do the perspectives of the US textile industry and US fashion brands and retailers diverge concerning CBP’s new strategy? What are the areas in which they share common ground?
Building on the previous question, how can the difference between the US textile industry and US fashion brands and retailers be explained regarding their response to DHS’s new enforcement strategy?
As a sourcing manager for a major US apparel brand with global operations, how do you plan to adjust your company’s sourcing practices in light of DHS’s new strategy? You can list 1-2 detailed action plans and provide your analysis.
Background
The U.S. Customs and Border Protection (CBP) is an agency within the Department of Homeland Security (DHS), responsible for “regulating and facilitating international trade, collecting import duties, enforcing U.S. trade laws, and protecting the nation’s borders.”
Homeland Security Investigations (HSI) is also a division within the Department of Homeland Security (DHS), responsible for “investigating transnational crime and threats, specifically those criminal organizations that exploit the global infrastructure through which international trade, travel and finance move.”
Students in FASH455 have proposed the following discussion questions based on the readings about the US textile and apparel industry and fashion companies’ sourcing strategies. Everyone is welcome to join the online discussion. For FASH455 students, please address at least two questions and mention the question number (#) in your reply.
#1 As a developed country, should the US prioritize further strengthening highly capital-intensive yarn manufacturing, or should we rebuild a vertically integrated textiles and apparel supply chain (e.g., yarns, fabrics, and garments) at home? What is your recommendation, and why?
#2 In FASH455, we discussed how the US textile industry has experienced a decline in employment despite increasing production volumes, largely due to advancements in technology. However, why is import competition often cited in the media as the single largest threat to the US textile industry?
#3 While studies show that US fashion companies are reducing “China exposure,” measured in quantity, China still accounted for 36.1% of US apparel imports in 2023, even higher than 34.7% in 2022. How can we explain this phenomenon? What factors have made US fashion companies hesitant to move away from China?
#4 How will US fashion companies’ growing interest in carrying more sustainable textiles and apparel affect their sourcing destinations and supply chains? Will developing countries with cheap labor and/or developed countries with the right capital and technology be the winners in the sustainability movement? Please provide your thoughts.
#5 Will the growing demand for supply chain transparency and traceability reduce the incentives or add additional burdens for fashion companies to diversify their supply chain further? What are the benefits of pursuing sourcing diversification other than mitigating the potential sourcing risks?
#6 What is your vision for the use of AI in apparel sourcing? What key sourcing and supply chain problems facing fashion brands and retailers can AI potentially solve?
First, affected by the macro economy, US apparel import volume in 2023 suffered the most significant decline since the pandemic. Specifically, US apparel imports decreased by 22% in quantity and value in 2023 compared to 2022, with none of the top ten suppliers experiencing positive growth.
Nevertheless, after several months of straight decline, US apparel imports finally bounced back in December 2023. Thanks to the holiday season and a gradual improvement of the US economy, seasonally adjusted US apparel imports in December 2023 were about 4.5% higher in quantity and 4.2% higher in value than the previous month. Highly consistent with trends, the US Consumer Confidence Index (CCI) increased from 67.2 in November to 76.4 in December (January 2019=100), suggesting US households turned more confident about their financial outlook and willing to spend. That being said, the latest January 2024 International Monetary Fund (IMF) forecasts still predicted the US GDP growth would slow down from 2.5% in 2023 to 2.1% in 2024. Thus, whether the US apparel import volume could continue to maintain growth after the holiday season remains a big question mark.
Second, while the pace of sourcing cost increases has slowed, the costs and financial pressure facing US fashion companies are far from over. Specifically, as of December 2023, the price index of US apparel imports stood at 106 (January 2019=100), almost no change from January 2023. However, two emerging trends are worth watching. One is the declining US apparel retail price index since August 2023, which means US fashion companies may have to sacrifice their profits to attract consumers to the store. The second trend is the surging shipping costs as a result of the recent Red Sea shipping crisis, which were not reflected in the December price data. According to J.P. Morgan, during the week of January 25, 2024, the container shipping rates from China to the US West Coast and East Coast saw a significant spike of around 140% and 120% from November 2023, respectively. Even worse, there is no sign that the Red Sea crisis will soon be solved. Therefore, 2024 could pose another year of financial challenges for many US fashion companies.
Third, diversification remained a pivotal trend in US fashion companies’ sourcing strategy in 2023. For example, the Herfindahl–Hirschman index (HHI), a commonly used measurement of market concentration, went down from 0.105 in 2022 to 0.101 in 2022, suggesting that US apparel imports came from even more diverse sources.
Notably, measured in value, only 71.6% of US apparel imports came from Asia in 2023, the lowest in five years. Highly consistent with the US Fashion Industry Association’s Benchmarking Survey results, OTEXA’s data reflected companies’ intention to diversify their sourcing away from Asia due to increasing geopolitical concerns, particularly the rising US-China strategic competition.
However, it should be noted that Asia’s reduced market share did not benefit “near-shoring” from the Western hemisphere much. For example, in 2023, approximately 14.6% of US apparel imports originated from USMCA and CAFTA-DR members, nearly the same as the 14.3% recorded in 2022. Instead, US apparel imports outside Asia and the Western Hemisphere jumped to 11.4% in 2023 from 9.8% a year ago. Some emerging EU and African suppliers, such as Turkey, Romania, Morocco, and Tunisia, performed relatively well in the US market in 2023, although their market shares remained small. We could highly expect the sourcing diversification strategy to continue in 2024 as many companies regard the strategy as the most effective to mitigate various market uncertainties and sourcing risks.
Fourth, US fashion companies continued reducing their China exposure as much as possible, but China will remain a key player in the game. On the one hand, about 20.0% of US apparel imports in value and 25.9% in quantity came from China in 2023, both hit a new low in the past decade. Recent studies also show that it became increasingly common for China to no longer be the largest source of apparel imports for many US fashion companies.
However, China remains highly competitive in terms of the variety of products it offers. For example, the export product diversification index, calculated based on trade data at the 6-digit HTS code level (Chapters 61 and 62), shows that few other countries can match China’s product variety. Likewise, product level data collected from industry sources indicates that China offered far more clothing styles (measured in Stock Keeping Units, SKUs) than its competitors in 2023. According to the results, rather than identifying 1-2 specific “next China,” US fashion companies appeared to leverage “category killers”—for example, utilizing Vietnam as a sourcing base for outerwear, underwear, and swimwear; India for dresses, and Bangladesh for large-volume basic knitwear items.
Related to this, another recent study found that the top five largest Asian suppliers next to China, including Vietnam, Bangladesh, Indonesia, India, and Cambodia, collectively can offer diverse product categories almost comparable to those from China in the US market.
Fifth, trade data reveals early signs that US fashion companies are gradually reducing sourcing cotton apparel products from Asia because of the implementation of the Uyghur Forced Labor Prevention Act (UFLPA). Notably, when concerns about cotton made by Xinjiang forced labor initially emerged in 2018, US fashion companies quickly shifted sourcing orders for cotton apparel (OTEXA code 31) from China to other Asian countries. However, UFLPA’s enforcement increasingly targets imports from Asian countries other than China due to the highly integrated regional textile and apparel supply chain and Asian countries’ heavy reliance on textile inputs from China. Consequently, Asia (excluding China) accounted for a declining share in the total imports of US cotton apparel in 2023.
Meanwhile, affected by UFLPA’s enforcement, only 11.8% of US cotton apparel imports came from China in 2023, marking a further decline from 13% in 2022 and reaching a new low for the past decade. China also deliberately decreased the percentage of cotton apparel in its total apparel exports to the US market, dropping from nearly 40% in 2017 to only 25% in 2023. In comparison, cotton apparel consistently represented about 45% of total US apparel imports during the same period.
Additionally, while there was no substantial increase in the volume of US apparel imports from CAFTA-DR members, as a silver lining, the utilization of the trade agreement improved. In 2023, about 19.2% of US apparel imports claimed duty-free benefits under US free trade agreements and trade preference programs, a notable increase from 17.7% in 2022. Most such imports came under CAFTA-DR (45.4%) and USMCA (19.7%).
Meanwhile, in the first 12 months of 2023 (latest OTEXA data), about 70.2% of US apparel imports came from CAFTA-DR members claimed the duty-free benefit, up from 66.6% the same period a year ago. Particularly, 65.4% of US apparel imports under CAFTA-DR complied with the yarn-forward rules of origin in 2023, a notable increase from 61.3% in 2022. Another 2.6% of imports utilized the agreement’s short supply mechanism, which also went up from 2.3% in 2022. The results could reflect an ever more integrated regional textile and apparel supply chain among CAFTA-DR members due to increasing investments made in the region in recent years. However, there is still much that needs to be done to effectively increase the volume of US apparel imports from the region.
Textiles and apparel “Made in the USA” have gained growing attention in recent years amid the increasing supply chain disruptions during the pandemic, the rising geopolitical tensions worldwide, and consumers’ increasing interest in sustainable apparel and faster speed to market. Statistics from the U.S. Bureau of Economic Analysis showed that U.S. textile and apparel production totaled nearly $28 billion in 2022, a record high in the most recent five years. Meanwhile, unlike in the old days, a growing proportion of textiles and apparel “Made in the USA” are sold overseas today. For example, according to the Office of Textiles and Apparel (OTEXA) under the U.S. Department of Commerce, U.S. textiles and apparel exports exceeded $24.8 billion in 2022, up nearly 12% from ten years ago.
By leveraging U.S. Department of Commerce Office of Textiles and Apparel (OTEXA)’s “Made in U.S.A. Sourcing & Products Directory,” this study explored U.S. textiles and apparel manufacturers’ detailed production and export practices. Altogether, 432 manufacturers included in the directory as of October 1, 2023, were analyzed. These manufacturers explicitly mentioned making one of the following products: fiber, yarn, fabric, garment, home textiles, and technical textiles.
Key findings:
First, U.S. textile manufacturers exhibit a notable geographic concentration, whereas apparel manufacturers are dispersed throughout the country. Meanwhile, by the number of textile and apparel manufacturers, California and North Carolina are the only two states that rank in the top five across all product categories, showcasing the most comprehensive textile and apparel supply chain there.
Second, U.S. textile and apparel manufacturers have a high concentration of small and medium-sized enterprises (SMEs). Highly consistent with the macro statistics, few textile and apparel manufacturers in the OTEXA database reported having more than 500 employees. Particularly, over 74% of apparel and nearly 60% of home textile manufacturers are “micro-factories” with less than 50 employees.
Third, U.S. textile and apparel manufacturers have limited vertical manufacturing capability. A vertically integrated manufacturer generally makes products covering various production stages, from raw materials to finished products. Results show that only one-third of U.S. textile and apparel manufacturers in OTEXA’s database reported making more than one product type (e.g., yarn or fabric). Meanwhile, specific types of vertically integrated production models are relatively popular among U.S. textile and apparel manufacturers, such as:
Apparel + home textiles (5.8%)
Fabric + technical textiles (5.1%)
Yarn + fabric (3.9%)
However, the lack of fabric mills (N=38 out of 432) appears to be a critical bottleneck preventing the building of a more vertically integrated U.S. textile and apparel supply chain.
Fourth, it is not uncommon for U.S. textile and apparel manufacturers to use imported components. Specifically, among the manufacturers in the OTEXA database, nearly 20% of apparel and fabric mills explicitly say they utilized imported components. In comparison, given the product nature, fiber and yarn manufacturers had a lower percentage using imported components (11%). Furthermore, smaller U.S. textile and apparel manufacturers appear to be more likely to use imported components. For example, whereas 20% of manufacturers with less than 50 employees used imported input, only 10.2% of those with 50-499 employees and 7.7% with 500 or more employees did so. The results indicate the necessity of supporting SME U.S. textile and apparel manufacturers to access textile input through mechanisms such as the Miscellaneous Tariff Bill (MTB).
Fifth, many US textile and apparel manufacturers have already explored overseas markets. Specifically, factories making textile products reported a higher percentage of engagement in exports, including fiber and yarn manufacturers (68.4%), fabric mills (78.9%), and technical textiles producers (69.1%). In comparison, relatively fewer U.S. apparel and home textile producers reported selling overseas.
Sixth, U.S. textile and apparel manufacturers’ export markets are relatively concentrated. Specifically, as many as 72% of apparel mills and 57% of home textiles manufacturers in the OTEXA database reported selling their products in less than two markets. These manufacturers also have a high percentage of selling to the U.S. domestic market. Likewise, because of the reliance on the Western Hemisphere supply chain, more than half of U.S. fiber and yarn manufacturers reported only selling in two markets or less. In comparison, reflecting the global demand for their products, U.S. technical textile manufacturers had the most diverse markets, with nearly 40% exporting to more than ten countries.
Seventh, while the Western Hemisphere remains the top export market, many U.S. textile and apparel manufacturers also export to Asia, Europe, and the rest of the world. For example, nearly half of U.S. textile and apparel manufacturers in OTEXA’s database reported exporting to Asia, and over 60% of U.S. technical textile manufacturers sold their products to European customers.
Additionally, over half of U.S. textile and apparel mills engaged in exports leveraged U.S. free trade agreements (FTAs). U.S. textile mills, on average, reported a higher percentage of using FTAs than apparel and home textile manufacturers. As most U.S.-led FTAs adopt the yarn-forward rules of origin, the results suggest that while such a rule may favor the export of U.S. textile products, its effectiveness and relevance in supporting U.S. apparel exports could be revisited.
Moreover, in line with the macro trade statistics, U.S. textile and apparel manufacturers in the OTEXA database reported a relatively high usage of USMCA, given Mexico and Canada being the two most important export markets. In comparison, U.S. textile and apparel manufacturers’ use of CAFTA-DR was notably lower, even for fiber and yarn manufacturers (37%) and fabric mills (33.3%).
by Kendall Ludwig, Miranda Rack and Sheng Lu
Picture above: On December 13, 2023, Kendall Ludwig and Miranda Rack, FASH 4+1 graduate students and Dr. Sheng Lu, had the unique opportunity to present the study’s findings to senior U.S. trade officials from OTEXA and the Office of the U.S. Trade Representative (USTR) in Washington DC, including Jennifer Knight (Deputy Assistant Secretary for Textiles, Consumer Goods and Materials), Laurie-Ann Agama (Acting Assistant US Trade Representative for Textiles), Maria D’Andrea-Yothers (Director of OTEXA), Natalie Hanson (Deputy Assistant US Trade Representative for Textiles) and Richard Stetson (Deputy Director of OTEXA).
Check the Udaily article that features the research project and the presentation (February 2024).
In December 2023, Just-Style consulted a panel of industry experts and scholars in its Outlook 2024–what’s next for apparel sourcing briefing. Below is my contribution to the report. Welcome any comments and suggestions!
What’s next for apparel sourcing?
Apparel sourcing is never about abrupt changes. However, fashion companies’ sourcing practices, from their crucial sourcing factors and sourcing destinations to operational priorities, will gradually shift in 2024 in response to the evolving business environment.
First, besides conventional sourcing factors like costs, speed to market, and compliance, fashion companies will increasingly emphasize flexibility and agility in vendor selection. One driving factor is economic uncertainty. For example, according to leading international organizations such as the World Bank and the International Monetary Fund (IMF), the world economy will likely grow relatively slowly at around 2.6%-3% in 2024. However, it is not uncommon that the economy and consumers’ demand for clothing could perform much better than expected. This means companies need to be ready for all occasions. Likewise, geopolitical tensions, from the Russia-Ukraine war and the US-China decoupling to the military conflict in the Middle East, could cause severe supply chain disruptions anytime and anywhere. Thus, fashion companies need to rely on a more flexible and agile supply chain to address market uncertainties and mitigate unpredictable sourcing risks.
Secondly, it will be interesting to watch in 2024 to what extent fashion companies will further reduce their exposure to China. On the one hand, it is no surprise that fashion companies are reducing finished garments sourcing from China as much as possible. However, fashion brands and retailers also admit that it is difficult to find practical alternatives to China in the short to medium terms regarding raw textile materials and orders that require small runs and great variety. Meanwhile, investments from China are flowing into regions considered alternative sourcing destinations, such as the rest of Asia and Central America. These new investments could complicate the efforts to limit exposure to China and potentially strengthen, not weaken, China’s position in the apparel supply chains. And stakeholders’ viewpoints on “investments from China” appear even more subtle and complicated.
Third, regulations “behind the borders” could more significantly affect fashion companies’ sourcing practices in 2024, particularly in sustainability-related areas. While sustainability is already a buzzword, fashion companies must deal with increasingly complex legal requirements to achieve sustainability. Take textile recycling, for example. The enforcement of the Uyghur Forced Labor Prevention Act (UFLPA) on recycled cotton, the US Federal Trade Commission’s expanded Green Guides, the EU’s extended producer responsibility (EPR) program and its strategy for sustainable textiles, and many state-level legislations on textile waste (e.g., California Textile Recycling Legislation) may all affect companies’ production and sourcing practices for such products. Fashion companies’ sourcing, legal, and sustainability teams will need to work ever more closely to ensure “sustainable apparel” can be available to customers.
Apparel industry challenges and opportunities
In 2024, a slow-growing or stagnant world economy will persist as a significant challenge for fashion companies. Without sourcing orders from fashion brands and retailers, many small and medium-sized manufacturers in the developing world may struggle to survive, leaving garment workers in a precarious financial situation. China’s economic slowdown could worsen the situation as many developing countries increasingly treat China as an emerging export market. With shrinking domestic demand, more “Made in China” apparel could enter the international market and intensify the price competition.
Another challenge is the rising geopolitical tensions and political instability in major apparel-producing countries. For example, while a broad base supports the early renewal of the African Growth and Opportunity Act (AGOA), which will expire in 2025, the reported human rights violations in some essential apparel exporting countries in the region could complicate the renewal process in US Congress. Likewise, even though the Biden administration is keen to encourage fashion companies to expand sourcing from Central America, political instability there, from Nicaragua to Haiti, makes fashion companies hesitant to make long-term sourcing commitments and investments. Furthermore, 2024 is the election year for many countries, from the US to Taiwan. We cannot rule out the possibility that unexpected incidents could trigger additional instability or even new conflict.
On the positive side, it is encouraging to see fashion companies continue to invest in new technologies to improve their operational efficiency in apparel sourcing. Digital product passports, 3D product design, PLM, blockchain, Generative AI, and various supply chain traceability tools are among the many technologies fashion companies actively explore. Fashion companies hope to leverage these tools to improve their supply chain transparency, strengthen relationships with key vendors, reduce textile waste, accelerate product development, and achieve financial returns.
It is also a critical time to rethink and reform fashion education. In addition to traditional curricula like apparel design and merchandising, we need more partnerships between the apparel industry and educational institutions to expose students to the real world. More direct engagement with Gen Z will also benefit fashion companies tremendously, allowing them to understand their future core customers and prepare qualified next-generation talents.
The full article is here(Just-Style access required). Below are the key findings:
Based on a content analysis of the annual reports of about 30 largest US fashion brands and retailers from 2018 to 2023, this study aims to identify these companies’ most critical evolving sourcing practices, including their sourcing destination adjustment, primary sourcing factors, and emerging sourcing-related “hot topics.” The findings provide critical market intelligence, informing US fashion companies about their peers’ emerging sourcing trends and popular practices. The results show that:
First, maintaining a relatively diverse sourcing base remains common among US fashion companies. Results show that large-size companies today typically source from more than 20 countries. One critical factor behind fashion companies’ sourcing diversification strategies is that no single supplying country is “perfect,” given the increasingly complex sourcing factors. Sourcing diversification allows fashion companies to balance various sourcing factors. For example, according to company #19, “the (sourcing diversification) approach provides us with the greatest flexibility in identifying the appropriate manufacturers while considering quality, cost, timing of product delivery and other criteria.” On the other hand, sourcing diversification enables companies to adapt quickly to market uncertainties and enjoy supply chain flexibility and resilience.
Second, while US fashion companies are not necessarily leaving any particular countries they source from, many have substantially reduced the number of vendors they work with over the past few years. Specifically, out of the 30 fashion companies the study examined, over 60% explicitly mentioned they consolidated their sourcing base at the vendor level from 2017/2018 to 2022/2023, although the degree varied. For example:
Company #4, a leading sportswear brand, cut its contracted factories from 363 to 291 (or down 19.8%)
Company #6, which owns several jeans and sportswear brands, reduced its contracted factories from 1,000 to around 340 (or down 66%)
Company #9, a well-known specialty clothing store, cut its vendors from 800 to 250 (or down 68.8%)
Company #26, a specialty clothing store targeting the youth, cut its vendors from 150 to around 119 (or down 20.7%)
Company #28, a discount department store, cut its vendors from 3,100 to around 2,800 (or down 9.7%)
Associated with the trend of “country diversification and vendor consolidation,” US fashion companies are increasingly interested in working with “super vendors,” e.g., those with multiple country presence or vertical manufacturing capability. The use of “super vendor” can also be observed in fashion companies’ willingness to give more sourcing orders to their top suppliers. For example, Company #18, a casual and outdoor wear retailer, reduced its vendors from 200 in 2017/2018 to 110 in 2022/2023, but increased the cap of sourcing orders for its top 10 vendors from 40% to 47% over the same period.
Third, regarding the sourcing base, many US fashion companies have intentionally reduced their apparel sourcing from China, given the US-China tariff war, deteriorating bilateral relations, and the forced labor concerns with China’s Xinjiang region (XUAR). Specifically, more than one-third of the examined companies explicitly mentioned their strategy to reduce finished garments sourcing from China. Furthermore, several US fashion companies indicated their “reducing China exposure” strategy would continue, implying China’s market share in the US apparel import market could decrease further.
Nevertheless, even though fewer finished garments are coming from China, US fashion companies admit that China will continue to play a critical role as a textile raw material supplier as no immediate practical alternative is available. For example, Company #20, a specialty clothing chain focusing on trendy and fashionable items, says, “During fiscal 2022, we sourced most of our finished products with partners and suppliers outside the US and we continued to design and purchase fabrics globally, with most coming from China.”
Fourth, in line with trade statistics, US fashion companies consider other Asian suppliers, such as Vietnam, Bangladesh, Cambodia, and Indonesia, as their top choices as China’s alternatives.In comparison, few fashion companies explicitly mentioned moving their sourcing orders from China to Western Hemisphere countries or other regions.
Additionally, regarding emerging “hot topics” related to sourcing:
Geopolitics: the deteriorating US-China relations, escalated trade tensions expanded from tariffs to forced labor, and the potential trade disruptions have concerned US fashion companies significantly. Notably, US fashion companies regard sourcing from China as increasingly risky, with the implementation of the Uyghur Forced Labor Prevention Act (UFLPA) in June 2022. For example, according to Company 2, “The Uyghur Forced Labor Prevention Act and other similar legislation may lead to greater supply chain compliance costs and delays to us and to our vendors.”
Near-shoring: due to the decoupling and de-risking from the China movement, US fashion companies have begun actively exploring near-shoring sourcing opportunities in the Western Hemisphere, particularly from members of the Dominican Republic-Central America Free Trade Agreement (CAFTA-DR). For example, Company #1, the North American manufacturer, disclosed that “(our) Company relies on a number of preferential trade programs (…) including the Dominican Republic – Central America – United States Free Trade Agreement (CAFTA-DR (…) Collectively, these agreements strengthen US economic relations and expand trade with Central America, the Dominican Republic, and Haiti.”
Sustainability and social responsibility: It is noteworthy that aside from climate change and forced labor, which are typically addressed as risk factors, US fashion companies generally hold an optimistic and forward-looking perspective for sustainability, such as new technologies and endeavors toward more sustainable production and sourcing. Terms such as using preferred or recycled materials, supply chain transparency and traceability, and emerging sustainability technologies have been more frequently mentioned in companies’ annual or ESG reports. For example, Company #17 says, “Increase the usage of environmentally preferred materials to comprise 32.6% of the brand’s global materials footprint.”Company #2 adds, “Our goal is to use preferred materials in 100 percent of our products by 2030.” Company #9 states, “We collaborate with suppliers to increase the supply of preferred raw materials.”
Supply chain transparency: US fashion companies attach great importance to improving supply chain transparency and traceability. Compared to the past, fashion companies are more willing to invest in new technologies and digital tools, allowing them to map supply chains and achieve sustainability goals more effectively. Related to this, US fashion companies have actively engaged with industry associations and other industry communities outside the company to stay informed about sustainability trends and learn best practices.
Emma Zuckerman, a New Jersey native, graduated from the University of Delaware in 2016 with a degree in Apparel Design. During her time at UD, she actively participated in the FASH program and engaged in extracurricular activities related to her major. Emma conducted research on functional fashion with Dr. Martha Hall and held positions on the executive board, eventually becoming the President of Synergy Fashion Group in her senior year. She also founded a club dedicated to creating adaptive garments for children with disabilities. After graduation, Emma commenced her career in technical design with Under Armour (UA), accumulating six years of experience across various apparel categories and fabrications. She began in youth basketball, then transitioned through a range of products, from underwear to seamless leggings, woven jackets, and pants. In her later years at Under Armour, she played a significant role in the launch of Curry Brand and the introduction of UA’s first inline women’s basketball apparel line (non-uniform). Presently, Emma holds the position of Senior Technical Designer at Nike, where she contributes to the development of ACG and Nike SB product lines.
In her free time, Emma loves working on personal sewing, patterning, and draping projects. She also loves hiking, skateboarding, baking, swimming, and painting!
Disclaimer: The views expressed in this interview are those of Emma Zuckermanand do not reflect the views or positions of her employer or any affiliated organizations.
Sheng: What does a technical designer do? Can you walk us through your typical day as a technical designer? Also, what makes you love your job?
Emma:Technical designers work on developing clothing – we work with factory partners to take a style from a conceptual sketch to bulk production. For each style, we start by working with our design partners to understand their vision. We create detailed construction sketches, measurement charts, and sometimes original patterns, then compile those into a tech pack along with our designer’s garment sketch and a Bill of Materials outlining all garment components. A factory partner uses the information in that tech pack to make a sample to send back to us. We fit that sample with our team, cutting and pinning until we achieve the desired fit and aesthetic. The factory uses our feedback to create a second sample, and this process repeats until the style is finalized and approved for production. Throughout the process, we keep the tech pack up-to-date and ensure it accurately reflects the style we’re developing.
There are so many things I love about my job! The subjects of fitting and patterning are fascinating to me, and there will always be so much to learn about them. I love that throughout my career, there will be no limit to how much I can learn and how much my skills can grow. I exercise my creativity while also exercising the mathematical side of my brain, so my job is constantly challenging me in really interesting ways. I get to work with people around the world, learn about other cultures, backgrounds, and communication styles, and collaborate with amazingly talented teammates.
Sheng: How does a technical designer get involved in a fashion company’s sourcing process?
Emma: A technical designer’s level of involvement in the sourcing process varies from company to company, but it is always extremely helpful to work closely with our sourcing team. Since both technical designers and the sourcing team communicate with factories, we often check in with each other to make sure the information we’re sending is consistent. We (technical designers) can help provide feedback on factory capabilities and sample quality. Understanding the sourcing process helps us gain insight into why our sourcing partners allocate certain styles to specific factories (for example, a factory might have expertise with woven fabrics, outerwear, or embroidery; a style might qualify for a lower duty rate if sourced from a specific region; some factories may reach their maximum capacity for new styles more quickly than others).
Technical designers work most closely with our sourcing partners during costing conversations. Factories send cost sheets for every style at several key points during development. These cost sheets break down every element that contributes to the final cost of making the garment, from materials to trims, to time spent. One major role of a sourcing partner (or, at some companies, a product developer) is to process these cost sheets and advise the rest of the team on how much cost needs to be saved, and/or what steps can be taken to save cost, to ensure the style is profitable. Technical designers can use our garment construction and patterning expertise to effectively contribute to these conversations (which leads nicely into the next question)!
Sheng: We know production cost is a critical sourcing factor for fashion brands and retailers. From a technical designer’s perspective, what factors affect garment production and its sourcing costs? What strategies can be employed to manage these costs, beyond labor wages?
Emma: So many factors affect production cost – at the top of my mind are material cost (for fabric yardage and individual trims like zippers) and cut/make time (which includes labor cost and factory overhead). Material usage and cut/make time are both factors that technical designers can heavily influence during costing conversations with our design and sourcing teams.
Material usage: Marker efficiency refers to the amount of fabric used per garment compared to the amount wasted. The more closely pattern pieces can fit together, the less space for fabric scraps between them and the more efficient a marker will be. A technical designer can use their patterning experience to advise pattern shapes that will contribute to marker efficiency. For example, adding or removing a seam may allow pattern pieces to fit more closely together. Choosing where and when to engineer print placements – for example, matching stripes across a seam – will also impact the way pattern pieces can be arranged and, therefore, how efficient a marker can be. An efficient marker will both save cost and minimize fabric waste.
More on material usage, and cut/make time: Each construction choice contributes to the final cost of making the garment. For example, when it comes to finishing seam allowances, binding a seam allowance will take longer and use more material than an overlock stitch. For that reason, binding a seam allowance will also be more expensive. As garment construction experts, we lead conversations about style details, the time it will take to construct them, and other options that could potentially save time and material. This helps our team make informed choices that consider both cost and aesthetics.
Sheng: What are your thoughts on the trend of fashion companies using more sustainable materials like recycled cotton in their products?
Emma: I support fashion companies making an effort toward more sustainable & ethical production, and using recycled materials is an important step. Fabric with recycled fiber content can be more expensive and more difficult to source than traditional fabric, which may discourage some companies from moving in that direction. I’m hopeful that this trend will continue and that as it gains popularity, fabric with recycled fiber content will become easier to source over time.
Speaking of ethical production, I also would like to see fashion industry brands take additional steps toward a more earth-positive and people-positive existence, including:
Considering local labor laws, worker wages, and working conditions when selecting factories
Implementing garment repair programs to extend the lifecycle of their styles
Improving accuracy of demand planning to reduce excess inventory and/or considering donation or upcycling of excess inventory
Expanding size ranges and accurately grading sizes to fit well on plus-sized consumers
Moving away from gendering clothing as “men’s” or “women’s;” during sample development, checking that samples fit well on lots of body types (including individuals who have had gender-affirming care, individuals who haven’t, individuals who may be wearing gender affirming garments like binders)
Diversifying the company workforce at every level, from entry-level to leadership to c-suite
Expanding representation in advertising campaigns to reflect the diversity of global consumers
Supporting nonprofit agencies whose work aligns with company values
Some companies are doing a great job of fulfilling some, most, or all of the items on my above wish list, but we know that the fashion industry has a long way to go when it comes to impacting our earth and our societies positively. I think it’s our job as newer fashion industry professionals to speak up about all of this and start to push our industry in a better direction.
Sheng: What other key industry trends will you closely monitor in 2023?
Emma: I am so interested in the increased use of 2D and 3D patterning software. Programs such as Gerber, Optitex, Clo, and Browzwear are already changing the design and development process in fascinating ways. Experience in any of these programs has already become a very valuable asset for job applicants. I’m curious whether garments will ever be sold to consumers based only on 3D renderings, and if body scanning will become a more mainstream part of the shopping process.
I’m also curious how the increased use of 2D and 3D patterning software will impact more traditional design processes, like paper patterns and draping. Will these arts be preserved? Are there types of apparel that will always need to be draped or patterned physically? Will students 20 years from now still learn to pattern and drape the way we did, or will these skills be fully computer-based?
Sheng: Any reflections on your experiences at UD and FASH? what advice would you offer current students preparing for a career in fashion after graduation?
Emma: I feel so lucky to have had the experience that I did at UD and within the FASH program. I learned so much in my patterning, draping, collections, textiles, and sourcing classes (big shoutout to Dr. Lu!) that has stayed with me and helped me find success in my current job.
I have so much advice! If you’re looking for a career in technical design, practice any patterning software you can access as much as you can. As you begin applying to jobs, try to reach out to contacts at the companies you’re applying to (even if it means sending a random LinkedIn message to a fellow UD grad, or asking a professor/another student to help connect you with someone). Start your career with curiosity and an open mind – you will learn so much on the job that isn’t covered in school. Try to find a mentor, or several mentors, who’ve had work experiences similar to yours. A mentor who you can trust and rely on for advice makes a huge difference when work gets challenging. Speaking of which – work does get challenging, and that’s okay! Work on learning to identify situations that you can work through and learn from (which are hugely beneficial to your personal growth and career development), compared to work environments that are more consistently unhealthy or not providing what you need (which are an indication that it’s time to make a change). If you have coworkers you trust, sharing salary information openly is a great way to make sure everyone’s skills and contributions are being valued appropriately.
Enjoy your time in college and in the FASH program. I miss it!
Argument: The U.S. textile manufacturing industry has been a winner of globalization
Comment #1: While it is true that many Americans lost their jobs due to the increase in trade, there are more benefits to both importing and exporting rather than the mercantilist view of trade. Increasing trade and globalization, especially during the Clinton administration, was an opportunity to develop strong relationships with other nations. The value of U.S. textile exports since 2000 has risen by 30% for yarn and 15% for fabric, after the establishment of agreements such as NAFTA. Additionally, one of the U.S. apparel manufacturers in the video used machinery for their production from Sweden. Without globalization and trade, they would not be able to use this high-tech equipment. All in all, U.S. textile manufacturing sector benefits from both importing and exporting goods.
Comment #2: Deeper down, the US textile sector seems to be winning in the long run. The squeeze that globalization has placed on them has allowed for innovation within the industry as they fight to stay relevant and compete with overseas goods. Operational slack such as high turnover jobs have been eliminated with automation, and US manufacturers gained a new branding niche that overseas companies do not: a US “personal touch.” Consumers may now be more willing to pay more for a garment just because it says it is made in the USA. USA-made clothing may now be perceived as higher quality and more scarce. The sentiment towards US-made goods and their quality could enact change to reduce overseas reliance, which is a win for US manufacturing in the long run. Additionally, globalization expands the export market for the US textile manufacturing sector.
Comment #3: As discussed in the video, there is a growing trend of reshoring and regionalization in some manufacturing sectors, including textiles. Some U.S. textile manufacturers have seized this opportunity to bring production back to the United States, capitalizing on the advantages of local supply chains, quality control, and speed to market. The video also shows how technology and automation can help streamline production processes and make manufacturing more competitive, even in higher-cost regions like the United States. US textile manufacturers have invested in innovation and automation, making them competitive in producing textiles with advanced features and properties in today’s global economy. It is globalization that is pushing the US textile industry to adopt these new technologies and continue improving its international competitiveness.”
Argument: the U.S. textile manufacturing industry has been a loser of globalization
Comment #4: One of the biggest arguments for globalization is the lower prices & affordability for the consumer. From this perspective, it seemed that the United States was a winner of globalization as a whole. However, when beginning to look at the consequences of moving production overseas, we not only see the textile manufacturing sector being affected, but we also see this impact disperse to the communities in America as well. When brands offshore and outsource production overseas for lower prices & labor, our very own US textile manufacturing industry is losing out on this business. It also forces this industry into a highly competitive environment that does not have equal “playing fields” and does not have insurance/protection in case environmental factors ruin crops. The US has clear labor laws and human rights policies (as well as increasing environmental policies), whereas their cotton-growing competitors, for instance, do not have to follow the same rules. This allows labor exploitation to decrease costs and makes US companies seem unappealing or less competitive.
Comment #5: Over the past few decades, the number of manufacturing jobs in the US textile industry has plummeted after companies began moving production overseas, specifically to countries like China, which have preferential treatment. These foreign facilities can produce things much faster and cheaper because the standards and regulations are completely different than those of the United States. Free trade does not consider these differences in labor and environmental laws, making it much less “free” than it claims. As countries overseas– specifically China and regions like Xinjiang– continue to not play by the rules, the US is forced to keep up by implementing things like the Toyota System…Americans want to be the best in manufacturing and globalization often gets in the way of this. With near-shoring, the US can reclaim high-quality, American-made garments while helping with job security and sustainability.
Comment #6: Overall, I believe that the U.S. textile manufacturing industry is a loser of globalization and international trade, mostly due to the competition from overseas. This competition includes more manufacturers from other countries, but also the competition of pricing since other oversea manufacturers are able to sell their cotton/textile materials at a lower price. Since the U.S. struggles to compete with these lower prices, they are forced to look for another way to have a competitive advantage in the textile manufacturing sector, such as lean manufacturing and technology improvements. At Carolina Cotton Works, Bryan Ashby shares how they have increased efficiency and use high-quality machines (note: imported) for their products. Although this sounds great, this also means that there are fewer workers.
Comment #7: Globalization creates a trade dependence on imports. It’s important we don’t depend on things for when things happen that we can’t predict like the pandemic where we can’t import anymore. Since there was a lack of local textile manufacturing and sourcing in the United States compared to what was being imported, there was less of a chance for technological advances and improvement in the United States textile manufacturing sector. Post Globalization, however, may be the chance for the United States to bring back the textile manufacturing sector momentum. I think this because the United States has seen the result of heavily relying on other countries for their cheap labor/sources, and this could add extra motivation for companies to want to figure out better alternatives in manufacturing in their own country.
Comment #8: I think currently the US is a loser to globalization only because brands want to get the product for cheap. I think brands think that would create more profit that way. However, I do believe we could get to a future where more things would be created in the US and wouldn’t have to pay that much in tariffs and other external prices. I think it would help boost people to work more. I think people are worried about making things in our country because of the relations we have with other countries.
Discussion questions:
Do you agree or disagree with any particular argument above? Any follow-up comments on the impact of globalization on the US textile manufacturing sector? What should government do with trade given the debates? Please feel free to share any additional thoughts.
This article comprehensively reviewed the world textiles and clothing trade patterns in 2022 based on the newly released World Trade Organization Statistical Review 2023 and data from the United Nations (UNComtrade). Affected by the slowing world economy and fashion companies’ evolving sourcing strategies in response to the rising geopolitical tensions, mainly linked to China, the world’s textiles and clothing trade in 2022 displayed several notable patterns different from the past.
Pattern #1: The expansion of world clothing exports witnessed a notable deceleration in 2022, primarily attributed to the economic downturn. Meanwhile, the world’s textile exports decreased from the previous year, affected by the reduced demand for textile raw materials used to produce personal protective equipment (PPE) as the pandemic waned.
The world’sclothing exports totaled $576 billion in 2022, up 5 percent year over year, much slower than the remarkable 20 percent growth in 2021. The slowed economic growth plus the unprecedented high inflation in major apparel import markets, particularly the United States and Western European countries, adversely affected consumers’ available budget for discretionary expenditures, including clothing purchases.
The world’s textile exports fell by 4.2 percent in 2022, totaling $339 billion, lagging behind most industrial sectors. Such a pattern was understandable as the demand for PPE and related textile raw materials substantially decreased with the pandemic nearing its end.
Pattern #2: China continued to lose market share in clothing exports, which benefited other leading apparel exporters in Asia. Notably, for the first time, Bangladesh surpassed Vietnam and ranked as the world’s second-largest apparel exporter in 2022.
In value, China remained the world’s largest apparel exporter in 2022. However, China’s clothing exports experienced a growth of 3.6 percent, below the global average of 5.0 percent, positioning China at the bottom of the top ten exporters.
China’s global market share in clothing exports dropped to 31.7 percent in 2022, marking its lowest point since the pandemic and a significant decrease from the approximate 38 percent recorded from 2015 to 2018. In fact, China lost market share in almost all major clothing import markets, including the US, the EU, Canada, and Japan. The concerns about the risks of forced labor linked to sourcing from China and the deteriorating US-China relations were among the primary factors driving fashion companies’ eagerness to reduce their ‘China exposure” further.
China has been diversifying its clothing exports beyond the traditional Western markets in response to the challenging business environment. For example, from 2021 to 2022, Asian countries, especially members of the Regional Comprehensive Economic Partnership (RCEP), became relatively more important clothing export markets for China. Nevertheless, since RCEP members primarily consist of developing economies with ambitions to enhance their own clothing production, the long-term growth prospects for their import demand of ‘Made in China’ clothing remain uncertain.
Bangladesh achieved a new record high in its market share of world clothing exports, reaching 7.9 percent in 2022, which exceeded Vietnam’s 6.1 percent. Many fashion companies regard Bangladesh as a promising clothing-sourcing destination with growth potential because of its capability to make cotton garments as China’s alternatives, competitive price, and reduced social compliance risks.
Fashion companies’ efforts to “de-risking from China” also resulted in the robust growth of clothing exports from other large-scale Asian clothing producers in 2022, including Vietnam (up 13 percent), Cambodia (up 12 percent), and India (up 10 percent). In other words, despite the concerns about China, fashion companies still treat Asia as their primary sourcing destination.
Pattern #3: Developed countries stay critical textile exporters, and middle-income developing countries gradually build new textile production and export capability.
The European Union members and the United States stayed critical textile exporters, accounting for 25.1 percent of the world’s textile exports in 2022, up from 24.5 percent in 2021 and 23.2 percent in 2020. Thanks to the increasing demand from apparel producers in the Western Hemisphere, U.S. textile exports increased by 5 percent in 2022, the highest among the world’s top ten.
As a persistent long-term trend, middle-income developing countries have consistently been strengthening their textile production and export capability. For example, China, Vietnam, Turkey, and India’s market shares in the world’s textile exports have steadily risen. They collectively accounted for 56.8 percent of the world’s clothing exports in 2022, a notable increase from only 40 percent in 2010. Also, over time, these middle-income developing countries have achieved a more balanced textiles-to-clothing export ratio.
Pattern #4: Regional textile and apparel trade patterns strengthened further with the growing popularity of near-shoring, particularly in the Western Hemisphere. However, an early indication has emerged that Asian countries are diversifying their sources of textile raw materials away from China to mitigate growing risks.
The regional textile and apparel supply chains were in good shape in Asia and Europe. For example, nearly 80 percent of Asian countries’ textile input and apparel imports came from within the region in 2022. Likewise, approximately half of EU countries’ textile imports were intra-region trade in 2022, and one-third were for apparel.
The Western Hemisphere (WH) textile and apparel supply chain became more integrated in 2022 thanks to the booming near-shoring trends. For example, 20.8 percent of WH countries’ textile imports came from within the region in 2022, up from 20.1 percent in the previous year. Likewise, about 15.1 percent of WH countries’ apparel imports came from within the region in 2022, higher than 14.7 percent in 2021 and 13.9 percent in 2022.
Compared with Asia and the EU, SSA clothing producers used much fewer locally-made textiles (i.e., stagnant at around 11% from 2011 to 2022), reflecting the region’s lack of textile manufacturing capability. A more comprehensive examination of strategies for bolstering the textile manufacturing sector in Sub-Saharan Africa, particularly in light of the recently enacted African Continental Free Trade Area (AfCFTA) agreement, might be warranted.
Additionally, data suggests that Asian countries began diversifying their textile imports away from China to mitigate supply chain risks. For example, with the official implementation of anti-forced labor legislation in the US and other primary apparel import markets directly targeting cotton made in China’s Xinjiang region, Asian countries significantly reduced their cotton fabric imports (SITC code 652) from China in 2022. Instead, Asian countries other than China accounted for 46.3 percent of the region’s textile supply in 2022, up from around 42-43 percent between 2019 and 2021.
It is critical to watch how willing, to what extent, and how quickly Asian countries can effectively reduce their dependency on textile supplies from China. The result is also an important reminder that Western fashion companies’ de-risking from China could exert significant and broad impacts across the entire supply chain beyond finished goods.
#1U.S. fashion companies are deeply concerned about the deteriorating U.S.-China bilateral relationship and plan to accelerate “reducing China exposure” to mitigate the risks.
Respondents identified “Finding a new sourcing base other than China” as a more prominent challenge in 2023 than the previous year (i.e., 4th in 2023 vs. 11th in 2022).
This year, over 40 percent of respondents reported sourcing less than 10 percent of their apparel products from China, up from 30 percent of respondents a year ago and a notable surge from only 20 percent in 2019. Similarly, a new record high of 61 percent of respondents no longer use China as their top supplier in 2023, up from 50 percent of respondents in 2022 and much higher than only 25-30 percent before the pandemic.
Nearly 80 percentof respondents plan to reduce apparel sourcing from China over the next two years, with a record high of 15 percent planning to “strongly decrease” sourcing from the country. This strong sentiment was not present in past studies. Notably, large-size U.S. fashion companies (with 1,000+ employees) that currently source more than 10 percent of their apparel products from China are among the most eager to de-risk.
#2 Tackling forced labor risks in the supply chain remains a significant challenge confronting U.S. fashion companies in 2023.
“Managing the forced labor risks in the supply chain” ranks as the 2nd top business challenge in 2023, with 64 percent of respondents rating the issue as one of their top five concerns.
Most surveyed U.S. fashion companies have taken a comprehensive approach to mitigating forced labor risks in the supply chain. Three practices, including “asking vendors to provide more detailed social compliance information,” “attending workshops and other educational events to understand related regulations better,” and “intentionally reducing sourcing from high-risk countries,” are the most commonly adopted by respondents (over 80 percent) in response to forced labor risks and the UFLPA’s implementation.
Since January 1, 2023, U.S. Customs and Border Protection (CBP)’s UFLPA enforcement has affected respondents’ importation of “Cotton apparel products from China,” “Cotton apparel products from Asian countries other than China,” and “Home textiles from China.”
U.S. fashion companies are actively seeking to diversify their sourcing beyond Asia to mitigate the forced labor risks, particularly regarding cotton products.
#3 There is robust excitement about increasing apparel sourcing from members of the Dominican Republic-Central America Free Trade Agreement (CAFTA-DR).
CAFTA-DR members play a more significant role as an apparel sourcing base this year. Over 80 percent of respondents report sourcing from CAFTA-DR members in 2023, a notable increase from 60 percent in the past few years. Also, nearly 30 percent of respondents placed more than 10 percent of their sourcing orders with CAFTA-DR members this year, a substantial increase from only 19 percent of respondents in 2022 and 10 percent in 2021.
About 40 percent of respondents plan to increase apparel sourcing from CAFTA-DR members over the next two years. Most respondents consider expanding sourcing from CAFTA-DR as part of their overall sourcing diversification strategy.
With U.S. fashion companies actively seeking immediate alternatives to sourcing from China and Asia, respondents emphasize theincreased urgencyof improving textile raw material access to promote further U.S. apparel sourcing from CAFTA-DR members. “Allowing more flexibility in sourcing fabrics and yarns from outside CAFTA-DR” was regarded as the top improvement needed.
#4 US fashion companies demonstrate a solid dedication to expanding their sourcing of clothing made from recycled or other sustainable textile fibers:
Nearly 60 percent of respondents say at least 10 percent of their sourced apparel products already use recycled or other sustainable textile fibers. Another 60 percent of surveyed companies plan to “substantially increase sourcing apparel made from sustainable or recycled textile materials over the next five years.”
Addressing the higher sourcing costs and the low-profit margins are regarded as the top challenge for sourcing clothing using recycled or other sustainable fiber.
About 60 percent of respondents also call for policy support for sourcing clothing using recycled or other sustainable textile materials, such as preferential tariff rates and guidance on sustainability and recycling standards.
#5 Respondents strongly support and emphasize the importance of the early renewal of the African Growth and Opportunity Act (AGOA) and extending the program for at least another ten years.
Respondents sourcing from AGOA members are typically large-scale U.S. fashion brands or retailers (with 1,000+ employees). Generally, these companies treat AGOA as part of their extensive global sourcing network and typically source less than 10 percent of the total sourcing value or volume from the region.
About 40 percent of respondents view AGOA as “essential for my company to source from AGOA members.”
About 60 percent of respondents say the temporary nature of AGOA “has discouraged them from making long-term investments and sourcing commitments in the region.” Many respondents expect to cut sourcing from AGOA members should the agreement is not renewed by June 2024.
About one-third of respondents currently sourcing from AGOA explicitly indicate, “Ethiopia’s loss of AGOA eligibility negatively affects my company’s interest in sourcing from the entire AGOA region.” In comparison, only about 17 percent of respondents say they “have moved sourcing orders from Ethiopia to other AGOA members.
Other topics covered by the report include:
5-year outlook for the U.S. fashion industry, including companies’ hiring plan by key positions
The competitiveness of major apparel sourcing destinations in 2023 regarding sourcing cost, speed to market, flexibility & agility, and compliance risks (assessed by respondents)
Respondents’ qualitative comments on the prospect of sourcing from China and “re-risk”
U.S. fashion companies’ latest social responsibility and sustainability practices related to sourcing
U.S. fashion companies’ trade policy priorities in 2023
Background
This year’s benchmarking study was based on a survey of executives from 30 leading U.S. fashion companies from April to June 2023. The study incorporated a balanced mix of respondents representing various businesses in the U.S. fashion industry. Approximately 73 percent of respondents were self-identified retailers, 60 percent self-identified brands, and 65 percent self-identified importers/wholesalers.
The respondents to the survey included both large U.S. fashion corporations and medium to small companies. Around 77 percent of respondents reported having more than 1,000 employees. And the rest (23 percent) represented medium to small-sized companies with 100-999 employees.
On April 17, 2023, the US International Trade Commission (USITC) released a new report analyzing the trade and economic impact of the African Growth Opportunity Act (AGOA). The report fulfills the investigation request by the US House of Representatives Committee on Ways and Means in January 2022.
The full report is HERE. Below are the key findings regarding the apparel sector:
The African Growth and Opportunity Act (AGOA) matters significantly to Sub-Saharan African countries (SSA)’s apparel exports to the United States
AGOA has been the primary competitive advantage for SSA’s apparel exports to the United States. For example, US apparel imports from AGOA beneficiaries have risen from $953 million in 2001 to $1.4 billion in 2021 (note: up to $1.76 billion in 2022). More than 96.4% of these imports claimed AGOA’s duty-free benefits, including 98.8% utilized the “third-country fabric” provision.
While twenty countries were eligible for AGOA’s apparel provision, over 90% of US apparel imports from AGOA members in 2021 originated in five SSA countries: Kenya (31.5%), Madagascar (19.9%), Lesotho (20.6%), Ethiopia (18.3%), and Mauritius (5.1%).
AGOA benefits appear essential for SSA countries to maintain their apparel exports to the United States. USITC noted that in every case when a country lost AGOA eligibility between 2000 and 2021, there was a noticeable decrease in US apparel imports from that country, such as Rwanda and Madagascar. (note: according to OTEXA’s latest trade data, US apparel imports from Ethiopia, which lost its AGOA eligibility in 2022, dropped by 42% in the first two months of 2023 from a year ago, far worse than a 5.8% decrease of AGOA members as a whole.)
SSA garment manufacturers often find supplying the US apparel market a better fit than Europe, primarily because US brands tend to place orders for higher volume bulk basics, which allows workers to focus on a narrower set of skills.
The impact of AGOA on SSA’s apparel production and exports varied at the country level
Some SSA countries (e.g., Kenya and Lesotho) already had well-established apparel industries when AGOA was implemented in 2000. In contrast, other SSA countries (e.g., Madagascar, Ethiopia, Tanzania, and Ghana) received substantial investments from foreign-owned firms after AGOA was enacted, which helped jumpstart their apparel sectors.
USITC also identified two “unsuccessful” AGOA cases. For example, Mauritius was the largest AGOA beneficiary apparel supplier to the United States in 2000 but has since fallen to the fifth-largest in 2021, largely due to increased labor costs. Likewise, South Africa’s apparel export to the US was negatively affected by its disqualification from the “third-country fabric” provision under AGOA.
AGOA has had a limited impact on building an integrated regional textile and apparel supply chain in SSA
Currently, SSA countries primarily participate in the cut-and-sew operations of apparel based on imported textile raw materials from outside the region (mostly from Asia).
The USITC identified several challenges in building the local textile industry in SSA. For example, building a textile mill typically requires much higher investments (e.g., $200–300 million) than a garment factory (i.e., $25 million). Also, most SSA manufacturers cannot make the various types of yarns and fabrics in demand from U.S. buyers.
The dilemma is not new: Access to textile inputs from sources outside SSA is essential for garment manufacturers in SSA to meet the specifications of US buyers. However, relying on imported textile inputs reduces the incentives for investing in new textile production capabilities in SSA.
The USITC report found Mauritius an exception as it has developed a relatively competitive capability in producing cotton fabrics, which are supplied to garment factories in Madagascar. There is also some collaboration between cotton producers in Tanzania and Uganda and Kenya’s textile manufacturers.
US fashion companies generally see SSA as a promising emerging sourcing destination
Apparel producers in SSA are less established in global apparel value chains than manufacturers in other parts of the world. Therefore, it is not uncommon that fashion brands and retailers “work more directly with SSA apparel manufacturers to ensure product quality, particularly for new or expanding product lines.”
Most SSA garment factories only have cut, make, and trim (CMT) capability and rely on imported textile materials arranged by fashion brands and retailers.
USITC found that US companies increasingly import man-made fiber (MMF) apparel from AGOA members to benefit from greater import duty savings. (note: US tariff rates for MMF apparel were typically higher than those made with natural fibers like cotton. On the other hand, however, it’s worth noting that SSA countries generally have more competitive advantages in producing cotton apparel products than in producing MMF apparel).
SSA countries also have advantages over their Asia competitors. For example, “a shipment takes about 15–18 days to travel from the port in Lomé to the East Coast of the United States. From China or Bangladesh, lead times range from 40–50 days.”
Many fashion brands “have expressed interest in sourcing from greenfield factories with fewer legacy challenges posed by compliance and environmental impacts.”
US fashion companies’ sourcing diversification strategy to avoid risk exposure also contributed to the expansion of their apparel imports from AGOA members.
Uncertainty of AGOA renewals hurt US apparel imports from SSA
Apparel companies typically make sourcing decisions 12–18 months in advance. This practice underscores the importance of renewing AGOA early rather than granting extensions only within two to nine months of expiration, as in the past.
The USITC report mentioned, “Without the assurance of the “third country fabric” provision, many US apparel companies sourced from AGOA beneficiaries reported holding back orders from the region.”
More can be done to leverage SSA’s cotton production better
Cotton growing is widespread across about thirty SSA countries. SSA accounts for about 7 percent of the world’s cotton production, the fifth-largest globally.
However, most SSA cotton is sold to international buyers and exported to Asian mills that process it into yarns and fabrics. In contrast, the consumption of domestic cotton in SSA is limited.
The SSA cotton industry produces high-quality, “sustainable” cotton that can be used in several high-value end products sold globally. However, because of a lack of mechanization, SSA cotton production struggles to increase supply to meet demand.
Also, cotton-growing regions in SSA tend to be poorer and less politically stable than other parts of the region.
Discussion questions:
Based on the blog post and class discussions, how competitive or attractive are AGOA members as apparel-sourcing destinations for US fashion companies, especially compared with suppliers from Asia and the Western Hemisphere?
Based on the blog post, what improvement can be made to make AGOA or any problems that need to be addressed?
Any other thoughts related to the patterns of apparel trade and sourcing based on the blog post?
In March 2023, the Office of the United States Trade Representative (USTR) released its 2024 Fiscal Year Budget report, outlining six major goals and objectives for FY2024. USTR’s FY2024 goals and objectives for textile and apparel are similar to FY2023, but keywords such as “near-shoring” are newly emphasized.
Goal 1: Open Foreign Markets and Combat Unfair Trade
Provide policy guidance and support for international negotiations or initiatives affecting the textile and apparel sector to ensure that the interests of U.S. industry and workers are taken into account and, where possible, to provide new or enhanced export opportunities for U.S. industry. (Note: no change from FY2023)
Conduct reviews of commercial availability petitions regarding textile and apparel products and negotiate corresponding FTA rules of origin changes, where appropriate, in a manner that takes into account market conditions while preserving export opportunities for U.S. producers and employment opportunities for U.S. workers. (Note: no change from FY2023)
Engage relevant trade partners to address regulatory issues potentially affecting the U.S. textile and apparel industry’s market access opportunities. (Note: no change from FY2023)
Continue to engage with CAFTA-DR partner countries to address trade-related issues to optimize inclusive economic opportunities; strengthen trade rules and transparency and address non-tariff trade impediments; provide capacity building in areas such as textile and apparel trade-related regulation and practice on customs, border and market access issues, including agricultural and sanitary and phytosanitary regulations, to avoid barriers to trade. (note: newly mentioned “transparency”)
Continue to engage CAFTA-DR partners and stakeholders to identify and develop means to increase two-way trade in textiles and apparel and strengthen the North American supply chain and near-shoring to enhance formal job creation. (note: newly emphasized “Near-shoring”)
Provide policy guidance and support for international negotiations or initiatives affecting the textile and apparel sector to ensure that the interests of U.S. industry and workers are taken into account and, where possible, to provide new or enhanced export opportunities for U.S. industry. (Note: no change from FY2023)
Conduct reviews of commercial availability petitions regarding textile and apparel products and negotiate corresponding FTA rules of origin changes, where appropriate, in a manner that takes into account market conditions while preserving export opportunities for U.S. producers and employment opportunities for U.S. workers (note: no change from FY2023)
Engage relevant trade partners to address regulatory issues potentially affecting the U.S. textile and apparel industry’s market access opportunities. (note: no change from FY2023)
Goal 2: Fully Enforce U.S. Trade Laws, Monitor Compliance with Agreements, and Use All Available Tools to Hold Other Countries Accountable
Closely collaborate with industry and other offices and Departments to monitor trade actions taken by partner countries on textiles and apparel to ensure that such actions are consistent with trade agreement obligations and do not impede U.S. export opportunities. (note: no change from FY2023)
Research and monitor policy support measures for the textile sector, in particular in the PRC, India, and other large textile producing and exporting countries, to ensure compliance with international agreements. (note: no change from FY2023)
Continue to work with the U.S. textile and apparel industry to promote exports and other opportunities under our free trade agreements and preference programs, by actively engaging with stakeholders and industry associations and participating, as appropriate, in industry trade shows. (note: no change from FY2023)
Goal 4: Develop Equitable Trade Policy Through Inclusive Processes
Take the lead in providing policy advice and assistance in support of any Congressional initiatives to reform or re-examine preference programs that have an impact on the textile and apparel sector. (note: no change from FY2023)
Other Priorities for USTR in FY2024:
#1 “Advancing a Worker-Centered Trade Policy.” For example, given “communities of color and lower socio-economic backgrounds were more negatively affected by free trade policies that have reduced tariffs and distributed supply chains across the globe,” USTR will develop “a new strategic approach to trade relationships that is not built on traditional free trade agreements…USTR is embarking on trade engagements with allies and like-minded economies, like Taiwan and Kenya and [through] multinational economic frameworks that focus on clean energy and supply chains rather than tariffs.”
#2 Address forced labor. For example, USTR developed the first-ever focused trade strategy to combat forced labor. Paired with the implementation of the Uyghur Forced Labor Prevention Act, and the Memorandum of Cooperation (MOC) launching of a Task Force on the Promotion of Human Rights and International Labor Standards in Supply Chains under the U.S.-Japan Partnership on Trade. And USTR will “use every tool available to block the importation of goods made partially or entirely with forced labor.”
#3 Re-Aligning the U.S. – Beijing Trade Relationship. “USTR continues to keep the door open to conversations with the PRC, including on its Phase One commitments. However, USTR acknowledges the Agreement’s limitations. USTR’s strategy is expand beyond only pressing Beijing for change and includes vigorously defending our values and economic interests from the negative impacts of the PRC’s unfair economic policies and practices.”
#4 Strengthen enforcement of US trade policy. For example, USTR sees enforcement “a key component of our worker-centered trade policy.” USTR is “upholding the eligibility requirements in preference programs,” such as the African Growth and Opportunity Act (AGOA). As many enforcement tools were “were crafted decades ago,” USTR will be “reviewing our existing trade tools and working with Congress to develop new tools as needed.”
Elizabeth Davelaar is a Co-Owner of Maker’s Way Fiber Mill in Brandon, SD, which opened in October 2021. The mill is a family-run business, with Elizabeth’s sister, Erin, and her mother, Kari, as other co-owners. Elizabeth began her career in the fashion industry at the University of Minnesota, where she graduated with a BS in Apparel Design from the College of Design. She then went to the University of Delaware, where she graduated with an MS in Fashion and Apparel Studies and a Graduate Certificate in Sustainable Apparel Business.
Elizabeth served as a project manager for a non-profit fashion brand in St. Louis and taught sewing to immigrant women in St. Louis and women in Ethiopia. She then moved to Vi Bella Jewelry in Sioux Center, IA, working her way from Shipping Manager to VP of Operations, Sustainability and Design. She then opened Maker’s Way Fiber Mill in 2021 with her family and has been working with local fiber producers to grow the yarn industry in South Dakota and surrounding areas.
Interview Part
Sheng: What inspired you to start your fiber mill business? What makes it special and exciting?
Elizabeth: The mill was born out of the need to solve a problem. I became interested in natural dye at the University of Delaware under Professor Cobb. Once I moved back to the area where I grew up, COVID hit, and I was able to dive deeper into the natural dye and use local plants as a dye source. This also led to being curious about local natural fibers. South Dakota isn’t a state that grows cotton, and the hemp industry is currently small, but it has an abundance of sheep. According to statistics from the US Department of Agriculture, South Dakota has 235,000 sheep and is home to one of the nation’s largest wool co-ops. However, there are only 2 working fiber mills in the area that provide custom processing, which makes yarn made from local fiber very hard to find.
This led to the opening of Maker’s Way Fiber Mill. We are a full-service, custom fiber mill and make yarn, felt, roving, and home goods products from primarily wool and alpaca fiber. Approximately 90% of our time is spent processing for clients who own the animals and use the yarn themselves or sell it, with the other 10% processing yarn that we sell online via our website and in-person at events. The vast majority of our customers are local (within 4-5 hrs) and sell locally to crafters. We take pride in knowing where the fiber we use comes from, sourcing from local farms or using fiber from vintage or second-hand sources.
Hats made from 80% alpaca/20% Wool (both sourced from SD) with a small amount of recycled sari silk blended in. Photo courtesy of Elizabeth Davelaar
(Photo courtesy of Elizabeth Davelaar)
Photo courtesy of Elizabeth Davelaar
Sheng: According to Maker’s Way Fiber Mill’s website, sustainability is a critical feature of your products. Why is that, and how do you make your products sustainable?
Elizabeth: We believe that we are stewards of the earth and should be conscious of how the products we make are grown, created, and then how they can be disposed of. The fashion industry, from creating the product to end life, is a huge polluter. The current market for wool is not great for producers, and there isn’t a good avenue for alpaca producers. We work very hard to ensure that our products are sourced from people that we know and trust or are from vintage or second-hand sources. We also work to ensure our products are made from natural fibers, thus they are biodegradable.
We also work to limit the waste in our mill. Although we try our absolute best to reduce loss in the process, each step produces some loss in fiber. This fiber is swept up and either rewashed and added to our Millie line or added to our bird nest starters. The Millie line is yarn spun up from the scraps, and we end up running about four batches of this a year. Each batch is unique because of the different blends of fiber we run. The bird nest starters use fiber that either falls out of our carder or is swept off the floor. These are then put outside in the spring for birds to use for nesting. The fibers are short enough that the baby birds don’t get tangled in them as they would with yarn and because they are natural animal fibers, the nests will biodegrade, unlike acrylic yarns that are sometimes used.
Photo courtesy of Elizabeth Davelaar
Sheng: Maker’s Way Fiber Mill’s products are 100% locally made in South Dakota. From your perspective, what are the opportunities and challenges for manufacturing textiles in the US today?
Elizabeth: I see two big challenges in the natural animal fiber side of the U.S. textile industry: Lack of consumer knowledge of where clothing comes from and lack of infrastructure. But both also present big opportunities!
First, we have found with our mill that people don’t have a good understanding of how many steps there are in creating yarn in general, let alone clothing. We have people who question our pricing because they don’t understand what it means to make yarn in the United States. From start to finish, it takes eight different steps to get raw fiber from producers to yarn ready to sell. Our consultations for new clients tend to be very educational because even fiber producers don’t necessarily know all the steps. As we open the mill for tours and talk to people at events, they start to understand and respect how much work is behind the yarn we create, and that is when we see buy-in – when people start to see the whole process, as well as the people.
The second challenge I see is the overall lack of infrastructure. We are one of approximately 200 small-scale / artisan-style mills in the country (this number is approximate – there is not a good database) and do not run near the quantity compared to the larger manufacturers. As of 2018, there aren’t any small-scale fiber mill equipment manufacturers in the US, so all of the equipment available to us is either used or has to be imported from Canada or Italy. Wait time for most small producers to get their fiber made into yarn is approximately 8-12 months at many mills, some run up to 18 months out. Our mill currently runs about 6 months out and we have been open for just over a year.
For producers who want to sell their wool to larger manufacturers and not have it custom processed, as far as our research has shown, there is one large-scale scouring (wool washing) facility in the states and most of the large-scale spinners use fiber from this facility to spin into yarn and then send the fiber off to other finishing companies for knitting. Otherwise, all of the wool is shipped overseas, and producers are earning approximately $1.66/lb of wool (in 2020). We have heard of many producers that have stockpiles of wool because they are waiting for higher wool prices. Coops also won’t accept wool that isn’t white, so all dark colors of wool get thrown away as there isn’t a market for it.
We also see this as an opportunity. We have noticed the “buying local” trend extending past food also to include yarn. People also see value in making their own clothing and being intentional through knitting/crocheting. There is a growing market for it. We have also seen some demand for the addition of another large-scale scouring facility that could meet the needs for wool insulation and other home applications.
Sheng: Like other fashion programs in the US, most of our FASH students take job opportunities from fashion brands and retailers, not necessarily textile mills. How to raise the young generation’s interest in pursuing a career in textile and apparel factories? Do you have any suggestions?
Elizabeth: I definitely never intended to start a fiber mill when I was in school. I only took one textile class and am pretty sure only one of my design projects used wool. UD was really what fed the sustainability bug in me and I started to realize that sustainability starts at the very beginning of the lifecycle of clothing. Whether or not something can be biodegradable, recyclable, or repurposed starts with what fiber makes up the clothing. UD also showed me how global apparel is and how much carbon footprint it makes.
Working in a fiber mill is not an easy job. It is dirty, we tend to put in long days, and we are constantly learning new things. I am a very hands-on person, and I love being able to create things from nothing, so this job is a great fit for me. The part I loved most about being in design school was being able to create things, and my current job is that all day, every day. We split the mill into “zones” and between myself, Erin and our mom, we all specialized in a specific part of the process. I am in charge of skirting and cleaning fleeces, which means cleaning off all of the hay and visibly dirty areas (aka manure) and then washing the fiber in 140-180 degree water to get the dirt and lanolin out of the fleece. I then pick and card the fiber, which opens up and organizes the fiber into a long tube that is then drafted, spun, plied, and put into skeins. While most days tend to include the same things, each day is never the same as the last. Each animal fleece we run acts differently, so we are always learning new and better ways to run the equipment we have. It is challenging but also a labor of love. Because we work directly with producers, we know the names of most of the animals and love knowing that their fleeces are being used instead of being discarded! We also love connecting with local people who love purchasing from local producers and makers.
Photo courtesy of Elizabeth Davelaar
One of the biggest things I believe fashion programs can do to help open up students to different options in the fashion industry is to expose them to different opportunities and allow them to follow whatever passion they have and emphasize that there isn’t a “right” path in the industry. My classes opened me up to labor issues around the world and that then led me to Delaware. And the opportunities I was given at UD to follow my passions are a huge reason I am doing what I am doing now. One of the things I think UD does right is having many different professors with varying backgrounds in the FASH department and I think other universities would do well to implement that too.
Sheng: Any other key issues or industry trends you will watch in 2023?
Elizabeth: One of the key trends we are watching is the local craft movements and knowing where your clothing comes from. We saw a crafting resurgence happen during COVID and people are still pickup up their knitting needles and crochet hooks to create items to wear and love. We also see some carryover of the local food scene into the local fiber scene. We believe that this will continue to grow!
This study was based on a statistical analysis of 3,307 randomly selected clothing items made from recycled textile materials for sale in the U.S. retail market between January 2019 and August 2022 (see the sample picture above). The results show that:
First, U.S. retailers sourced clothing made from recycled textile materials from diverse countries.
Specifically, the sampled clothing items came from as many as 36 countries, including developed and developing economies in Asia, America, the EU, and Africa.
However, reflecting the unique supply chain composition of clothing made from recycled textile materials, U.S. retailers’ sourcing patterns for such products turned out to be quite different from regular new clothing. For example, whereas the vast majority (i.e., over 90%) of U.S. regular new clothing came from developing countries as of 2022 (UNComtrade, 2022), as many as 43% of the sampled clothing items made from recycled textile materials (n=1,408) were sourced from developed countries. Likewise, U.S. retailers seemed to be less dependent on Asia when sourcing clothing made from recycled materials (41.9%, n=1,387) and instead used near-sourcing from America (30.1%, n=994) more often, particularly domestic sourcing from the United States (14.8%, n=490).
Second, U.S. retailers appeared to set differentiated assortments for products imported from developed and developing countries when sourcing clothing made from recycled textile materials.
Among the sampled clothing items made from recycled textile materials, those imported from developing countries, on average, included a broader assortment than developed economies. Likewise, imports from developing countries also concentrated on products relatively more complex to make as opposed to developed countries. Developing countries’ more extensive clothing production capability, including the available production facilities and skilled labor force, than developed economies could have contributed to the pattern.
On the other hand, likely caused by developed countries’ overall higher production costs, the average retail price of sampled clothing items sourced from developed countries was notably higher than those from developing ones. However, NO clear evidence shows that U.S. retailers used developed countries primarily as the sourcing bases for luxury or premium items and used developing countries only for items targeting the mass or value market.
Third, an exporting country’s geographic location was another statistically significant factor affecting U.S. retailers’ sourcing pattern for clothing made from recycled textile materials. Specifically,
Imports from Asia had the most diverse product assortment (e.g., sizing options) and focused on complex product categories (e.g., outwear) that targeted mass and value markets.
Imports from America (North, South, and Central America) concentrated on simple product categories (e.g., T-shirts and hosiery) with moderate assortment diversity and mainly targeted the mass and value market.
Imports from the EU were mainly higher-priced luxury items in medium-sophisticated or sophisticated product categories with diverse assortment.
Imports from Africa concentrated on relatively higher-priced premium or luxury items in simple product categories (i.e., swim shorts) with a limited assortment diversity.
The study’s findings demystified the country of origin of clothing made from recycled textile materials hidden behind macro trade statistics. The findings also created critical new knowledge that contributed to our understanding of the supply chain of clothing made from recycled textile materials and U.S. retailers’ distinct sourcing patterns and affecting factors for such products. The findings have several other important implications:
First, the study’s findings revealed the broad supply base for clothing made from recycled textile materials and suggested promising sourcing opportunities for such products. Whereas existing studies illustrated consumers’ increasing interest in shopping for clothing made from recycled textile materials, the study’s results indicated that the “enthusiasm” also applied to the supply side, with many countries already engaged in making and exporting such products. Meanwhile, the results showed that U.S. retailers sourced clothing made from recycled textile materials in different product categories with a broad price range targeting various market segments to meet consumers’ varying demands. Moreover, as textile recycling techniques continue to advance, potentially enriching the product offer of clothing made from recycled textile materials, U.S. retailers’ sourcing needs and supply base for such products could expand further.
Second, the study’s findings suggest that sourcing clothing made from recycled textile materials may help U.S. retailers achieve business benefits beyond the positive environmental impacts. For example, given the unique supply chain composition and production requirements, China appeared to play a less dominant role as a supplier of clothing made from recycled textile materials for U.S. retailers. Instead, a substantial portion of such products was “Made in the USA” or came from emerging sourcing destinations in America (e.g., El Salvador, Nicaragua) and Africa (e.g., Tunisia and Morocco). In other words, sourcing clothing made from recycled textile materials could help U.S. retailers with several goals they have been trying to achieve, such as reducing dependence on sourcing from China, expanding near sourcing, and diversifying their sourcing base.
Additionally, the study’s findings call for strengthening U.S. domestic apparel manufacturing capability to better serve retailers’ sourcing needs for clothing made from recycled textile materials. On the one hand, the results demonstrated U.S. retailers’ strong interest in sourcing clothing made from recycled textile materials that were “Made in the USA.” Also, the United States may enjoy certain competitive advantages in making such products, ranging from the abundant supply of recycled textile waste and the affordability of expensive modern recycling machinery to the advanced research and product development capability. On the other hand, the results showed that U.S. retailers primarily sourced simple product categories (e.g., T-shirts and hosiery), targeting the value and mass markets from the U.S. and other American countries. This pattern somewhat mirrored the production and sourcing pattern for regular new clothing, for which apparel “Made in the USA” also lacked product variety and focused on basic fashion items compared with Asian and EU suppliers. Thus, strengthening the U.S. domestic apparel production capacity, especially for those complex product categories (e.g., outwear and suits), could encourage more sourcing of “Made in the USA” apparel using recycled textile materials and support production and job creation in the U.S. apparel manufacturing sector.
#1. Are classic trade theories (e.g., comparative advantage) still relevant or outdated in the 21st century? Why? Please share your thoughts based on the video and the figures.
#2. Based on the video and the figures above, is the US textile manufacturing sector a winner or loser of globalization and international trade? Why?
#3. Take the following poll (anonymous) and share your reflections.
#4. Should the government’s trade policy consider non-economic factors such as national security and geopolitics? What should be the line between promoting “fair trade” and “trade protectionism”? What’s your view?
#5. Is there anything else you find interesting/intriguing/thought-provoking in the video? Why?
This article provided a comprehensive review of the world textiles and clothing trade patterns in 2021 based on the newly released data from the World Trade Statistical Review 2022 and the United Nations (UNComtrade). Affected by the ongoing pandemic and companies’ evolving production and sourcing strategies in response to the shifting business environment, the world textiles and clothing trade patterns in 2021 included both continuities and new trends. Specifically:
Pattern #1: As the world economy recovered from COVID, the world clothing export boomed in 2021, while the world textile exports grew much slower due to a high trade volume the year before. Specifically, thanks to consumers’ strong demand, world clothing exports in 2021 fully bounced back to the pre-COVID level and exceeded $548.8bn, a substantial increase of 21.9% from 2020. The apparel sector is not alone. With economic activities mostly resumed, the world merchandise trade in 2021 also jumped 26.5% from a year ago, the fastest growth in decades.
In comparison, the value of world textiles exports grew slower at 7.8% in 2021 (i.e., reached $354.2bn), lagging behind most sectors. However, such a pattern was understandable as the textile trade maintained a high level in 2020, driven by high demand for personal protective equipment (PPE) during the pandemic.
Nevertheless, the world textiles and clothing trade could face strong headwinds down the road due to a slowing world economy and consumers’ weakened demand. Notably, amid hiking inflation, high energy costs, and retrenchment of global supply chains, leading international economic agencies, from the World Bank to the International Monetary Fund (IMF), unanimously predict a slowing economy worldwide. Likewise, the World Trade Organization (WTO) forecasts that the growth of world merchandise trade will be cut to 3.5% in 2022 and down further to only 1% in 2023. As a result, the world textiles and clothing trade will likely struggle with stagnant growth or a modest decline over the next two years.
Pattern #2: COVID did NOT fundamentally shift the competitive landscape of textile exports but affected the export product structure. Meanwhile, some long-term structural changes in world textile exports continued in 2021.
Specifically, China, the European Union (EU), and India remained the world’s three largest textile exporters in 2021, a pattern that has stayed stable for over a decade. Together, these top three accounted for 68% of the world’s textile exports in 2021, similar to 66.9% before the pandemic (2018-2019). Other textile exporters that made it to the top ten list in 2021 were also the same as a year ago and before the pandemic (2018-2019).
Meanwhile, the growth rate of the top ten textile exporters varied significantly in 2021, ranging from -5.5% (China) to 47.8% (India). The demand shift from PPE to apparel-related yarns and fabrics was a critical contributing factor behind the phenomenon. For example, China’s PPE-related textile exports decreased by more than $33bn (or down 43%) in 2021. In contrast, the world knit fabric exports (SITC code 655) surged by more than 30% in 2021, led by India (up 74%) and Pakistan (up 72%). Nevertheless, as consumers’ lifestyles almost reached a “new normal,” we could expect the textile export product structure to stabilize soon.
On the other hand, as a trend already emerged before the pandemic, middle-income developing countries continued to play a more significant role in textile exports, whereas developed countries lost market shares. For example, the United States, Germany, and Italy led the world’s textile exports in the 2000s, accounting for more than 20% of the market shares. However, these three countries’ shares fell to 12.8% in 2019 and hit a new low of 11.3% in 2021. In comparison, middle-income developing countries like China, Vietnam, Turkey, and India have entered the development stage of expanding textile manufacturing. As a result, their market share in the world’s textile exports rose steadily. These countries also achieved a more balanced textiles/clothing export ratio over the years, meaning more textile raw materials like yarns and fabrics can be locally produced instead of relying on imports. For example, Vietnam, known for its competitive clothing products, achieved a new high of $11.5bn in textile exports in 2021 and ranked sixth globally. Vietnam’s textiles/clothing ratio also doubled from 0.15 in 2005 to 0.37 in 2021. It is not unlikely that Vietnam’s textile exports may surpass the United States over the next few years.
Pattern #3: Countries with large-scale production capacity stood out in world clothing exports in 2021. Meanwhile, clothing exporters compete to become China’s alternatives, but there seems to be no clear winner yet.
Consumers’ surging demand and COVID-related supply chain disruptions significantly impacted the world’s clothing export patterns in 2021. As fashion brands and retailers were eager to find sourcing capacity, countries with large-scale production capacity and relatively stable supply enjoyed the fastest growth in clothing exports. For example, except for Vietnam, which suffered several months of COVID lockdowns, all other top five clothing exporters enjoyed a more than 20% growth of their exports in 2021, such as China (up 24%), Bangladesh (up 30%), Turkey (up 22%), and India (up 24%).
As another critical trend, many international fashion brands and retailers have been trying to reduce their apparel sourcing from China, driven by various economic and non-economic factors, from cost considerations and trade tensions to geopolitics. Notably, despite its strong performance in 2021, China accounted for only 23.1% of US apparel imports in 2022 (January to September), much lower than 36.2% in 2015. Likewise, China’s market shares in the EU, Japanese, and Canadian clothing import markets also fell over the same period, suggesting this was a worldwide phenomenon.
With reduced apparel sourcing from China, fashion companies have actively sought alternative sourcing destinations, but the latest trade data suggests no clear winner yet. For example, Vietnam and Bangladesh, the two most popular candidates for “Next China,” accounted for 6.5% and 5.7% shares in the world’s clothing export in 2021, still far behind China (32.1%). Interestingly, from 2015 to 2021, the world’s top four largest clothing exporters next to China (i.e., Bangladesh, Vietnam, Turkey, and India) did not substantially gain new market shares. Instead, China’s lost market was filled by “the rest of the world.”
Additionally, recent studies show that many fashion companies have switched back to the sourcing diversification strategy in 2022 as managing risks and improving sourcing flexibility become more urgent priorities. In other words, the world’s clothing export market could turn more “crowded” and competitive in the coming years.
Pattern #4: Regional supply chains remain critical features of the world textiles and clothing trade. Several factors support and shape the regional textiles and clothing trade patterns. First, as clothing production often needs to be close to where textile materials are available, many developing clothing-producing countries rely heavily on imported textile materials, primarily from more advanced economies in the same region. Second, through lowered trade barriers, regional free trade agreements also financially encouraged garment producers, particularly in Asia, the EU, and Western Hemisphere (WH), to use locally or regionally made textile materials. Further, fashion companies’ interest in “near-shoring” supported the regional supply chain, and related textiles and clothing trade flows between neighboring countries.
The latest trade data indicated that Asia’s regional textiles and clothing trade patterns strengthened further despite supply chain chaos during the pandemic. Specifically, in 2021, as many as 82% of Asian countries’ textile imports came from within Asia, up from 80% in 2015. China, in particular, has played a more prominent role as a leading textile supplier for other Asian clothing-exporting countries. For example, more than 60% of Vietnam’s textile imports came from China in 2021, a substantial increase from 23% in 2005. The same pattern applied to Pakistan, Cambodia, Bangladesh, and the Association of Southeast Asian Nations (ASEAN) members.
In January 2022, the Regional Comprehensive Economic Partnership (RCEP), a mega free trade agreement involving all major economies in Asia, entered into force. The tariff cut and very liberal rules of origin of the agreement will hopefully drive Asia’s booming regional textiles and clothing trade and further deepen its regional economic integration.
Besides Asia, the regional textiles and clothing trade pattern in the EU (or the so-called Intra-EU trade) was also in good shape. In 2021, 50.8% of EU countries’ textile imports and 37% of clothing imports came from other EU members. This pattern has changed little over the past decade, thanks to many EU countries’ commitment to maintaining local textiles and clothing production rather than outsourcing.
In comparison, the Western Hemisphere (WH) textile and apparel supply chain (e.g., clothing made in Mexico or Central America using US or regionally made textiles) seemed to struggle in recent years. As of 2021, only 20% of WH countries’ textile imports came from within WH, down from 26% in 2015. Likewise, WH countries (mainly the US and Canada) just imported 14.6% of clothing from WH in 2021, down from 15.3% in 2015 and much lower than their EU counterparts (37% in 2021). It will be interesting to see whether US and Canadian fashion companies’ expressed interest in expanding near-shoring may reverse the course.
Furthermore, the regional textiles and clothing trade patterns in Sub-Saharan Africa (SSA) are also worth watching. Compared with Asia and the EU, SSA clothing producers used much fewer locally-made textiles (i.e., stagnant at around 11% only from 2011 to 2021), reflecting the region’s lack of textile manufacturing capability. Most trade programs with SSA countries, such as the US-led African Growth and Opportunity Act (AGOA) and EU’s Everything But Arms (EBA) program, adopt liberal rules of origin for clothing products, allowing third-party textile input to be used. It can be studied whether such liberal rules of origin somehow disincentivize building SSA’s own textile manufacturing sector or are still essential given the reality of SSA’s limited textile production capacity.
This study offers valuable input and practical policy recommendations from U.S. apparel companies’ perspectives regarding expanding U.S. apparel sourcing from CAFTA-DR members. For the study, we consulted executives at 27 leading U.S.-based apparel companies (note: 85% report having annual revenues exceeding $500 million; over 95% have been sourcing apparel from the CAFTA-DR region for more than ten years).
The results confirm that expanding U.S. apparel sourcing from CAFTA-DR could be the best chance to effectively create more jobs in Central America and solve the root causes of migration there. To achieve this goal, we need to focus on four areas:
First, improve CAFTA-DR’s apparel production capacity and diversify its product offers.
As many as 92 percent of respondents report currently sourcing apparel from CAFTA-DR members.
Highly consistent with the macro trade statistics, the vast majority of respondents (i.e., 60 percent) place less than 10 percent of their company’s total sourcing orders with CAFTA-DR members.
Whereas respondents rate CAFTA-DR members overall competitive in terms of “speed to market,” they express concerns about CAFTA-DR countries’ limited production capacity in making various products. As a result, U.S. companies primarily source basic fashion items like T-shirts and sweaters from the region. These products also face growing price competition with many alternative sourcing destinations.
Improving CAFTA-DR’s production capacity and diversifying product offers would encourage U.S. apparel companies to move more sourcing orders from Asia to the region permanently.
Second, practically solve the bottleneck of limited textile raw material supply within CAFTA-DR and do NOT worsen the problem.
The limited textile raw material supply within CAFTA-DR is a primary contributing factor behind the region’s stagnated apparel export volume and a lack of product diversification.
Notably, respondents say for their apparel imports from CAFTA-DR members, only 42.9% of fabrics, 40.0% of sewing threads, and 23.8% of accessories (such as trims and labels) can be sourced from within the CAFTA-DR area (including the United States). CAFTA-DR’s textile raw material supply problem could worsen as the U.S. textile industry switches to making more technical textiles and less so for apparel-related fabrics and textile accessories.
Maintaining the status quo or simply calling for making the CAFTA-DR apparel supply chain more “vertical” will NOT automatically increase the sourcing volume. Instead, allowing CAFTA-DR garment producers to access needed textile raw materials at a competitive price will be essential to encourage more U.S. apparel sourcing from the region.
Third, encourage more utilization of CAFTA-DR for apparel sourcing.
CAFTA-DR plays a critical role in promoting U.S. apparel sourcing from the region. Nearly 90 percent of respondents say the duty-free benefits provided by CAFTA-DR encourage their apparel sourcing from the region.
The limited textile supply within CAFTA-DR, especially fabrics and textile accessories, often makes it impossible for U.S. companies to source apparel from the region while fully complying with the strict “yarn-forward” rules of origin. As a result, consistent with the official trade statistics, around 31 percent of respondents say they sometimes have to forgo the CAFTA-DR duty-free benefits when sourcing from the region.
Respondents say the exceptions to the “yarn-forward” rules of origin, including “short supply,” “cumulation,” and “cut and assemble” rules, provide necessary flexibilities supporting respondents’ apparel sourcing from CAFTA-DR members. Around one-third of respondents utilize at least one of these three exceptions when sourcing from CAFTA-DR members when the products are short of meeting the strict “yarn-forward” rules of origin. It is misleading to call these exceptions “loopholes.”
Fourth, leverage expanded apparel sourcing to incentivize more investments in the CAFTA-DR region’s production and infrastructure.
U.S. apparel companies are interested in investing in CAFTA-DR to strengthen the region’s sourcing and production capacity. Nearly half of respondents explicitly say they will make investments, including “building factories or expanding sourcing or manufacturing capacities” in the CAFTA-DR region through 2026.
CAFTA-DR will be better positioned to attract long-term investments in its textile and apparel industry with a sound and expanded apparel sourcing volume.
In February and March of 2022, the Office of the United States Trade Representative (USTR) organized and hosted a series of four webinars on CAFTA-DR trade in textiles and apparel. The objective was to enhance stakeholder understanding of the textile and apparel provisions of CAFTA-DR and identify opportunities for increasing and diversifying two-way trade between the United States and CAFTA-DR partner countries.
Webinar 1: Trends and Opportunities in CAFTA-DR Textile and Apparel Trade
Webinar 2: Making Use of CAFTA-DR’s Rules of Origin for Apparel
Webinar 3: The CAFTA-DR Short Supply Mechanism: What It Is and How To Use It
Webinar 4: Understanding Customs Claims and Customs Verifications in CAFTA-DR
Note: According to the 2022 USFIA Fashion Industry Benchmarking Study, US fashion companies demonstrate new excitement about increasing apparel sourcing from members of the Dominican Republic-Central America Free Trade Agreement (CAFTA-DR). More than 60 percent of respondents plan to increase apparel sourcing from CAFTA-DR members as part of their sourcing diversification strategy.
Respondents also say the exceptions to the “yarn-forward” rules of origin, such as the “short supply” and “cumulation” mechanisms, provide essential flexibility that encourages more apparel sourcing from CAFTA-DR members.
However, U.S. apparel sourcing from CAFTA-DR has yet to achieve its full potential. For example, measured in value, only 10.2% of US apparel imports came from CAFTA-DR members in May 2022 (and 9.7% year to date), almost no change from 10.6% in 2021. Meanwhile, the CAFTA-DR utilization rate for apparel imports was stagnant at about 75%-80% since 2015, meaning 20-26 percent of U.S. apparel imports from CAFTA-DR members did NOT claim preferential duty benefits every year.
In April 2022, the Office of the United States Trade Representative (USTR) released its 2023 Fiscal Year Budget report, outlining five goals and objectives for 2023. Notably, textile and apparel is a key sector USTR plans to focus on in the coming year:
Goal 1: Open Foreign Markets and Combat Unfair Trade
Provide policy guidance and support for international negotiations or initiatives affecting the textile and apparel sector to ensure that the interests of U.S. industry and workers are taken into account and, where possible, to provide new or enhanced export opportunities for U.S. industry.
Conduct reviews of commercial availability petitions regarding textile and apparel products and negotiate corresponding FTA rules of origin changes, where appropriate, in a manner that takes into account market conditions while preserving export opportunities for U.S. producers and employment opportunities for U.S. workers.
Engage relevant trade partners to address regulatory issues potentially affecting the U.S. textile and apparel industry’s market access opportunities.
Continue to engage under CAFTA-DR working groups and committees to optimize inclusive economic opportunities; strengthen the agreement and address non-tariff trade impediments; provide capacity building in textile and apparel trade-related regulation and practice on customs, border and market access issues, including agriculture and sanitary and phytosanitary regulation, to avoid barriers to trade.
Continue to engage CAFTA-DR partners and stakeholders to identify and develop means to increase two-way trade in textiles and apparel and strengthen the North American supply chain to enhance formal job creation.
Goal 2: Fully Enforce U.S. Trade Laws, Monitor Compliance with Agreements, and Use All Available Tools to Hold Other Countries Accountable
Closely collaborate with industry and other offices and Departments to monitor trade actions taken by partner countries on textiles and apparel to ensure that such actions are consistent with trade agreement obligations and do not impede U.S. export opportunities.
Research and monitor policy support measures for the textile sector, in particular in China, India, and other large textile producing and exporting countries, to ensure compliance with international agreements.
Continue to work with the U.S. textile and apparel industry to promote exports and other opportunities under our free trade agreements and preference programs, by actively engaging with stakeholders and industry associations and participating, as appropriate, in industry trade shows.
Goal 4: Develop Equitable Trade Policy Through Inclusive Processes
Take the lead in providing policy advice and assistance in support of any Congressional initiatives to reform or re-examine preference programs that have an impact on the textile and apparel sector.
The full study is available here(need Just-Style subscription)
By leveraging production and trade statistics from government databases, we examined the critical trends of US textile manufacturing and supply. Particularly, we try to understand the strengths and weaknesses of the United States as a textile raw material supplier for domestic garment manufacturers and those in the Western Hemisphere. Below are the key findings:
First, fiber, yarn, and thread manufacturing is a long-time strength in the US, whereas fabric production is much smaller in scale. Specifically, fiber, yarn, and thread (NAICS 31311) accounted for nearly 18% of US textile mills’ total output in 2019. In comparison, less than 13% of the production went to woven fabrics (NAICS 31321) and only about 5% for knit fabrics (NAICS 31324).
Second, the US textile industry shifts to make more technical textiles and less apparel-related yarns, fabrics, and other raw materials. Data shows that from 2015 to 2019, the value of US fiber, yarn, and thread manufacturing (NAICS code 31311) dropped by as much as 16.8 percent. Likewise, US broadwoven fabric manufacturing (NAICS code 31321) and knit fabric (NAICS code 31324) decreased by 2.0 percent and 2.7 percent over the same period. Labor cost, material cost, and capital expenditure are critical factors behind the structural shift of US textile manufacturing.
Third, the structural change of US textile manufacturing directly affects the role of the US serving as a textile supplier for domestic apparel producers and those in the Western Hemisphere.
On the one hand, the US remains a critical yarns and threads supplier in the Western Hemisphere. For example, from 2010 to 2019, the value of US fibers, yarn and threads exports (NAICS31311) increased by 25%, much higher than other textile categories. Likewise, in 2021, fibers, yarns, and threads accounted for about 23.3% of US textile exports, higher than 21.0% in 2010. Additionally, nearly 40% of Mexico and CAFTA-DR members’ yarn imports in 2021 (SITC 651) still came from the US, the single largest source. This trend has stayed stable over the past decade.
On the other hand, the US couldn’t sufficiently supply fabrics and other textile accessories for garment producers in the Western Hemisphere, and the problem seems to worsen. Corresponding to the decline in manufacturing, US broadwoven fabric (NAICS 31321) and knit fabric (NAICS 31324) exports decreased substantially.
The US also plays a declining role as a fabric and textile accessories supplier for garment factories in the Western Hemisphere. Garment producers in Mexico and CAFTA-DR members had to source 60%-80% of woven fabrics and 75-82% of knit fabrics from non-US sources in 2021. Likewise, only 40% and 14.6% of Mexico and CAFTA-DR members’ textile accessories, such as labels and trims, came from the US in 2021.
Likewise, the limited US fabric supply affects the raw material sourcing of domestic apparel manufacturers. For example, according to the “Made in the USA” database managed by the Office of Textiles and Apparel (OTEXA), around 36% of US-based apparel mills explicitly say they use “imported material,” primarily fabrics.
The study’s findings echo some previous studies suggesting that textile raw material supply, especially fabrics and textile accessories, could be the single most significant bottleneck preventing more apparel “Made in the USA” and near-sourcing from the Western Hemisphere.
Meanwhile, how to overcome the bottleneck could trigger heated public policy debate. For example, US policymakers could encourage an expansion of domestic fabric and textile accessories manufacturing as one option. However, to make it happen takes time and requires substantial new investments. Also, economic factors may continue to favor technical textiles production over apparel-related fabrics in the US.
As an alternative, US policymakers could make it easier for garment producers in the Western Hemisphere to access their needed fabrics and textile accessories outside the US, such as improving the rules of origin flexibility in CAFTA-DR or USMCA. But this option is likely to face strong opposition from US yarn producers and be politically challenging to implement.
(About the authors: Dr Sheng Lu is an associate professor in fashion and apparel studies at the University of Delaware; Anna Matteson is a research assistant in fashion and apparel studies at the University of Delaware).
#1: As of June 2021, US textile production had resumed about 98.8% of its production capacity at the pre-COVID level. Based on the readings, why or why not do you think the industry is already “out of the woods”? How to understand the impact of COVID-19 on the international competitiveness of US textile production?
#2: To which extent do you think the state of the US textile and apparel industry and its performance during the pandemic challenge the conclusions of the classic trade and economic development theories we learned in the class (e.g., comparative advantage, factor proportion, the international division of labor, and stage of development theories)? Do you find any trade or production patterns that existing theories cannot fully explain?
#3 Many US fashion companies’ strategies to “consolidate existing sourcing base and strengthen the relationship with key vendors” during the pandemic. What is your evaluation of this strategy—is it a short-term reaction toward COVID-19 or a long-term trend likely to stay? What does this strategy mean for vendors in the apparel supplying countries?
#4: What are the notable changes in fashion companies’ sourcing criteria during the pandemic? How to explain such changes? Who are the winners and losers? Why?
#5: It is of concern that sustainability and social responsibility become a lower priority for the apparel industry during the pandemic, given the unprecedented operational and financial challenges companies face. What is your assessment based on the readings?
#6: What is your vision for the US textile and apparel industry in the post-COVID world? What are the key issues/questions/development trends we shall watch?
(Welcome to our online discussion. For students in FASH455, please address at least two questions and mention the question number (#) in your reply)
As one breaking news, on 16 September 2021, China officially presented its application to join the 11-member Comprehensive and Progressive Agreement for Trans-Pacific Partnership (CPTPP). While the approval of China’s membership in CPTPP remains a long shot and won’t happen anytime soon, the debate on the potential impact of China’s accession to the trade agreement already starts to heat up.
Like many other sectors, textile and apparel companies are on the alert. Notably, China plus current CPTPP members accounted for nearly half of the world’s textile and apparel exports in 2020. Many non-CPTPP countries are also critical stakeholders of China’s membership in the agreement. In particular, the Western Hemisphere textile and apparel supply chain, which involves the US textile industry, could face unrepresented challenges once China joins CPTPP.
First, once China joins CPTPP, the tariff cut could provide strong financial incentives for Mexico and Canada to use more Chinese textiles. China is already a leading textile supplier for many CPTPP members. In 2019, as much as 47.7% of CPTPP countries’ textile imports (i.e., yarns, fabrics, and accessories) came from China, far more than the United States (12.1%), the other leading textile exporter in the region.
Notably, thanks to the Western Hemisphere supply chain and the US-Mexico-Canada Trade Agreement (USMCA, previously NAFTA), the United States remains the largest textile supplier for Mexico (48.2%) and Canada (37.2%). Mexico and Canada also serve as the largest export market for US textile producers, accounting for as many as 46.4% of total US yarn and fabric exports in 2020.
However, US textile exporters face growing competition from China, offering more choices of textile products at a more competitive price (e.g., knitted fabrics and man-made fiber woven fabrics). From 2005 to 2019, US textile suppliers lost nearly 20 percentage points of market shares in Mexico and Canada, equivalent to what China gained in these two markets over the same period.
Further, China’s membership in CPTPP means its textile exports to Mexico and Canada could eventually enjoy duty-free market access. The significant tariff cut (e.g., from 9.8% to zero in Mexico) could make Chinese textiles even more price-competitive and less so for US products. This also means the US textile industry could lose its most critical export market in Mexico and Canada even if the Biden administration stays away from the agreement.
Second, if both China and the US become CPTPP members, the situation would be even worse for the US textile industry. In such a case, even the most restrictive rules of origin would NOT prevent Mexico and Canada from using more textiles from China and then export the finished garments to the US duty-free. Considering its heavy reliance on exporting to Mexico and Canada, this will be a devastating scenario for the US textile industry.
Even worse, the US textile exports to CAFTA-DR members, another critical export market, would drop significantly when China and the US became CPTPP members. Under the so-called Western-Hemisphere textile and apparel supply chain, how much textiles (i.e., yarns and fabrics) US exports to CAFTA-DR countries depends on how much garments CAFTA-DR members can export to the US. In comparison, US apparel imports from Asia mostly use Asian-made textiles. For example, as a developing country, Vietnam relies on imported yarns and fabrics for its apparel production. However, over 97% of Vietnam’s textile imports come from Asian countries, led by China (57.1%), South Korea, Taiwan, and Japan (about 25%), as opposed to less than 1% from the United States.
The US textile industry also deeply worries about Vietnam becoming a more competitive apparel exporter with the help of China under CPTPP. Notably, among the CPTPP members, Vietnam is already the second-largest apparel exporter to the United States, next only to China. Despite the high tariff rate, the value of US apparel imports from Vietnam increased by 131% between 2010 and 2020, much higher than 17% of the world average. Vietnam’s US apparel import market shares quickly increased from only 7.6% in 2010 to 16.6% in 2020 (and reached 19.3% in the first half of 2021). The lowered non-tariff and investment barriers provided by CPTPP could encourage more Chinese investments to come to Vietnam and further strengthen Vietnam’s competitiveness in apparel exports.
Understandably, when apparel exports from China and Vietnam became more price-competitive thanks to their CPTPP memberships, more sourcing orders could be moved away from CAFTA-DR countries, resulting in their declined demand for US textiles. Notably, a substantial portion of US apparel imports from CAFTA-DR countries focuses on relatively simple products like T-shirts, polo shirts, and trousers, which primarily compete on price. Losing both the USMCA and CAFTA-DR export markets, which currently account for nearly 70% of total US yarns and fabrics exports, could directly threaten the survival of the US textile industry.
According to the World Trade Statistical Review 2021 report released by the World Trade Organization (WTO), the textiles and apparel trade patterns in 2020 include both continuities and new trends affected by the pandemic and companies’ evolving production and sourcing strategies in response to the shifting business environment.
Pattern #1: COVID-19 significantly affected the world textile and apparel trade volumes, resulting in substantial growth of textile exports and a declined demand for apparel.
Driven by increased personal protective equipment (PPE) production, global textile exports grew by 16.1% in 2020, reaching $353bn. In comparison, affected by lockdown measures, worsened economy, and consumers’ tighter budget for discretionary spending, global apparel export decreased by nearly 9% in 2020, totaling $448bn, the worst performance in decades. The apparel sector is not alone. The world merchandise trade in 2020 also suffered an unprecedented 8% drop from a year ago, with COVID-19 to blame.
Notably, as economic activities returned in the second half of 2020, the world clothing export quickly rebounded to around 95% of the pre-covid level by the end of 2020. That being said, the unexpected resurgence of COVID cases in summer 2021, especially the delta variant, caused new market uncertainties. Overall, the world textile and apparel trade recovery process from COVID-19 will differ from our experiences during the 2008 global financial crisis.
Pattern #2: COVID-19 did NOT shift the competitive landscape of the world textile exports; Meanwhile, textile exports from China and Vietnam gained new momentum during the pandemic.
China, the European Union (EU), and India remained the world’s three largest textile exporters in 2020. Together, these top three accounted for 65.8% of the world’s textile exports in 2020, similar to 66.9% before the pandemic (2018-2019).
Notably, China and Vietnam enjoyed a substantial increase in their textile exports in 2020, up 28.9% and 10.7% from a year ago, respectively. The complete textile and apparel supply chain and considerable production capability allow these two countries to switch clothing production to PPE manufacturing quickly. In particular, Vietnamexceeded South Korea and ranked the world’s sixth-largest textile exporter in 2020 ($10 bn of exports), the first time in history.
The United States dropped one place and ranked the world’s fifth-largest textile exporter in 2020 (was 4th from 2015 to 2019), accounting for 3.2% of the shares (was 4.4% in 2019). Production disruptions at the beginning of the pandemic and the shift toward PPE production for domestic consumption were the two primary contributing factors behind the decline in U.S. textile exports. Due to the regional trade patterns, around 67% of U.S. textile exports went to the Western Hemisphere in 2020, including 46% for members of the U.S.-Mexico-Canada Trade Agreement (USMCA) and another 17.2% for members of the Dominican Republic-Central America Free Trade Agreement (CAFTA-DR).
Pattern #3: Fashion companies’ efforts to diversify apparel sourcing from China somehow slowed during the pandemic.
China, the European Union, Vietnam, and Bangladesh unshakably remained the world’s four largest apparel exporters in 2020. Altogether, these top four accounted for 72.2% of the world market shares in 2020, higher than 71.4% in 2019.
Notably, while China steadily accounted for declining shares in the world’s total apparel exports since 2015, its market shares rebounded to 31.6% in 2020 from 30.7% in 2019. We can observe a similar pattern in Canada (up from 36.2% to 41.2%) and the EU (31.2% to 31.3%), two of the world’s leading apparel import markets. Even in the U.S. market, where Chinese goods face adverse impacts of the tariff war, the market shares of “Made in China” only marginally decreased from 30.8% in 2019 to 29.8% in 2020, compared with a more significant drop before the pandemic (i.e., fell from 34.4% 2018 to 30.8% in 2019).
Several factors could explain the resilience of China’s apparel exports: 1) fashion brands and retailers’ particular sourcing criteria match China’s competitiveness during the pandemic (e.g., flexibility, agility, and total landed sourcing cost). 2) China has one of the world’s most complete textile and apparel supply chains, allowing garment factories to access textile raw material and accessories locally. 3) Compared with many other apparel exporting countries, China suffered a shorter COVID lockdown period and resumed apparel production earlier and more quickly. Most Chinese textile and apparel factories started to reopen in April 2020, and they resumed an overall 90%-95% operational capacity rate by July 2020.
Nonetheless, fashion companies are NOT reversing their long-term strategies to reduce “China exposure” for apparel sourcing. On the contrary, non-economic factors, particularly the concerns about forced labor in China’s Xinjiang region, push most western fashion brands and retailers to develop apparel sourcing capacities beyond China. Meanwhile, no single country has yet and will likely become the “Next China” because of capacity limits. Instead, from 2015 to 2020, China’s lost market shares in the world apparel exports (around 7.8 percentage points) were picked up jointly by its competitors in Asia, including ASEAN members (up 4.4 percentage points), Bangladesh (up 1.3 percentage points), and Pakistan (up 0.3 percentage point). Such a trend is most likely to continue in the post-COVID world.
Pattern #4: Developed economies led textile PPE imports during the pandemic, whereas the developing countries imported fewer textiles as their apparel exports dropped.
On the one hand, the value of textile imports by developed economies, including EU members, the United States, Japan, and Canada, surged by more than 30 percent in 2020, driven mainly by their demand for PPE. The result also reveals the significant contribution of international trade in supporting the supply and distribution of textile PPE globally. On the other hand, the developing countries engaged in apparel production and export drove the import demand for textile raw materials like yarns and fabrics. However, most of these developing countries’ textile imports fell in 2020, corresponding to their decreased apparel exports during the pandemic.
Pattern #5: Despite COVID-19, the world apparel import market continues to diversify. The import demand increasingly comes from emerging economies with a booming middle class.
Affected by consumers’ purchasing power (often measured by GDP per capita) and the size of the population, the European Union, the United States, and Japan remained the world’s three largest apparel importers in 2020, a stable pattern that has lasted for decades. While these top three still absorbed 56.2% of the world’s apparel imports in 2020, it was a new record low in the past ten years (was 58.1% in 2019 and 61.5% in 2018), and much lower than 84% back in 2005.
Behind the numbers, it is not the case that consumers in the EU, the United States, and Japan necessarily purchase less clothing over the years. Instead, several emerging economies have become fast-growing apparel-consuming markets with robust import demand. For example, despite COVID-19, China’s apparel imports totaled $9.5bn in 2020, up 6.5% from 2019. From 2010 to 2020, China’s apparel imports enjoyed a nearly 15% annual growth, compared with only 0.56% of the traditional top three. Around 30% of China’s apparel imports today are luxury items made in the EU.
Within the Western-Hemisphere (WH) textile and apparel supply chain, the United States serves as the leading textile supplier, whereas developing countries in North, Central, and South America (such as Mexico and countries in the Caribbean region) assemble imported textiles from the United States or elsewhere into apparel. The majority of clothing produced in the area is eventually exported to the United States or Canada.
WH countries still form a close supply chain partnership in textile and apparel production. For example, close to 70% of US textile exports went to WH members in 2020, a pattern that has stayed stable over the past decades (OTEXA, 2021). Meanwhile, the United States serves as the single largest export market for most apparel exporting countries in the WH For example, in 2019, close to 89% of apparel exports from CAFTA-DR and USMCA (NAFTA) members went to the US.
However, the WH textile and apparel supply chain is not without significant challenges. For example, CAFTA-DR and Mexico are increasingly using textiles inputs from outside the WH region, which weakens the US role as a dominant textile supplier. Notably, most of the market shares lost by US textile suppliers are fulfilled by Asian countries, including China and other members of the RCEP (Regional Comprehensive Economic Partnership). Theoretically, using cheaper textile inputs from Asia may help apparel producing countries in the WH improve the price competitiveness of their finished garments and diversify their export markets beyond the US.
Meanwhile, despite the apparent popularity of “near-sourcing”, no evidence suggests that US fashion brands and retailers are sourcing more from WH countries, including CAFTA-DR and USMCA (NAFTA) members. Neither the US-China trade war nor COVID-19 seems to have shifted the trends. Instead, close to 75%-80% of US apparel imports still come from Asian countries (OTEXA, 2021). Studies further show that a vast majority of US apparel imports from WH concentrate on a limited category of products, such as tops and bottoms, which is far from sufficient to meet retailers’ sourcing needs.
On the other hand, technical textiles and industrial textiles account for a growing share in the total US textile exports, and Asia is a particularly fast-growing market. However, there is few US free trade agreement with Asian countries, making it a disadvantage to promote “Made in the USA” products in these markets. It is debatable what should be the priority for the US textile and apparel trade policy: to continue to protect the exports of yarn and fabrics to the WH or open new export markets for technical and industrial textiles outside the WH region?
The EU region as a whole remains one of the world’s leading producers of textile and apparel (T&A). The value of EU’s T&A production totaled EUR137.3 bn in 2019, down around 2% from a year ago (Note: Statistical Classification of Economic Activities or NACE, sectors C13, and C14). The value of EU’s T&A output was divided almost equally between textile manufacturing (EUR68.7bn) and apparel manufacturing (EUR68.6bn).
Regarding textile production, Southern and Western EU, where most developed EU members are located such as Germany, France, and Italy, accounted for nearly 75% of EU’s textile manufacturing in 2019. Further, of EU countries’ total textile output, the share of non-woven and other technical textile products (NACE sectors C1395 and C1396) has increased from 19.2% in 2011 to 23.0% in 2017, which reflects the on-going structural change of the sector.
Apparel manufacturing in the EU includes two primary categories: one is the medium-priced products for consumption in the mass market, which are produced primarily by developing countries in Eastern and Southern Europe, such as Poland, Hungary, and Romania, where cheap labor is relatively abundant. The other category is the high-end luxury apparel produced by developed Western EU countries, such as Italy, UK, France, and Germany.
It is also interesting to note that in Western EU countries, labor only accounted for 21.7% of the total apparel production cost in 2017, which was substantially lower than 30.1% back in 2006. This change suggests that apparel manufacturing is becoming capital and technology-intensive in some developed Western EU countries—as companies are actively adopting automation technology in garment production.
Because of their relatively high GDP per capita and size of the population, Germany, Italy, UK, France, and Spain accounted for nearly 60% of total apparel retail sales in the EU in 2020. Such a market structure has stayed stable over the past decade.
Data source: UNcomtrade (2021)
Intra-region trade is an important feature of the EU’s textile and apparel industry. Despite the increasing pressure from cost-competitive Asian suppliers, statistics from UNComtrade show that of the EU region’s total US$73.8bn textile imports in 2019, as much as 54.6% were in the category of intra-region trade. Similarly, of EU countries’ total US$204.0bn apparel imports in 2019, as much as 37.4% also came from other EU members. In comparison, close to 98% of apparel consumed in the United States are imported in 2019, of which more than 75% came from Asia (Eurostat, 2021; UNComtrade, 2021).
Regarding EU countries’ textile and apparel trade with non-EU members (i.e., extra-region trade), the United States remained one of the EU’s top export markets and a vital textile supplier (mainly for technical and industrial textiles). Meanwhile, Asian countries served as the dominant apparel sourcing base outside the EU region for EU fashion brands and retailers.
2021 hopefully will be a year of recovery and growthfor the EU textile and apparel industry. According to Euratex, the EU Business Confidence indicator of March 2021 gained momentum, with a confirmed upward trend in the textile industry (+3.8 points), and a modest recovery in the clothing industry (+1.6 points). However, Euratex also noted that EU textile and apparel companies still face daunting challenges and uncertainties in 2021, ranging from the rising raw material price, increasing transportation cost, to political instability in some key sourcing destinations (such as China and Myanmar).
#2: From the readings and your observation, to which extent will automation challenge the conclusions of the “flying geese model” and the evolution pattern of Asian countries’ textile and apparel industry over the past decades?
#3: It could be a crazy idea, but given the current business environment, what would the textile and apparel supply chain in Asia look like without “Made in China”? What would be the implications for US fashion companies sourcing strategies?
#4: RCEP members are with a diverse competitiveness in textile and apparel production and exports. Several leading Asian apparel-exporting countries are not RCEP members (such as Bangladesh). Is it unavoidable that RCEP will create BOTH winners and losers for textile and apparel trade? How so?
#5: Is the growth model and development path of Asian countries’ textile and apparel industry an exception—meaning it is challenging to apply it to the rest of the world, such as the Western Hemisphere and Africa? What is your view?
#6: What is your outlook of Asia as a textile and apparel-sourcing base in the post-Covid world? Why?
(Welcome to our online discussion. For students in FASH455, please address at least two questions and mention the question number (#) in your reply)


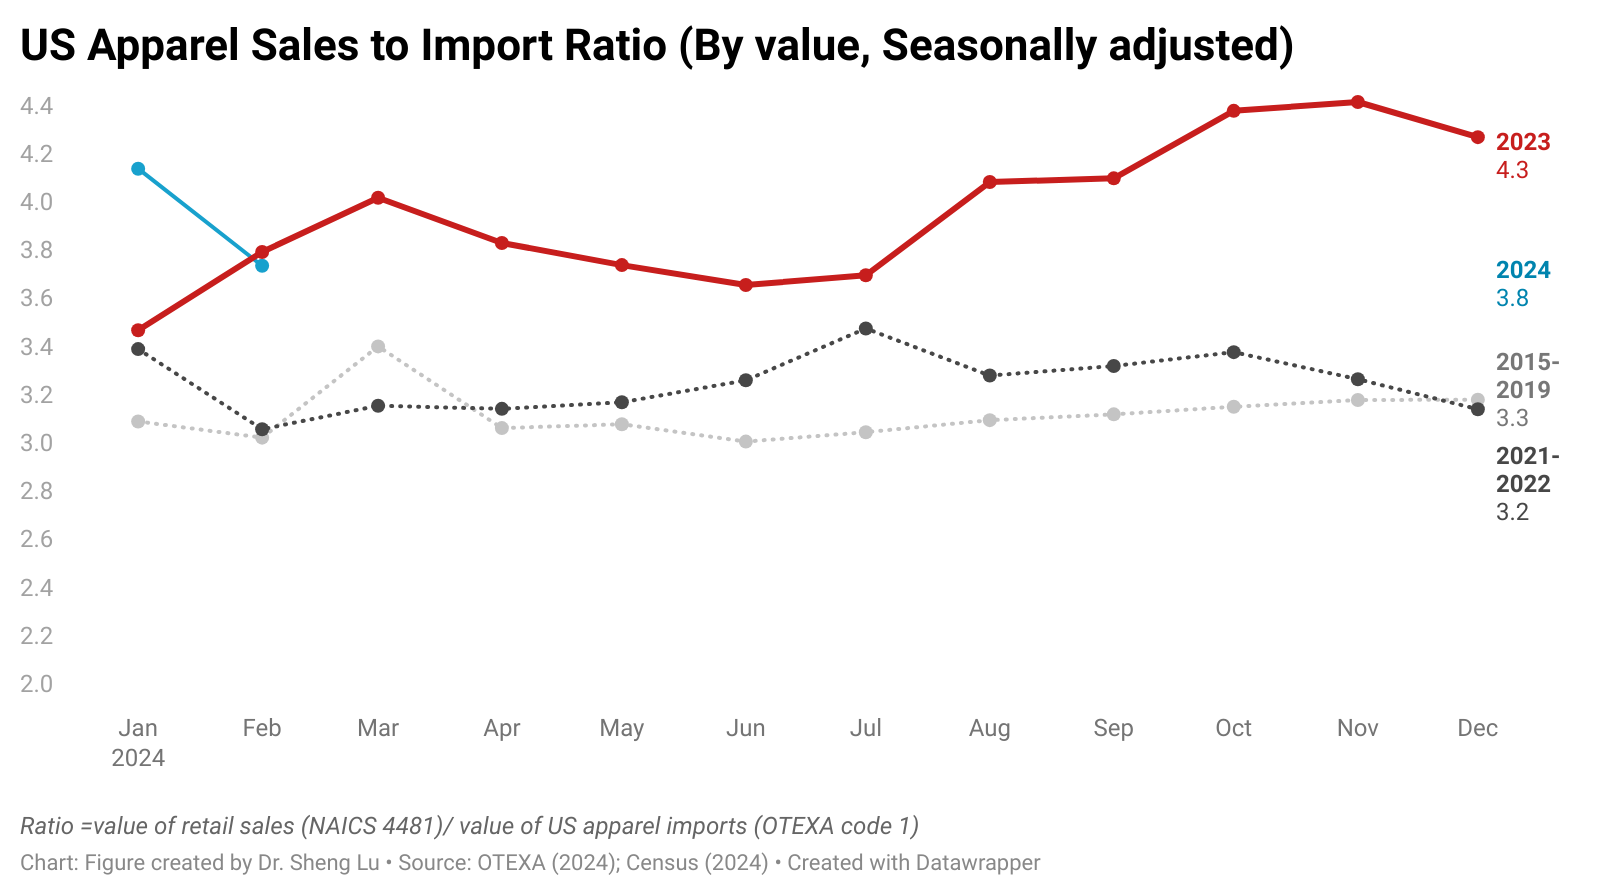
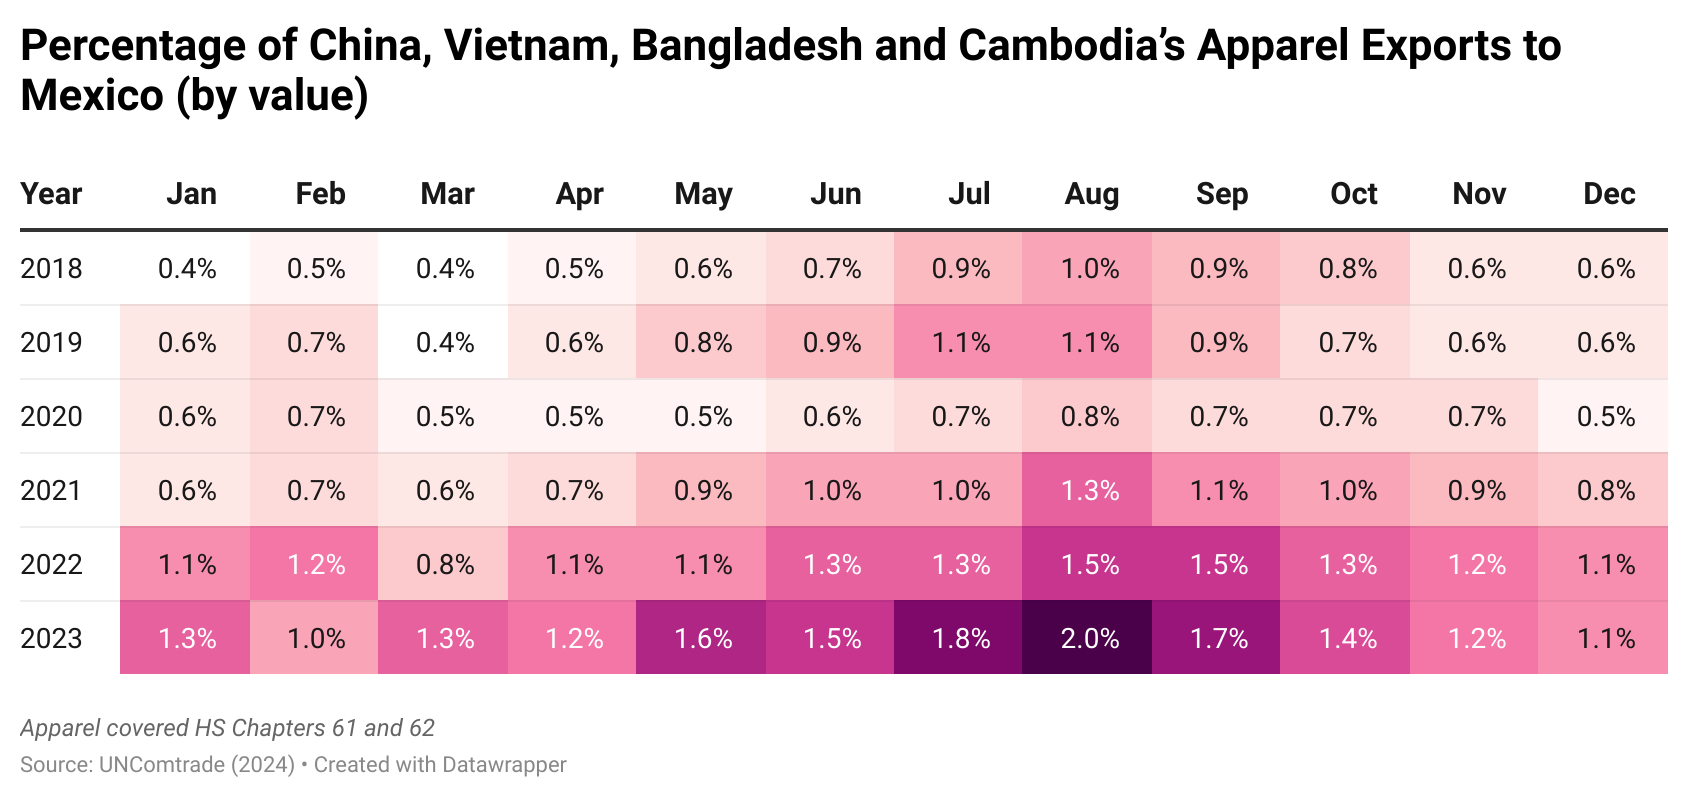


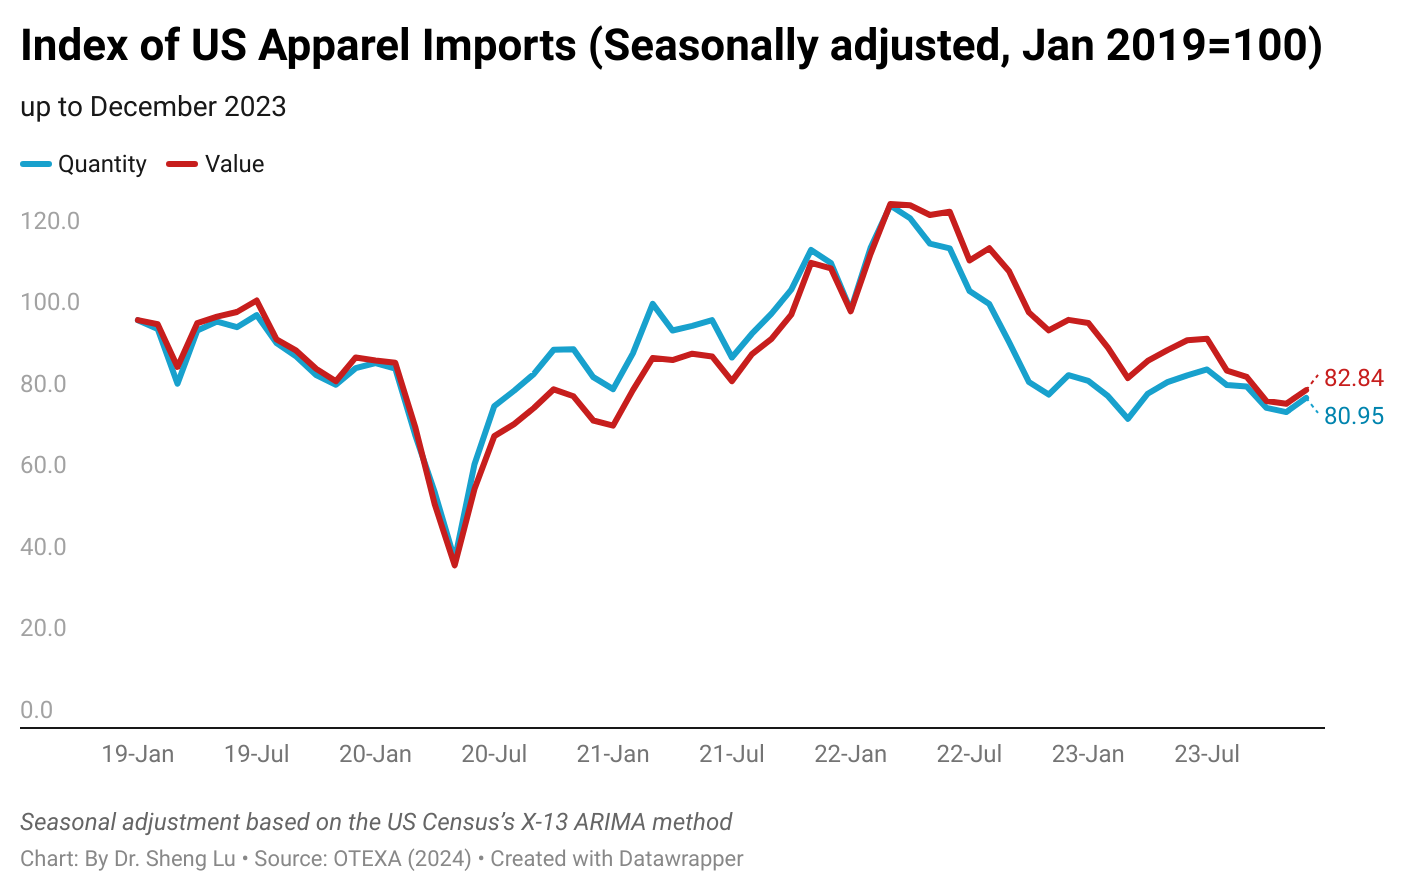


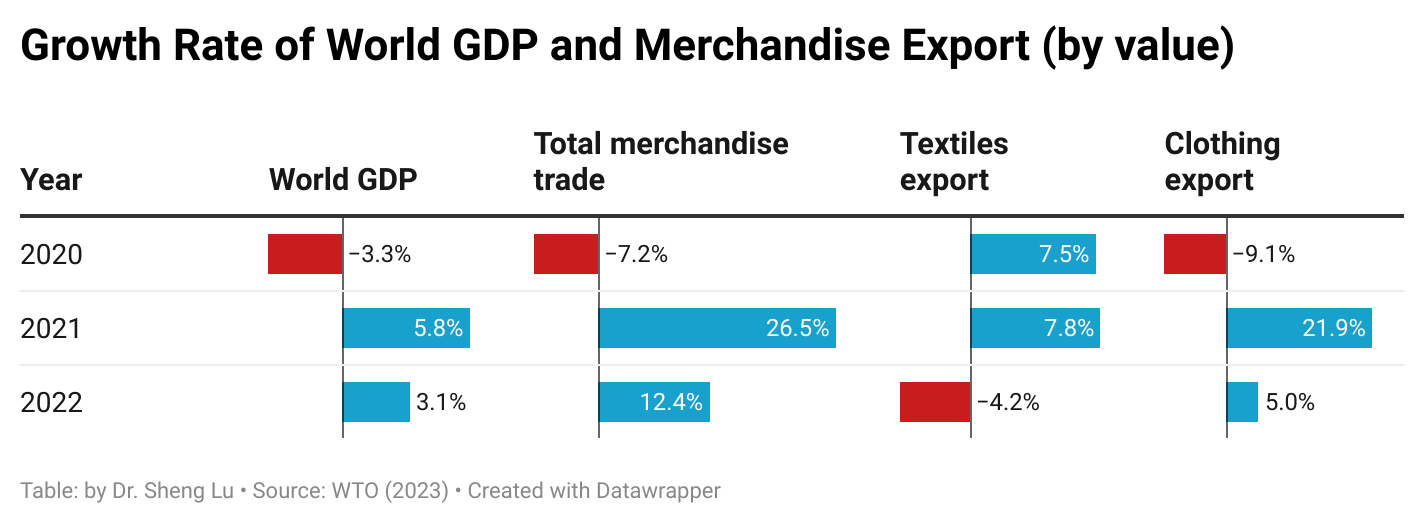

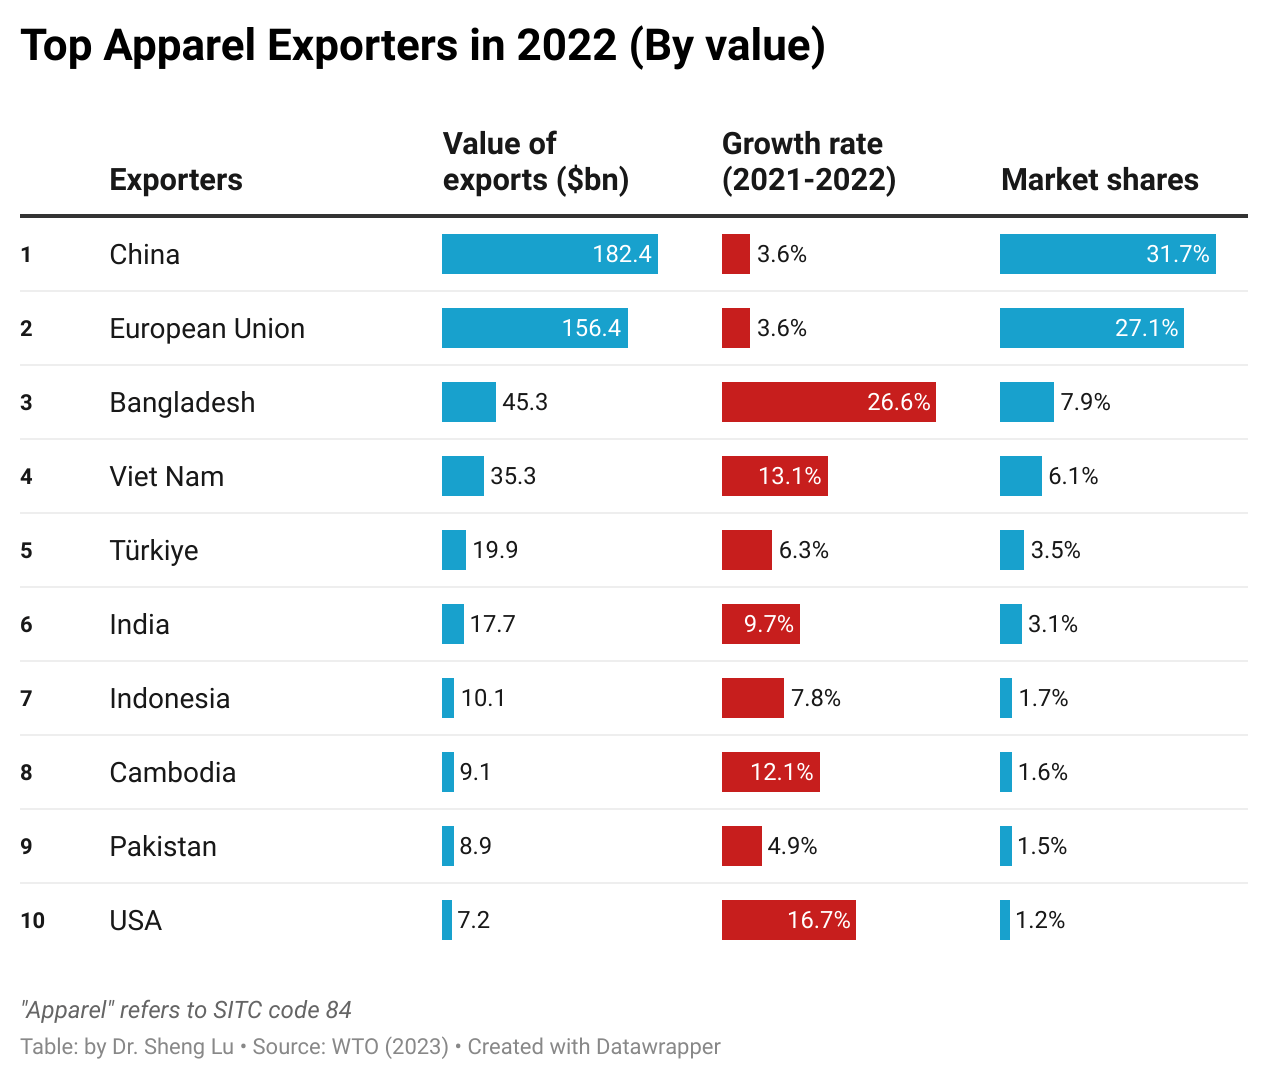
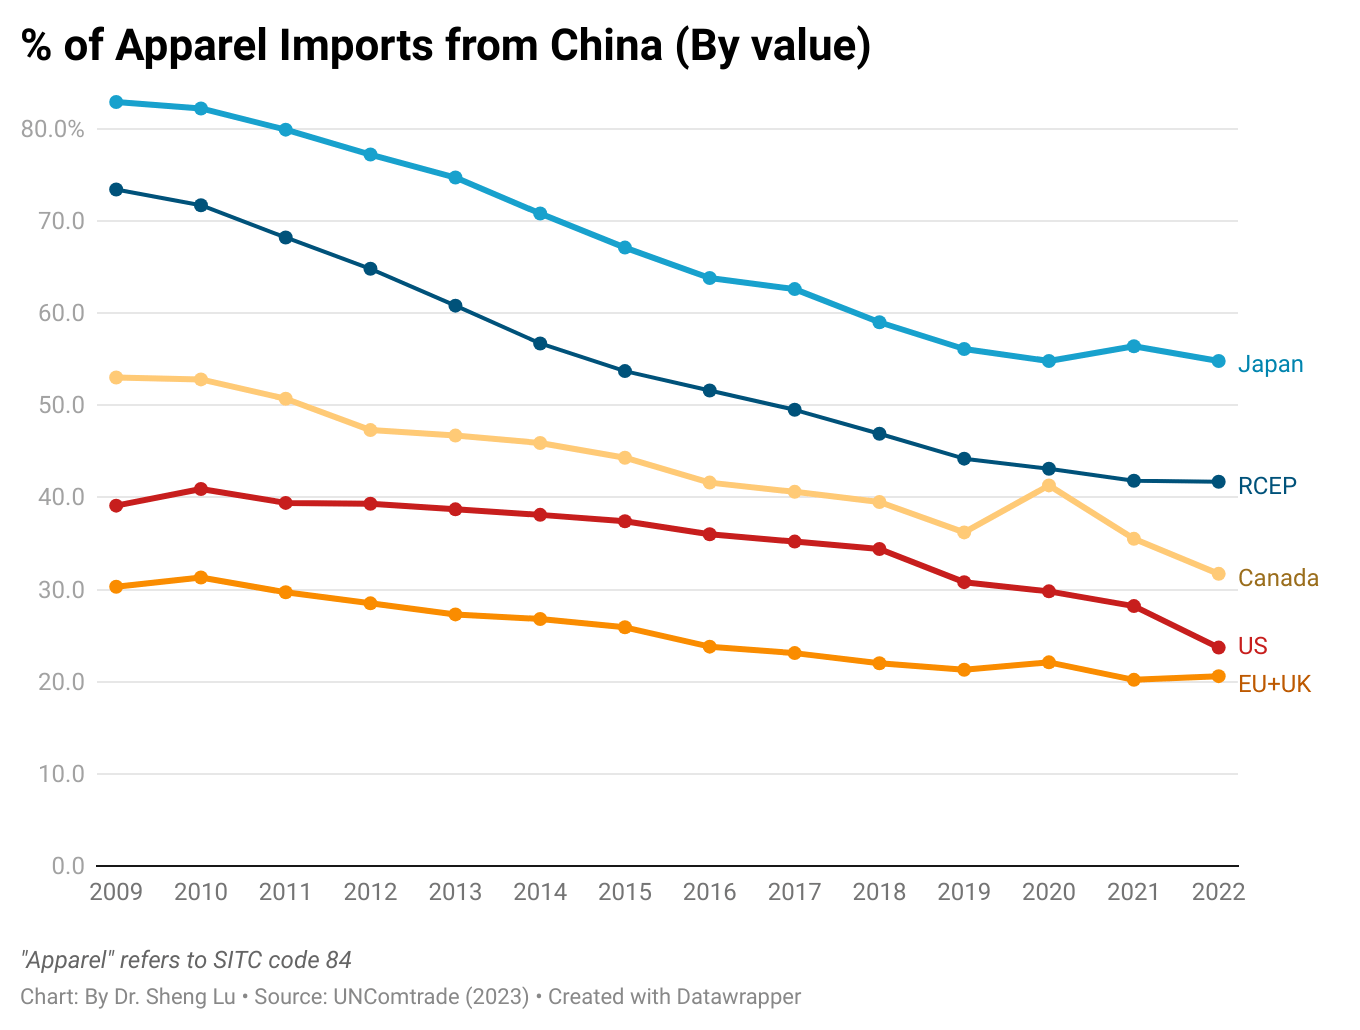


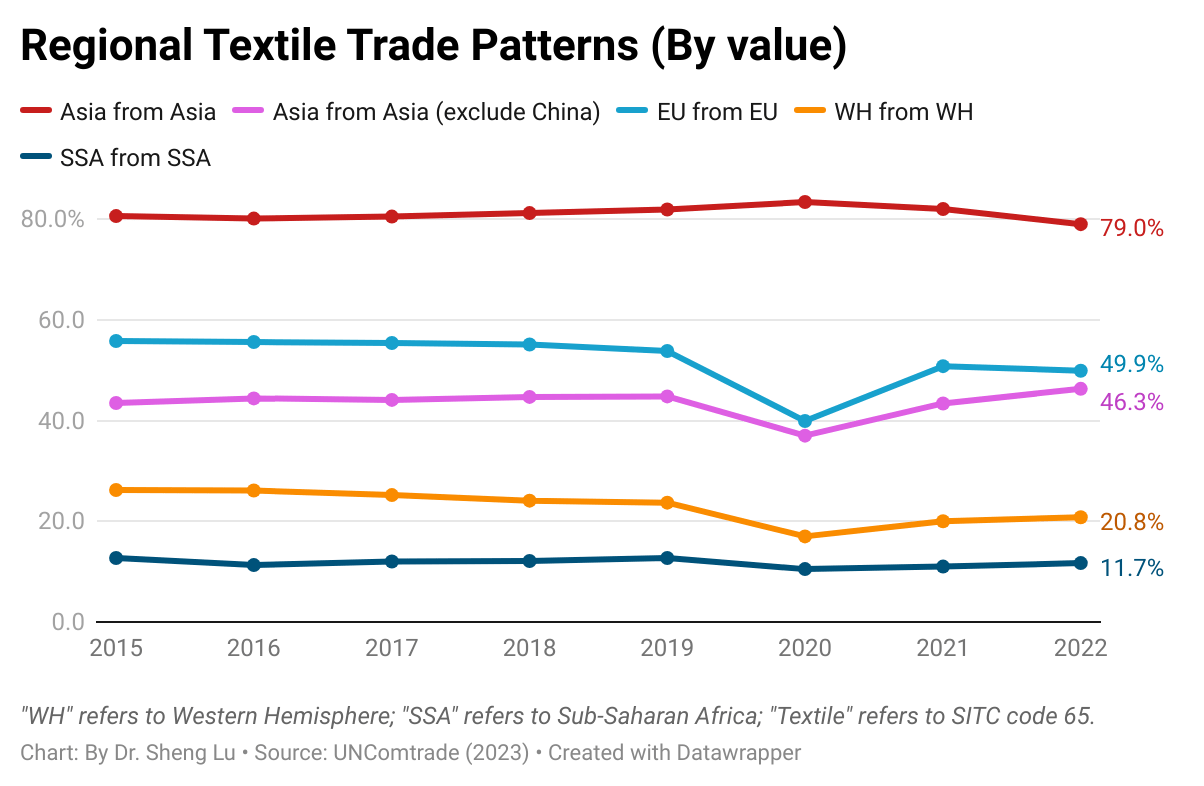

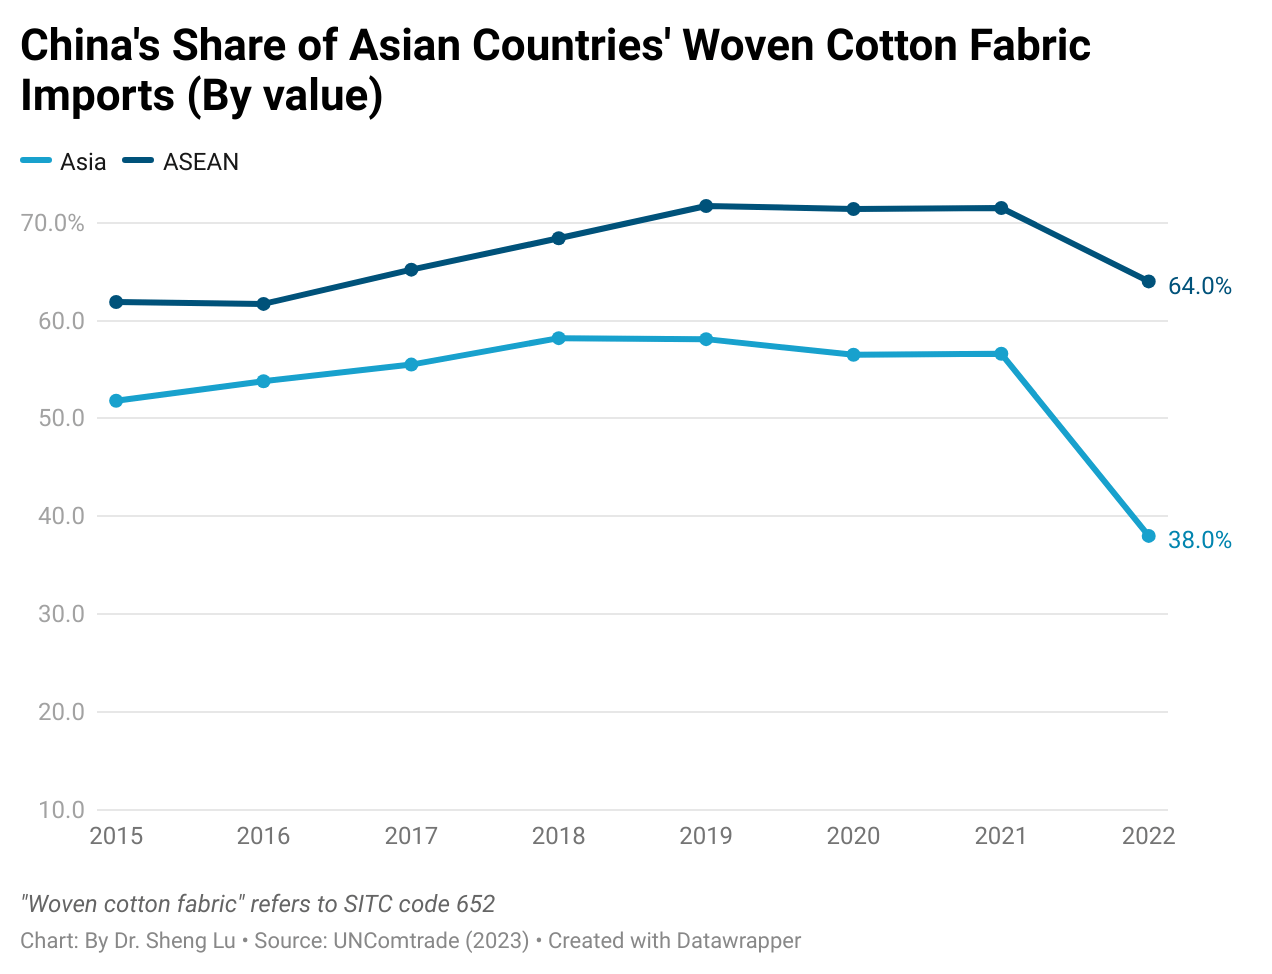



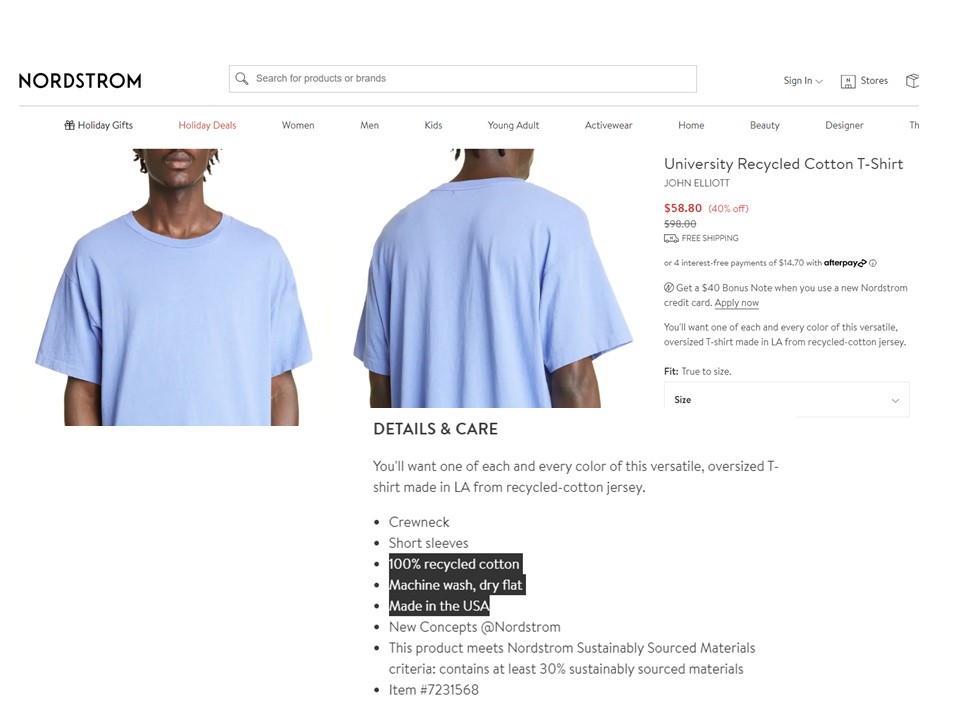


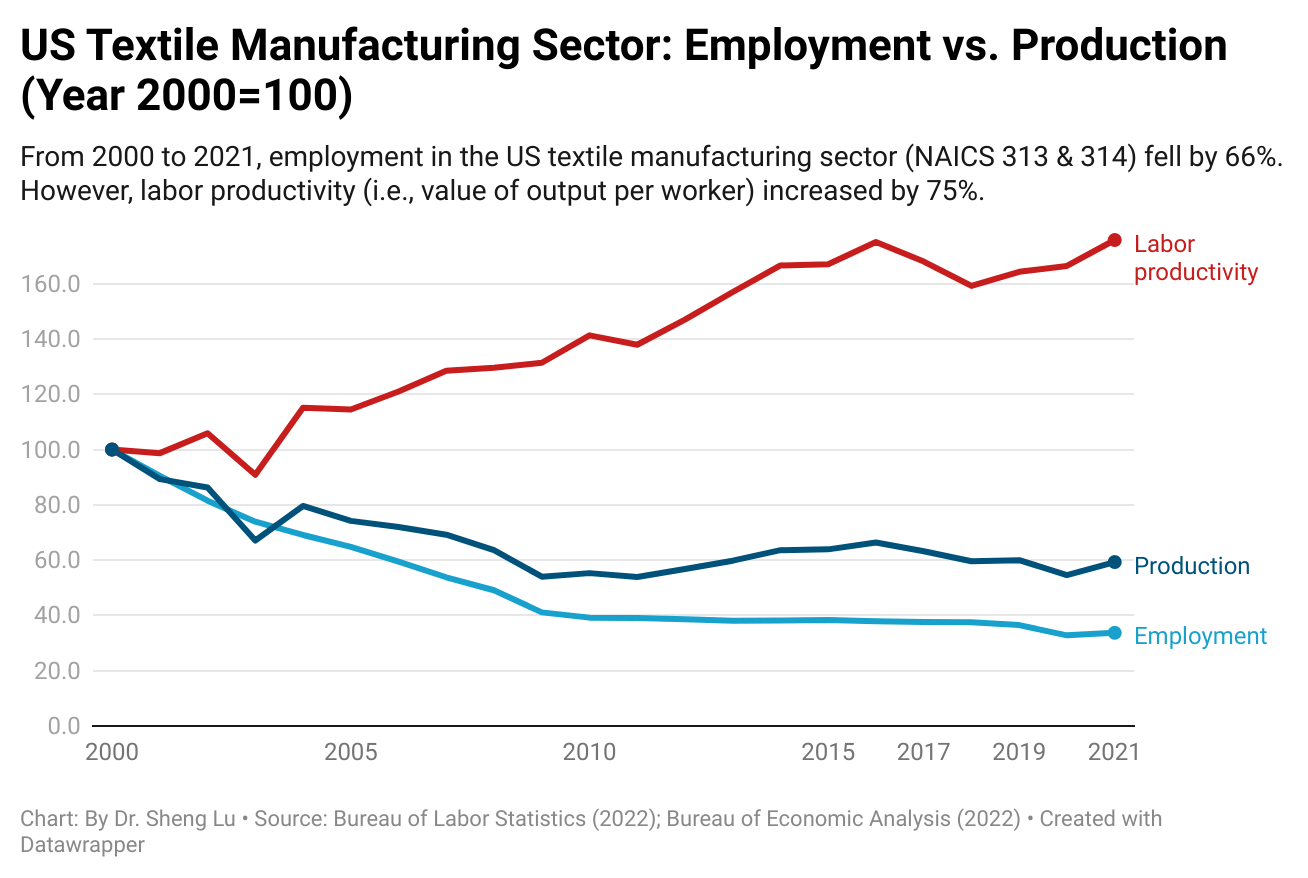
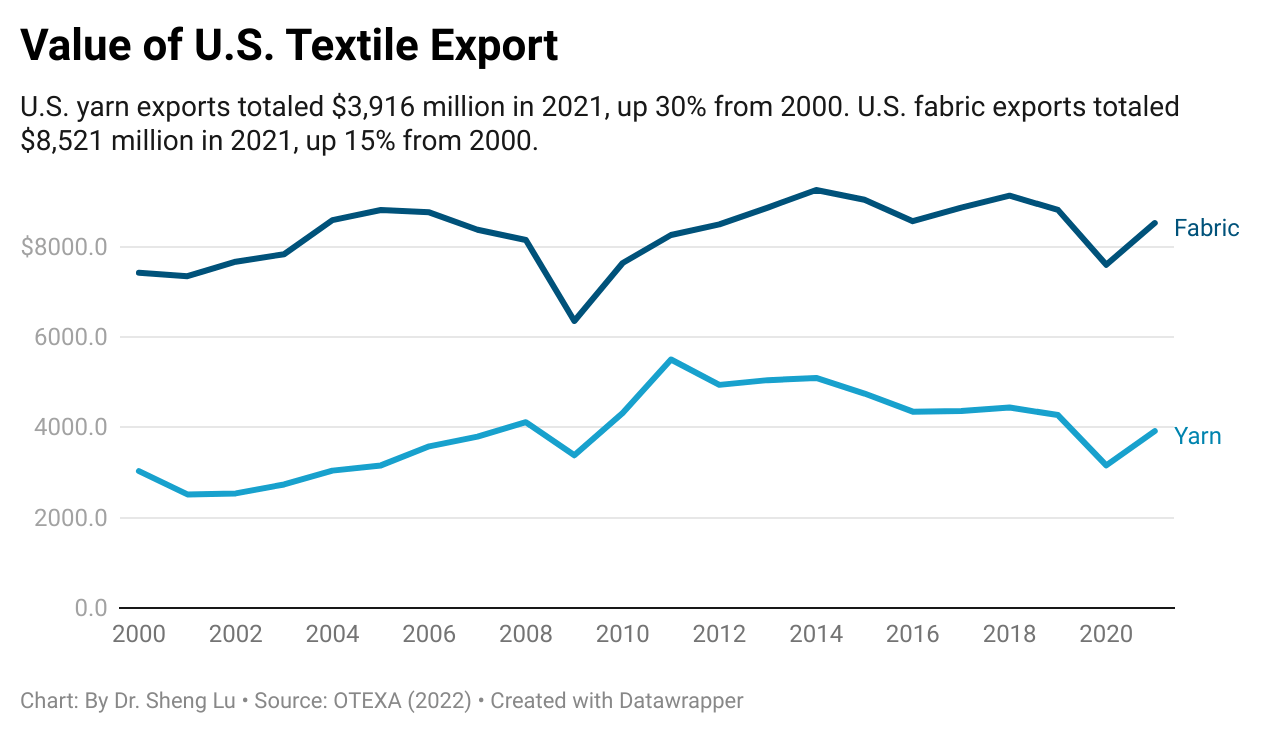
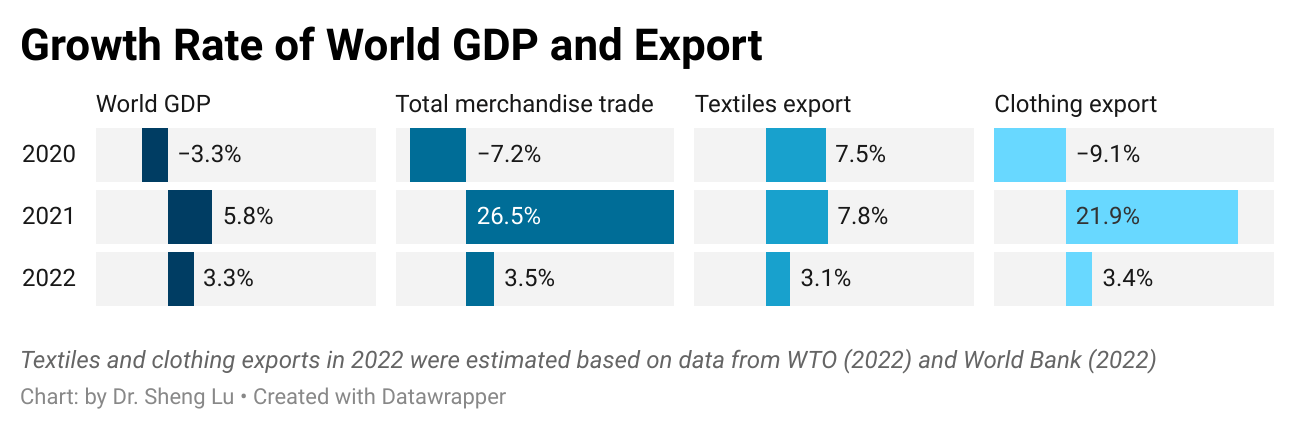

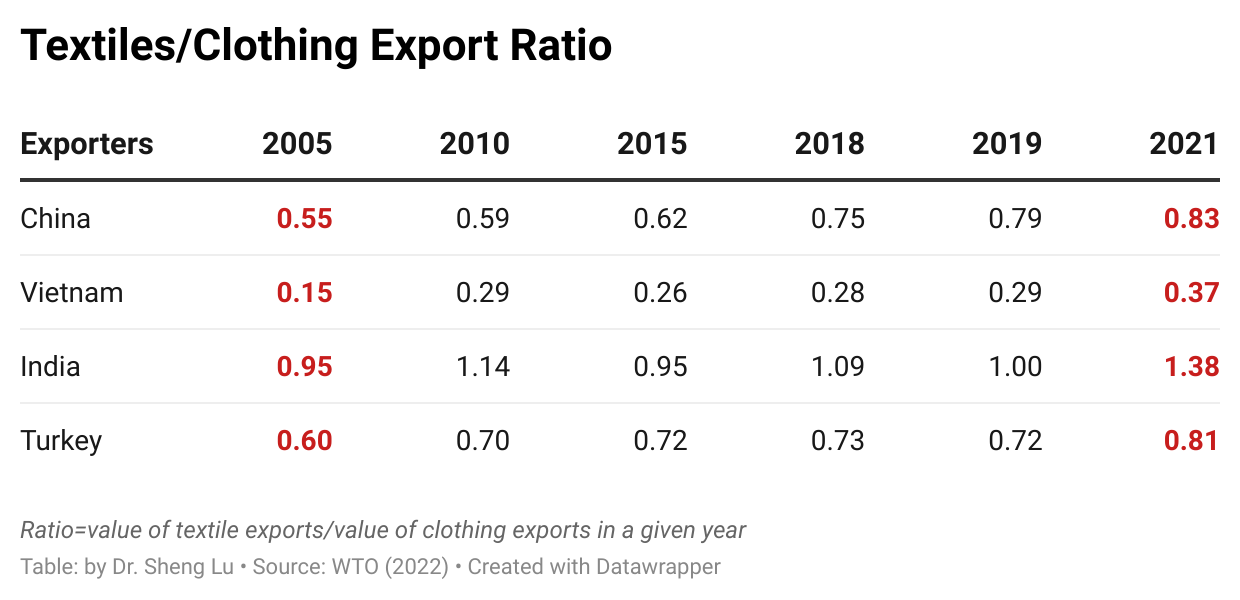


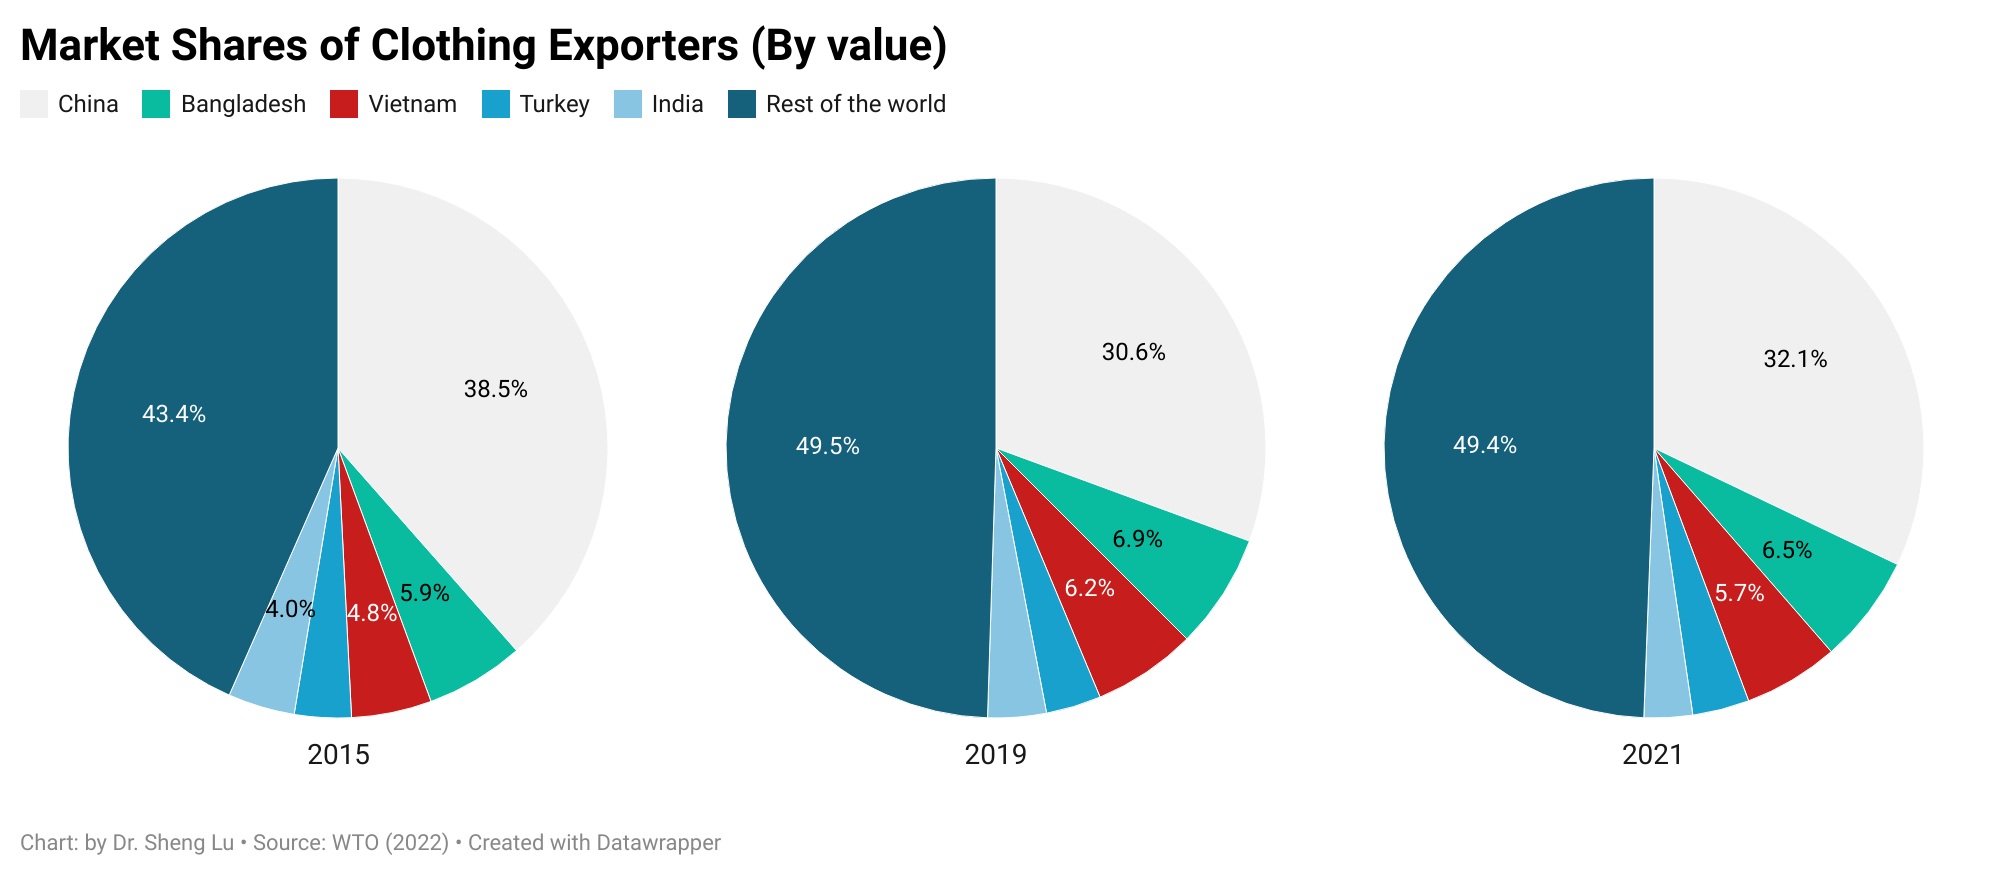

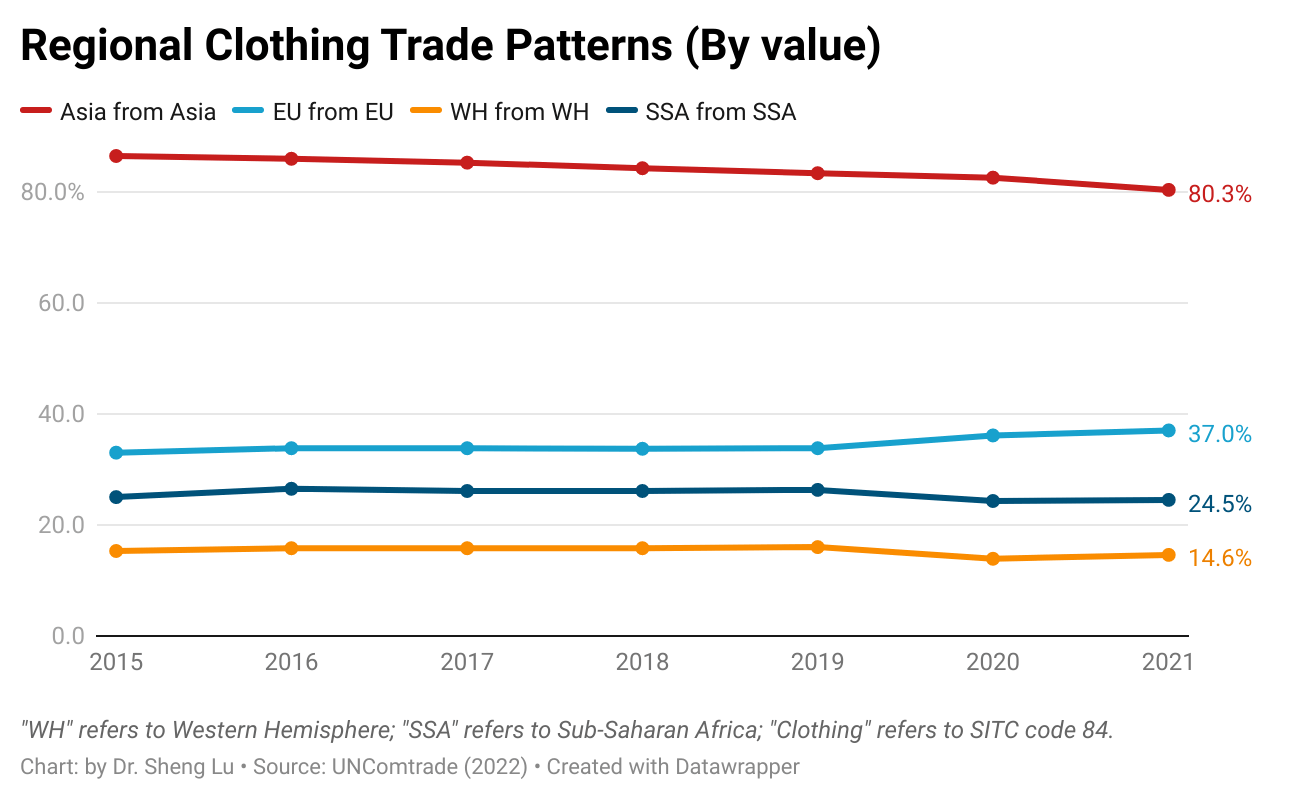
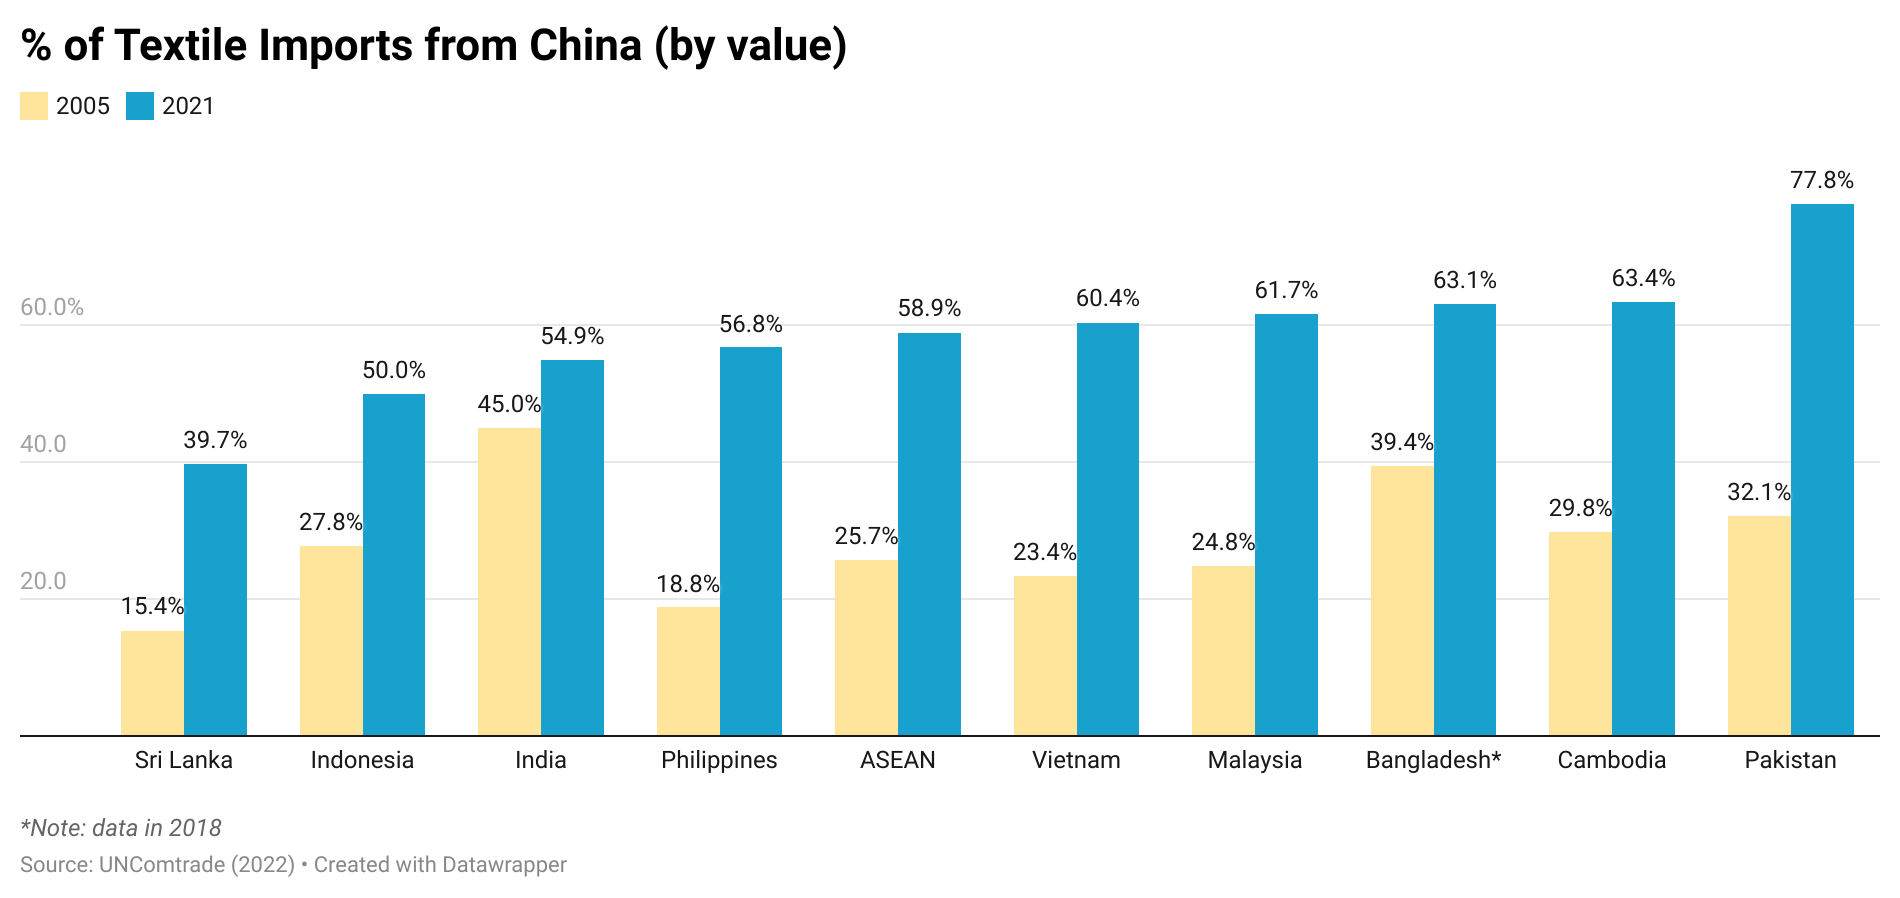

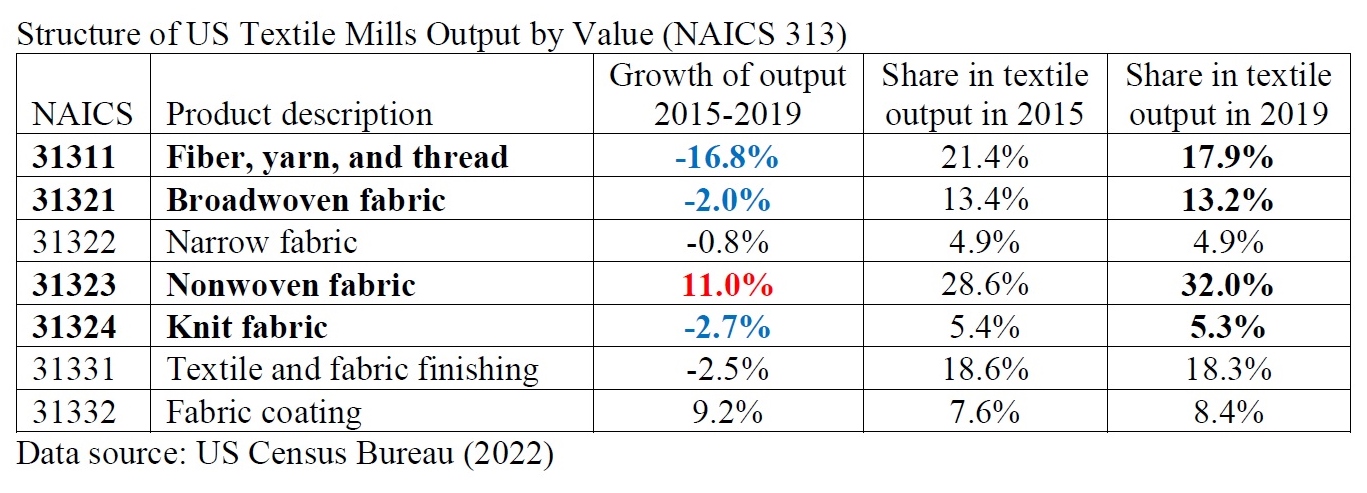


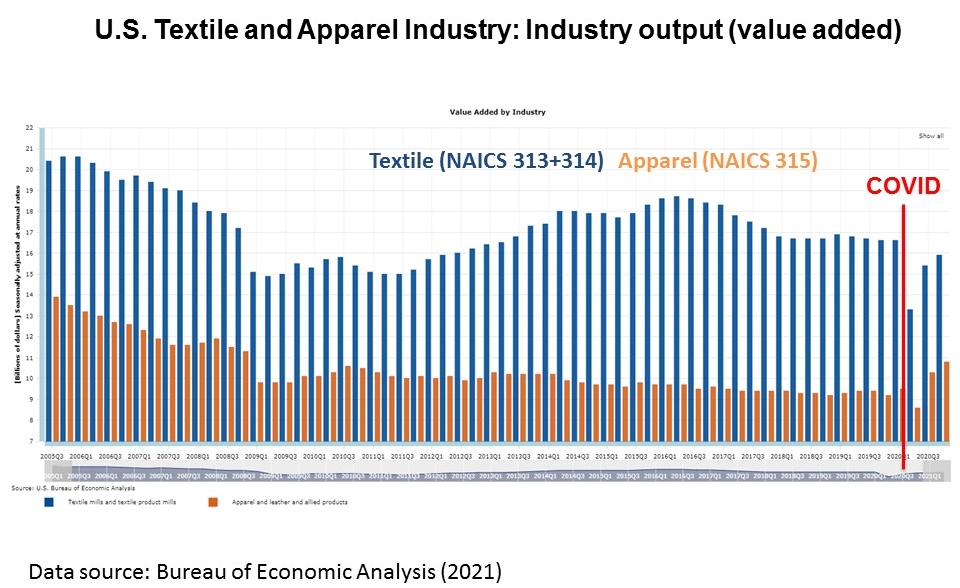
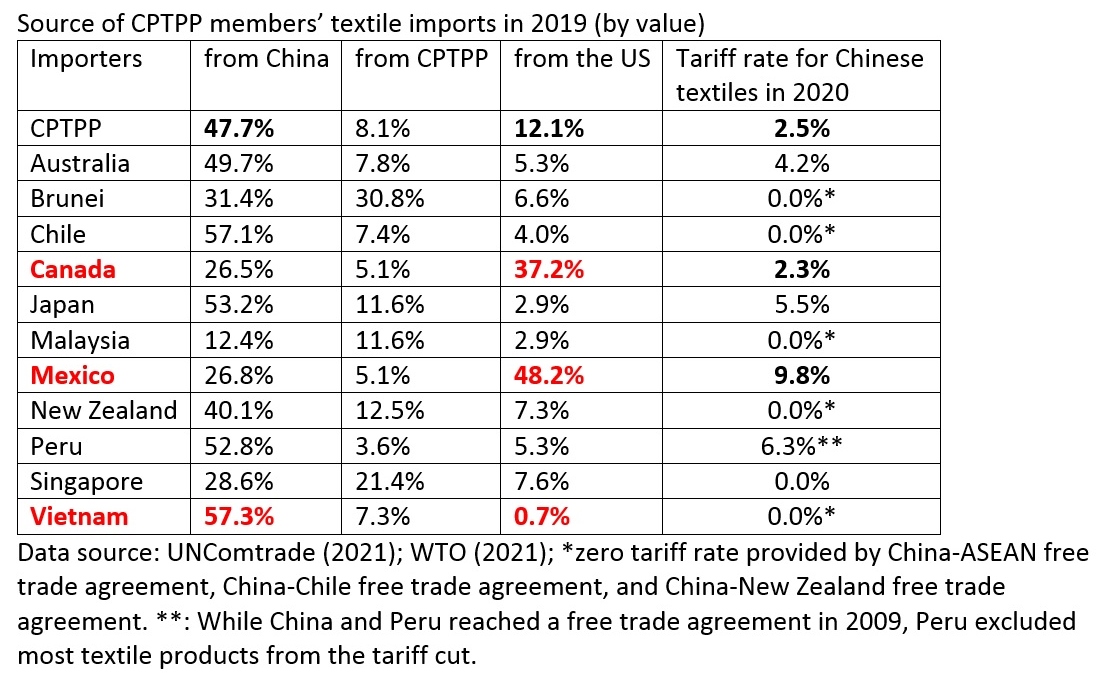
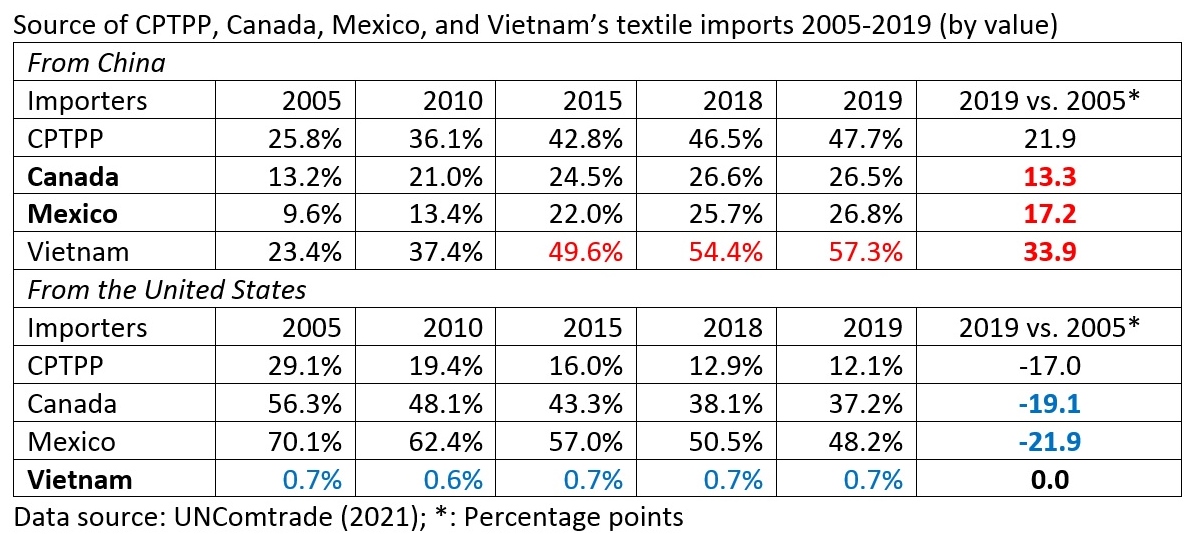
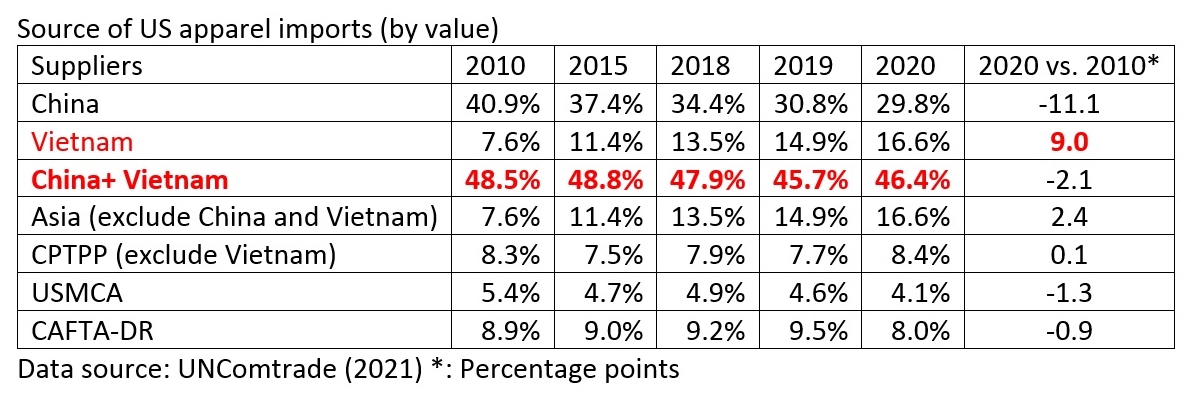


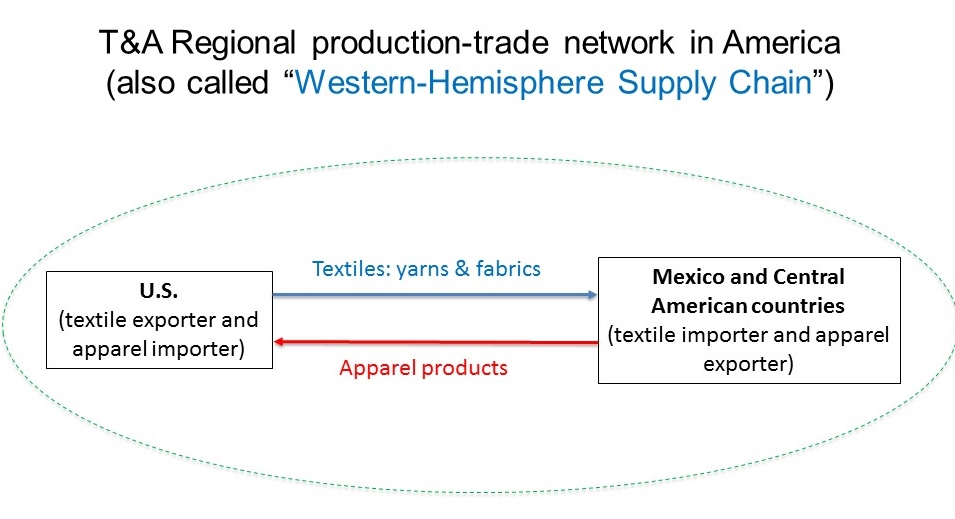
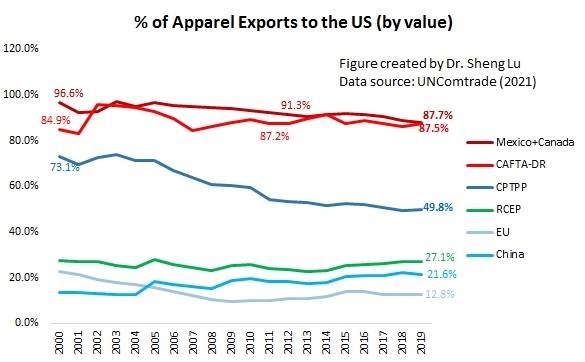
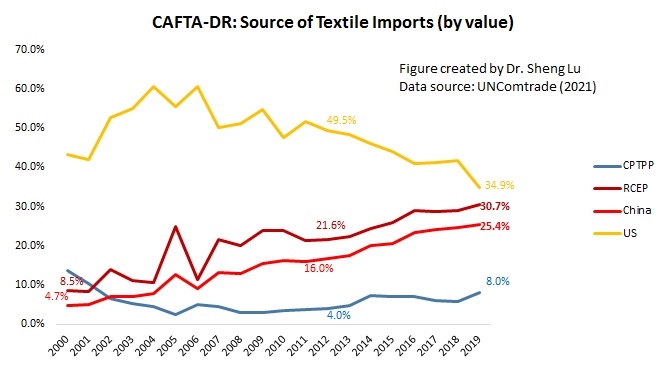
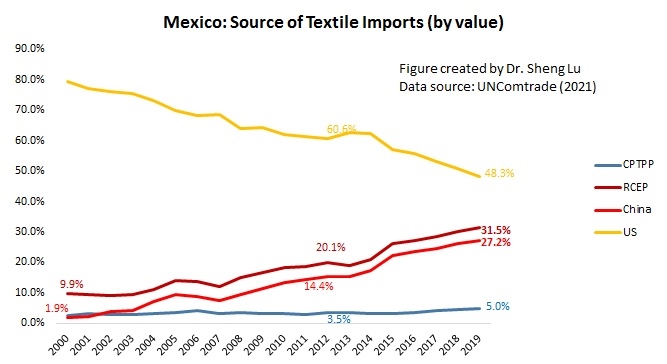


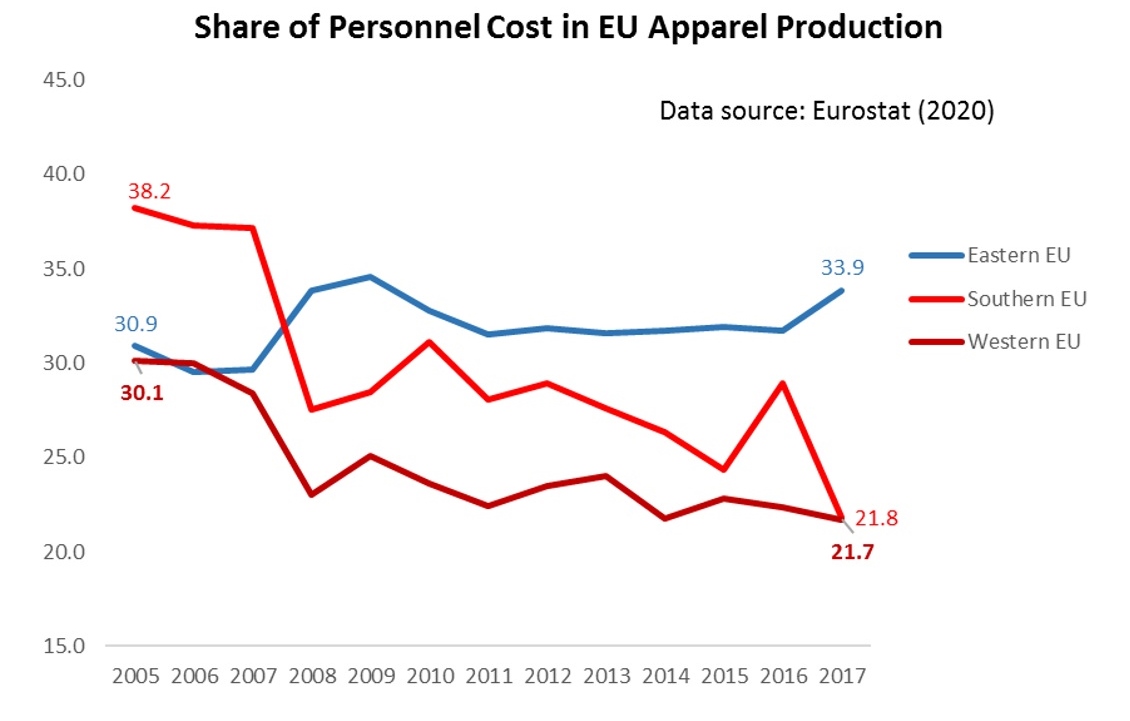
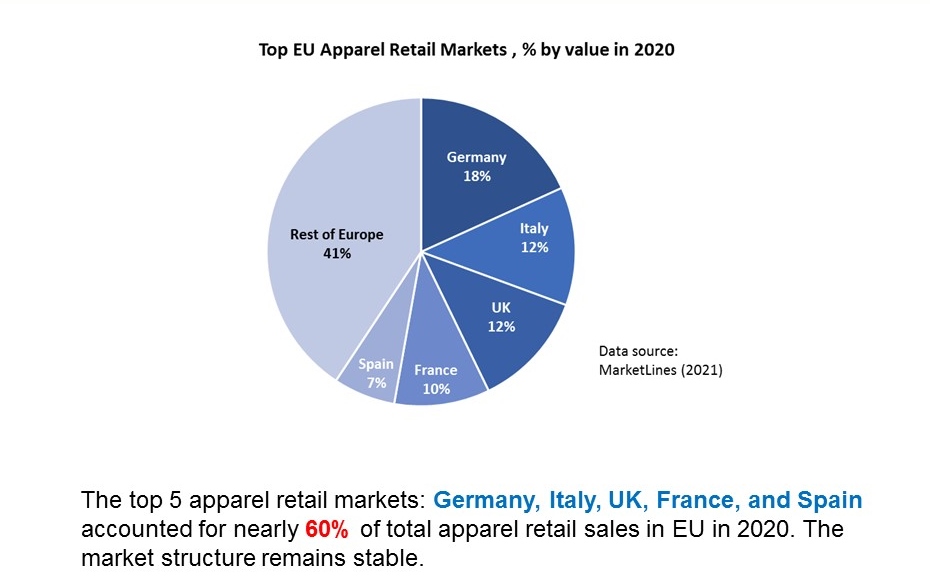


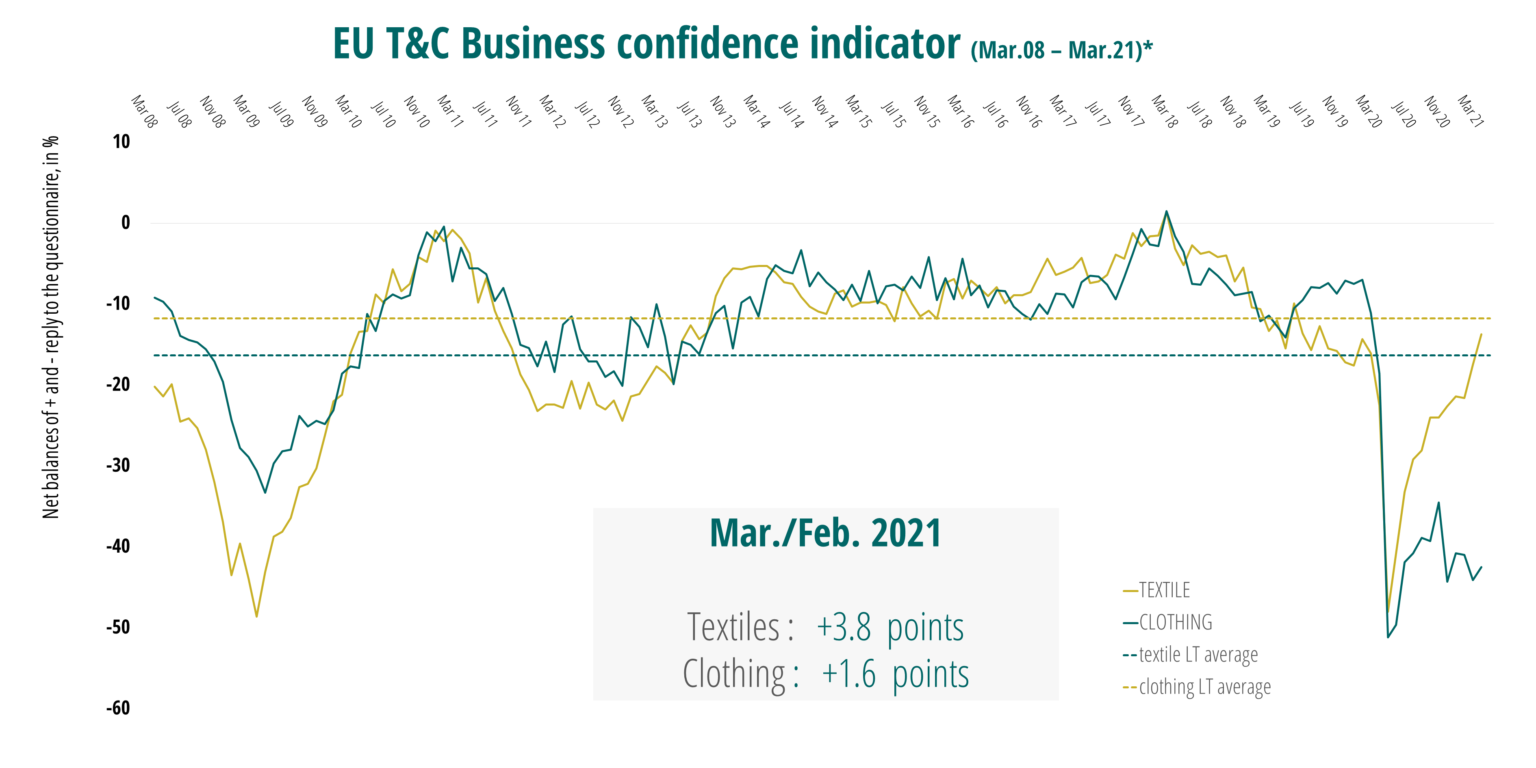
 FASH455 Global Apparel & Textile Trade and Sourcing

